



 Chat with AI
Exam 14: Long-Term Liabilities and Receivables

Exam 1: The Environment of Financial Reporting41 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System87 Questions
Exam 4: The Balance Sheet and the Statement of Changes in Stockholders Equity78 Questions
Exam 5: The Income Statement and the Statement of Cash Flows104 Questions
Exam 6: Additional Aspects of Financial Reporting and Financial Analysis95 Questions
Exam 7: Cash and Receivables99 Questions
Exam 8: Inventories: Cost Measurement and Flow Assumptions89 Questions
Exam 9: Inventories: Special Valuation Issues109 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Disposal88 Questions
Exam 11: Depreciation and Depletion103 Questions
Exam 12: Intangibles84 Questions
Exam 13: Current Liabilities and Contingencies99 Questions
Exam 14: Long-Term Liabilities and Receivables140 Questions
Exam 15: Investments101 Questions
Exam 16: Contributed Capital121 Questions
Exam 17: Earnings Per Share and Retained Earnings86 Questions
Exam 18: Income Recognition and Measurement of Net Assets71 Questions
Exam 19: Accounting for Income Taxes74 Questions
Exam 20: Accounting for Postemployment Benefits68 Questions
Exam 21: Accounting for Leases114 Questions
Exam 22: The Statement of Cash Flows62 Questions
Exam 23: Accounting for Changes and Errors86 Questions
Exam 24: Time Value of Money Module72 Questions
Select questions type


The proper procedure for computing the amortization of a premium using the effective interest method includes multiplying
(Multiple Choice)
4.9/5  (68)
(68) Which of the following is always equal to the face rate of interest?
(Multiple Choice)
4.8/5 (81)
(81) When the market rate of interest is greater than the contract rate of interest, the bonds should sell at
(Multiple Choice)
4.9/5 (70)
(70) Exhibit 14-10 Elaine, Inc.issued a seven-year non-interest-bearing note with a face value of $20, 000 and received $11, 670.Actuarial information for seven periods is as follows:
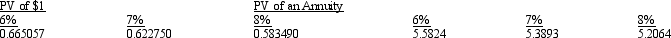 -Refer to Exhibit 14-10.Interest expense for the first year is
 (Multiple Choice)
4.8/5 (82)
(82) Interest expense recognized each period on zero-coupon bonds sold at a discount is equal to the
(Multiple Choice)
4.8/5 (87)
(87) Exhibit 14-12 Shaw owes Lawrence Co.$15, 000 on a note payable, plus $3, 000 of unpaid interest.Lawrence agrees to accept equipment in full settlement of the debt.The equipment is recorded on Shaw's books at $12, 000, and it is currently worth $14, 200.
-
Refer to Exhibit 14-12.What total amounts of extraordinary gains should be recorded by Shaw on this troubled debt restructuring?
(Multiple Choice)
4.9/5 (92)
(92) On January 1, 2010, Saldano, Inc.issued $50, 000 of ten-year 8% bonds for $43, 800.Interest was payable semiannually.The effective yield was 10%.The effective interest method of discount amortization was used.What amount of interest expense should be recorded for the six-month period ending December 31, 2010?
(Multiple Choice)
4.8/5 (74)
(74) Exhibit 14-7 On January 1, 2010, Bubbles, Inc.sold $200, 000 of its 12% five-year bonds to yield 10%.Interest is paid each January 1 and July 1, and effective interest amortization is used.On May 1, 2012, Bubbles, retired $100, 000 of the bonds at 104.The book value of the bonds on December 31, 2011, was $212, 926.
-
Refer to Exhibit 14-7.Which of the following would be included in the interest accrual entry?
(Multiple Choice)
5.0/5 (75)
(75) Exhibit 14-1 Alfred issued 9%, ten-year bonds dated January 1, 2010, with a face value of $100, 000 at 102 plus accrued interest on March 1, 2010.Alfred amortizes premiums and discounts using the straight-line method.Expenses connected with the issue totaled $5, 000 and were deducted in arriving at the net proceeds.
-
Refer to Exhibit 14-1.Assuming interest is paid semiannually on January 1 and July 1, the balance of the interest expense account (to the nearest dollar)after the July 1, 2010, entry would be
(Multiple Choice)
5.0/5 (75)
(75) Exhibit 14-4 A $300, 000, ten-year, 6% bond issue was sold to yield 7% interest payable annually.Actuarial information for 10 periods is as follows:
6\% 7\% Present value of 1 .558 .508 Present value of an anmuity of 1 7.360 7.024
- Refer to Exhibit 14-4.These bonds sold at
(Multiple Choice)
4.8/5 (82)
(82) Exhibit 14-1 Alfred issued 9%, ten-year bonds dated January 1, 2010, with a face value of $100, 000 at 102 plus accrued interest on March 1, 2010.Alfred amortizes premiums and discounts using the straight-line method.Expenses connected with the issue totaled $5, 000 and were deducted in arriving at the net proceeds.
-
Refer to Exhibit 14-1.The entry to record the issue would include a debit to Cash for
(Multiple Choice)
4.9/5 (87)
(87) Under current GAAP, the rate of interest assigned to non-interest-bearing notes is
(Multiple Choice)
4.9/5 (67)
(67) Related to long-term liabilities, reading the notes to the financial statements is important because they contain
(Multiple Choice)
4.9/5 (85)
(85) When a company issues bonds, the selling price of the bonds is determined by a number of factors.Two factors that affect bond prices are the bond's contract (stated)rate and its effective yield (effective rate).
Required:
Explain the effect on a bond's selling price caused by the stated and effective rates.
(Essay)
4.9/5 (70)
(70) For which of the following types of bonds is interest expense recognized each year even though no interest is paid?
(Multiple Choice)
4.8/5 (78)
(78) How do the classification requirements of IFRS for instruments as financial liabilities versus equity differ from those of GAAP?
(Essay)
4.8/5 (84)
(84) If a company sells its bonds at less than face value, the effective interest rate is
(Multiple Choice)
4.8/5 (78)
(78) Hoosier Co.sold $300, 000 of 10% bonds for $311, 600.Each $1, 000 bond carried ten warrants and each warrant allowed the holder to acquire one share of $10 par value common stock for $25 a share.After the issuance of the securities, the bonds were quoted at 103.5 and each warrant was quoted at $9.
Required:
Prepare the entry to record the sale of the bonds.
(Essay)
4.8/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)