



 Chat with AI
Exam 21: Accounting for Leases

Exam 1: The Environment of Financial Reporting41 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System87 Questions
Exam 4: The Balance Sheet and the Statement of Changes in Stockholders Equity78 Questions
Exam 5: The Income Statement and the Statement of Cash Flows104 Questions
Exam 6: Additional Aspects of Financial Reporting and Financial Analysis95 Questions
Exam 7: Cash and Receivables99 Questions
Exam 8: Inventories: Cost Measurement and Flow Assumptions89 Questions
Exam 9: Inventories: Special Valuation Issues109 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Disposal88 Questions
Exam 11: Depreciation and Depletion103 Questions
Exam 12: Intangibles84 Questions
Exam 13: Current Liabilities and Contingencies99 Questions
Exam 14: Long-Term Liabilities and Receivables140 Questions
Exam 15: Investments101 Questions
Exam 16: Contributed Capital121 Questions
Exam 17: Earnings Per Share and Retained Earnings86 Questions
Exam 18: Income Recognition and Measurement of Net Assets71 Questions
Exam 19: Accounting for Income Taxes74 Questions
Exam 20: Accounting for Postemployment Benefits68 Questions
Exam 21: Accounting for Leases114 Questions
Exam 22: The Statement of Cash Flows62 Questions
Exam 23: Accounting for Changes and Errors86 Questions
Exam 24: Time Value of Money Module72 Questions
Select questions type


Lessees may classify a lease as one of two types: (1)capital lease, or (2)operating lease.Current GAAP provides the criteria for determining which classification is appropriate.
Required:
Identify the criteria that a lessee uses to classify leases as either capital or operating leases.
(Essay)
4.8/5  (80)
(80) The account Unearned Interest: Leases should be reported on the lessor's financial statements as
(Multiple Choice)
4.9/5 (87)
(87) The lessor should report the Lease Receivable for a sales-type lease on its balance sheet as
(Multiple Choice)
4.7/5 (78)
(78) Exhibit 21-3 On January 1, 2010, Quincy Company enters into a five-year sales-type lease with Andy Company.The lease requires Andy to make five annual payments at the beginning of the year, with the first payment due January 1, 2010.The lease includes a bargain purchase price of $10, 000.Quincy requires a 10% rate of return.The cost to Quincy of the property is $100, 000, and it has a fair value of $150, 000.Present value factors for a 10% interest rate are as follows:
Present value of \ 1 for n=1 0.909091 Present value of \ 1 for n=5 0.620921 Present value of an ordinary annuity for n=5 3.790787 Present value of an annuity due for n=5 4.169865
- Refer to Exhibit 21-3.The sales revenue to be recognized by Quincy on January 1, 2010, is
(Multiple Choice)
4.8/5 (79)
(79) Which of the following statements regarding the calculation of the lessee's depreciation expense for a capital lease is true?
(Multiple Choice)
4.9/5 (83)
(83) On January 1, Lessee Company incorrectly recorded a 10-year operating lease as a capital lease.The lease requires annual payments.As a result of the recording error, Lessee Company's assets and total liabilities will be Total Assets Total Liabilities I. not affected not affected II. not affected understated III. understated overstated IV. overstated overstated
(Multiple Choice)
4.8/5 (61)
(61) Exhibit 21-1 On January 1, 2010, Victor Company signed a lease agreement requiring six annual payments of $60, 000, beginning December 31, 2010.The lease qualifies as a capital lease.Victor's incremental borrowing rate was 9% and the lessor's implicit rate, known by Victor, was 10%.The present value factors of an ordinary annuity of $1 for six periods for interest rates of 9% and 10% are 4.485919 and 4.355261, respectively.
-
Refer to Exhibit 21-1.The balance of the lease obligation for financial reporting purposes on December 31, 2010, after the lease payment would be (round answers to the nearest dollar)
(Multiple Choice)
4.8/5 (74)
(74) On January 1, Lessor Company incorrectly recorded a sales-type lease as an operating lease.As a result of this error, the reported amount for Lessor Company's property, plant, and equipment leased to others is
(Multiple Choice)
4.9/5 (86)
(86) For a sale-leaseback transaction for which the lease qualifies as a capital lease, the seller-lessee should account for any gain on the sale of the asset as
(Multiple Choice)
4.9/5 (78)
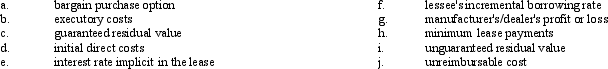
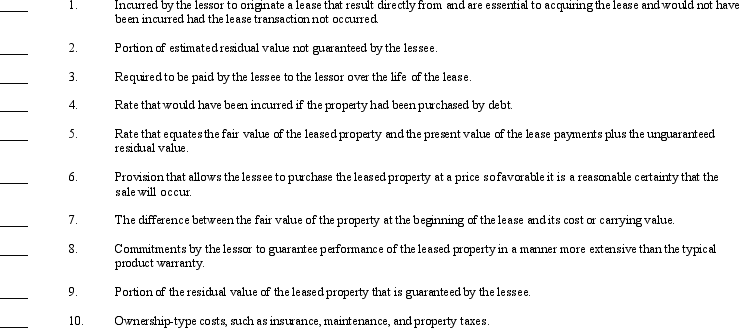
(78) Shown below is a list of key terms (a-j)related to leasing, followed by a series of definitions (1-10):
 Required:
Match each term to its definition by placing the appropriate letter in the space provided.
Required:
Match each term to its definition by placing the appropriate letter in the space provided. (Essay)
4.9/5 (76)
(76) On January 1, 2010, Rachel Company leased equipment by signing a five-year lease that required five payments of $30, 000 due on December 31 of each year.The equipment remains the property of the lessor at the end of the lease, and Rachel does not guarantee any residual value.Using a rate of 7%, Rachel capitalized the lease on January 1, 2010, in the amount of $123, 006.What is the amount of interest expense Rachel should report on its 2011 income statement?
(Multiple Choice)
4.8/5 (75)
(75) Exhibit 21-2 On January 1, 2010, Maury Company leased equipment, signing a five-year lease that requires annual lease payments of $20, 000.The lease qualifies as a capital lease.The payments are made at year-end, and the first payment will be made at December 31, 2010.In addition, Maury guarantees the residual value to be $10, 000 at the end of the lease term.Maury correctly uses the lessor's implicit interest rate, which is 12%.The present value factors for five periods at 12% are as follows:
Present value of \ 1 0.567427 Present value of ordinary annuity of \ 1 3.604776
- Refer to Exhibit 21-2.The interest expense associated with the leased equipment for the year ending December 31, 2010, is
(Multiple Choice)
4.9/5 (79)
(79) As a generalized statement regarding lease accounting, which statement best describes U.S.versus international accounting principles?
(Multiple Choice)
4.8/5 (79)
(79) The lease term includes the fixed non-cancellable term of the lease plus
(Multiple Choice)
4.9/5 (68)
(68) A direct financing lease differs from a sales-type lease in that
(Multiple Choice)
4.8/5 (90)
(90) On January 1, 2010, Marty Inc.leased equipment by signing a five-year lease that required five payments of $60, 000 due on January 1 of each year with the first payment due January 1, 2010.The equipment remains the property of the lessor at the end of the lease and Marty does not guarantee any residual value.Marty accounted for the lease as an operating lease, and using a rate of 10%, determined its present value on January 1, 2010, to be $250, 194.What is the amount of current lease liability Marty should report on its December 31, 2010 balance sheet?
(Multiple Choice)
4.8/5 (63)
(63) On January 1, 2010, Mabel Company leased equipment by signing a five-year lease that required five payments of $90, 000 due on December 31 of each year.The equipment remains the property of the lessor at the end of the lease, and Mabel does not guarantee any residual value.Using a rate of 10%, Mabel capitalized the lease on January 1, 2010, in the amount of $341, 172.What is the amount of the lease liability on December 31, 2011?
(Multiple Choice)
4.8/5 (79)
(79) On January 1, 2010, Karen Corp.leased equipment by signing a five-year lease that required five payments of $60, 000 due on December 31 of each year.Karen has a 9% cost of capital and capitalized the lease on January 1, 2010, in the amount of $233, 379.As of December 31, 2012, what amount is reported as the current portion of the lease liability?
(Multiple Choice)
4.8/5 (83)
(83) When is it appropriate for the lessee to use the lessor's implicit rate to discount the minimum lease payments?
(Multiple Choice)
4.9/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)