



 Chat with AI
Exam 7: Cash and Receivables

Exam 1: The Environment of Financial Reporting41 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System87 Questions
Exam 4: The Balance Sheet and the Statement of Changes in Stockholders Equity78 Questions
Exam 5: The Income Statement and the Statement of Cash Flows104 Questions
Exam 6: Additional Aspects of Financial Reporting and Financial Analysis95 Questions
Exam 7: Cash and Receivables99 Questions
Exam 8: Inventories: Cost Measurement and Flow Assumptions89 Questions
Exam 9: Inventories: Special Valuation Issues109 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Disposal88 Questions
Exam 11: Depreciation and Depletion103 Questions
Exam 12: Intangibles84 Questions
Exam 13: Current Liabilities and Contingencies99 Questions
Exam 14: Long-Term Liabilities and Receivables140 Questions
Exam 15: Investments101 Questions
Exam 16: Contributed Capital121 Questions
Exam 17: Earnings Per Share and Retained Earnings86 Questions
Exam 18: Income Recognition and Measurement of Net Assets71 Questions
Exam 19: Accounting for Income Taxes74 Questions
Exam 20: Accounting for Postemployment Benefits68 Questions
Exam 21: Accounting for Leases114 Questions
Exam 22: The Statement of Cash Flows62 Questions
Exam 23: Accounting for Changes and Errors86 Questions
Exam 24: Time Value of Money Module72 Questions
Select questions type


Which of the following is not one of the criteria that must be satisfied for a seller to recognize revenue at the time of sale when the right of return exists?
(Multiple Choice)
4.9/5  (84)
(84) In certain circumstances a company may find it necessary to accelerate the cash inflows potentially generated from its accounts receivable.This can be accomplished through pledging, assigning, or factoring the accounts receivable.
Required:
Explain each of these arrangements.Include in your discussion an explanation of each agreement, who retains the risks and benefits of ownership, whether or not the agreement is formally recorded in the company's accounting records, and how the agreement is disclosed in the company's financial statements.
(Essay)
4.9/5 (72)
(72) When aging of accounts receivable is used, each age group is multiplied by its own estimated uncollectible percentage to determine each age group's estimated uncollectible amount.The sum of the amounts thus determined
(Multiple Choice)
4.8/5 (81)
(81) What entry format is appropriate if sales returns and allowances occur on factored accounts?
(Multiple Choice)
4.9/5 (69)
(69) Which of the following would not be a valid contributing justification for expanding your selling model to include selling goods on account?
(Multiple Choice)
4.8/5 (87)
(87) Compensating balance agreements that legally restrict cash should
(Multiple Choice)
4.9/5 (68)
(68) If the transferor of accounts receivable cannot meet all conditions for a sale, the transferor records the proceeds received as a debit to Cash and records a corresponding credit to a(n)
(Multiple Choice)
4.9/5 (76)
(76) Which of the following is not a basic form of financing agreement to obtain cash from accounts receivable?
(Multiple Choice)
4.8/5 (88)
(88) Which of the following is a key element of internal control over cash payments?
(Multiple Choice)
4.7/5 (78)
(78) On a bank reconciliation, customers' checks that are returned for lack of funds would be
(Multiple Choice)
4.8/5 (77)
(77) Bedford Market's accountant is preparing its May bank reconciliation and has collected the following data: Per Books Per Bank May 1 balance \ 11,600 \ 10,000 May deposits 24,600 21,200 May checks 27,800 29,000 Note collected (includes 10\% interest) -- 4,400 May service charge -- 20 May 31 balance 8,400 6,580 Additionally, deposits in transit and outstanding checks from April's reconciliation were $4, 400 and $2, 800, respectively.
The correct balance for cash at May 31 should be
(Multiple Choice)
4.9/5 (82)
(82) O'Rourke Co.reports assigned accounts receivable of $90, 000 that relate to an unpaid note payable of $40, 000.Correct balance sheet disclosure is
(Multiple Choice)
4.7/5 (65)
(65) Which of the following statements concerning compensating balance agreements is not true?
(Multiple Choice)
4.8/5 (82)
(82) Under U.S.GAAP, a company can designate a receivable, upon initial recognition, to be recognized at fair value without meeting any criteria.IFRS has established qualifying criteria for fair value designation.
Required:
Describe the IFRS qualifying criteria that must be met to designate a receivable as fair value.
(Essay)
4.9/5 (78)
(78) Compensating balance agreements against short-term borrowings that legally restrict the amount of funds shown on the balance sheet should be reported in the
(Multiple Choice)
4.8/5 (69)
(69) A disadvantage of using the gross price method to account for cash discounts extended by the seller to its customer is that
(Multiple Choice)
4.8/5 (75)
(75) Current GAAP requires a company to disclose the fair value of its financial instruments and to disclose all significant concentrations of credit risk due to its financial instruments.The FASB's rationale for this disclosure includes allowing readers to
(Multiple Choice)
4.8/5 (83)
(83) When the net price method is used to record credit sales, the sales discounts not taken account is reported as a(n)
(Multiple Choice)
4.9/5 (76)
(76) The following are transactions of the Morris Company:
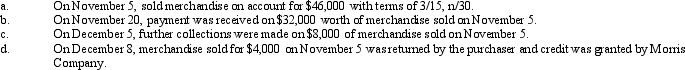 Required:
Record the appropriate amounts under the gross price, net price, and allowance methods in the spaces below.For each method, write the amount to be debited or credited on the appropriate line for each account shown.Indicate that the amount is a debit or credit by placing a (d)or (c)after the amount.
a. To record sale on Nov. 5:
Gross Price Net Price Allowance Method Method Method Cash \_\_\_\_ \_\_\_\_ \_\_\_\_ Accounts Receivable \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Allowance for Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts Not Taken \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Returns and.Allowances: \_\_\_\_ \_\_\_\_ \_\_\_\_ b. To record payment received on Nov. 20
Gross Price Net Price Allowance Method Method Method Cash \_\_\_\_ \_\_\_\_ \_\_\_\_ Accounts Receivable \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Allowance for Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts Not Taken \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Returns and.Allowances: \_\_\_\_ \_\_\_\_ \_\_\_\_ c. To record payment recenved on Dec. 5:
Gross Price Net Price Allowance Method Method Method Cash \_\_\_\_ \_\_\_\_ \_\_\_\_ Accounts Receivable \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Allowance for Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts Not Taken \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Returns and.Allowances: \_\_\_\_ \_\_\_\_ \_\_\_\_ d. To record sales returin on Dec.8:
Gross Price Net Price Allowance Method Method Method Cash \_\_\_\_ \_\_\_\_ \_\_\_\_ Accounts Receivable \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Allowance for Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts Not Taken \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Returns and.Allowances: \_\_\_\_ \_\_\_\_ \_\_\_\_
Required:
Record the appropriate amounts under the gross price, net price, and allowance methods in the spaces below.For each method, write the amount to be debited or credited on the appropriate line for each account shown.Indicate that the amount is a debit or credit by placing a (d)or (c)after the amount.
a. To record sale on Nov. 5:
Gross Price Net Price Allowance Method Method Method Cash \_\_\_\_ \_\_\_\_ \_\_\_\_ Accounts Receivable \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Allowance for Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts Not Taken \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Returns and.Allowances: \_\_\_\_ \_\_\_\_ \_\_\_\_ b. To record payment received on Nov. 20
Gross Price Net Price Allowance Method Method Method Cash \_\_\_\_ \_\_\_\_ \_\_\_\_ Accounts Receivable \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Allowance for Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts Not Taken \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Returns and.Allowances: \_\_\_\_ \_\_\_\_ \_\_\_\_ c. To record payment recenved on Dec. 5:
Gross Price Net Price Allowance Method Method Method Cash \_\_\_\_ \_\_\_\_ \_\_\_\_ Accounts Receivable \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Allowance for Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts Not Taken \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Returns and.Allowances: \_\_\_\_ \_\_\_\_ \_\_\_\_ d. To record sales returin on Dec.8:
Gross Price Net Price Allowance Method Method Method Cash \_\_\_\_ \_\_\_\_ \_\_\_\_ Accounts Receivable \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Allowance for Sales Discounts \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Discounts Not Taken \_\_\_\_ \_\_\_\_ \_\_\_\_ Sales Returns and.Allowances: \_\_\_\_ \_\_\_\_ \_\_\_\_ (Essay)
4.7/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)