



 Chat with AI
Exam 8: A--Perfect Competition

Exam 1: The Art and Science of Economic Analysis162 Questions
Exam 1: Appendix--Understanding Graphs71 Questions
Exam 2: Economic Tools and Economics Systems211 Questions
Exam 3: Economic Decision Makers207 Questions
Exam 4: Demand, Supply, and Markets245 Questions
Exam 5: Elasticity of Demand and Supply244 Questions
Exam 5: Appendix--Price Elasticity and Tax Incidence32 Questions
Exam 6: Consumer Choice and Demand171 Questions
Exam 6: Appendix--Indifference Curves and Utility Maximization107 Questions
Exam 7: Production and Cost in the Firm218 Questions
Exam 8: A--Perfect Competition250 Questions
Exam 8: B--Perfect Competition25 Questions
Exam 9: A--Monopoly249 Questions
Exam 9: B--Monopoly18 Questions
Exam 10: Monopolistic Competition and Oligopoly233 Questions
Exam 11: Resource Markets219 Questions
Exam 12: Labor Markets and Labor Unions218 Questions
Exam 13: Capital, Interest, and Corporate Finance190 Questions
Exam 14: Transaction Costs, Imperfect Information, and Behavioral Economics187 Questions
Exam 15: Economic Regulation and Antitrust Policy179 Questions
Exam 16: Public Goods and Public Choice143 Questions
Exam 17: Externalities and the Environment203 Questions
Exam 18: Income Distribution and Poverty130 Questions
Exam 19: International Trade172 Questions
Exam 20: International Finance226 Questions
Exam 21: Economic Development97 Questions
Select questions type


The motivating force behind an increase in supply in a long-run adjustment to equilibrium is
(Multiple Choice)
4.9/5  (78)
(78) Which characteristic of perfect competition ensures that economic profit will be zero in the long run?
(Multiple Choice)
4.8/5 (58)
(58) Exhibit 8-14 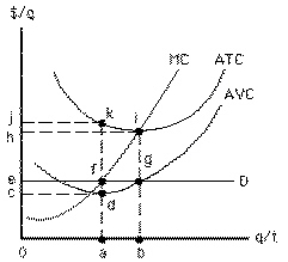 In Exhibit 8-14, what area represents variable cost at the loss-minimizing output?
 (Multiple Choice)
4.9/5 (88)
(88) In the short run, a perfectly competitive firm will always shut down if, at all positive output levels, total revenue is
(Multiple Choice)
4.7/5 (78)
(78) The short-run supply curve of a perfectly competitive firm is the
(Multiple Choice)
4.9/5 (74)
(74) Marginal revenue is the change in total revenue from selling one more unit of output.
(True/False)
4.7/5 (65)
(65) A perfectly competitive firm has a horizontal supply curve in the short run.
(True/False)
4.7/5 (76)
(76) Exhibit 8-18 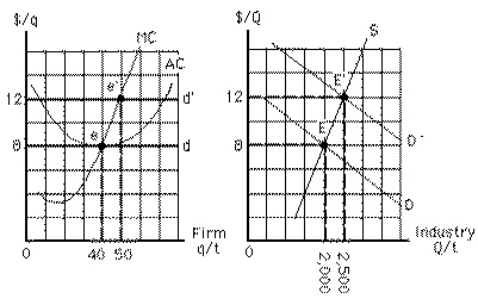 The increase in demand shown in Exhibit 8-18 increases each firm's total revenue
 (Multiple Choice)
4.7/5 (83)
(83) The short-run supply curve of a perfectly competitive firm is
(Multiple Choice)
4.8/5 (76)
(76) If a perfectly competitive firm is incurring a short-run loss, it
(Multiple Choice)
4.7/5 (81)
(81) Exhibit 8-3  Which point in Exhibit 8-3 indicates the quantity at which marginal revenue and marginal cost are equal?
 (Multiple Choice)
4.9/5 (76)
(76) Exhibit 8-1  The perfectly competitive firewood market is composed of 1, 000 identical consumers and 1, 000 identical firms.Exhibit 8-1 shows cost data for one firm and demand data for one consumer.What does the demand curve facing a single firm look like?
 (Multiple Choice)
4.7/5 (87)
(87) A decline in demand in a competitive industry will result in
(Multiple Choice)
4.9/5 (81)
(81) A perfectly competitive firm is allocatively efficient because price is identical to marginal cost at every quantity
(True/False)
5.0/5 (80)
(80) In the short run, a perfectly competitive firm will always shut down if, at all output levels above zero,
(Multiple Choice)
4.7/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)