



 Chat with AI
Exam 20: Short-Term Financing

Exam 1: Multinational Financial Management: an Overview79 Questions
Exam 2: International Flow of Funds75 Questions
Exam 3: International Financial Markets102 Questions
Exam 4: Exchange Rate Determination74 Questions
Exam 5: Currency Derivatives163 Questions
Exam 6: Government Influence on Exchange Rates117 Questions
Exam 7: International Arbitrage and Interest Rate Parity97 Questions
Exam 8: Relationships Among Inflation, Interest Rates, and Exchange Rates62 Questions
Exam 9: Forecasting Exchange Rates92 Questions
Exam 10: Measuring Exposure to Exchange Rate Fluctuations90 Questions
Exam 11: Managing Transaction Exposure92 Questions
Exam 12: Managing Economic Exposure and Translation Exposure63 Questions
Exam 13: Direct Foreign Investment62 Questions
Exam 14: Multinational Capital Budgeting63 Questions
Exam 15: International Corporate Governance and Control74 Questions
Exam 16: Country Risk Analysis57 Questions
Exam 17: Multinational Cost of Capital and Capital Structure71 Questions
Exam 18: Long-Term Debt Financing54 Questions
Exam 19: Financing International Trade73 Questions
Exam 20: Short-Term Financing55 Questions
Exam 21: International Cash Management49 Questions
Select questions type


Exhibit 20-1
Assume a U.S.-based MNC is borrowing Romanian leu (ROL) at an interest rate of 8% for one year. Also assume that the spot rate of the leu is $.00012 and the one-year forward rate of the leu is $.00010. The expected spot rate of the leu one-year from now is $.00011.
-Maston Corporation has forecasted the value of the Russian ruble as follows for the next year: 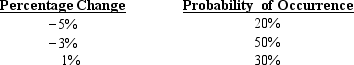 If the Russian interest rate is 30%, the expected cost of financing a one-year loan in rubles is:
 (Multiple Choice)
4.8/5  (71)
(71) Exhibit 20-2
To benefit from the low correlation between the Canadian dollar (C$) and the Japanese yen (¥), Luzar Corporation decides to borrow 50% of funds needed in Canadian dollars and the remainder in yen. The domestic financing rate for a one-year loan is 7%. The Canadian one-year interest rate is 6% and the Japanese one-year interest rate is 10%. Luzar has determined the following possible percentage changes in the two individual currencies as follows:
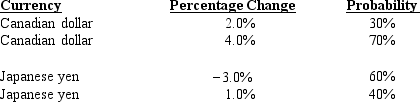 -Refer to Exhibit 20-2. What is the expected effective financing rate of the portfolio Luzar is contemplating (assume the two currencies move independently from one another)?
 (Multiple Choice)
4.9/5 (89)
(89) A U.S. firm plans to borrow Swiss francs today for a one-year period. The Swiss interest rate is 9%. It uses today's spot rate as a forecast for the franc's spot rate in one year. The U.S. one-year interest rate is 10%. The expected effective financing rate on Swiss francs is:
(Multiple Choice)
4.9/5 (78)
(78) MNCs can use short-term foreign financing to reduce their exposure to exchange rate fluctuations. For example, if an American-based MNC has ____ in euros, it could borrow ____, resulting in an offsetting effect.
(Multiple Choice)
4.8/5 (80)
(80) Assume that the Swiss franc has an annual interest rate of 8% and is expected to depreciate by 6% against the dollar. From a U.S. perspective, the effective financing rate from borrowing francs is:
(Multiple Choice)
4.8/5 (90)
(90) A firm without any exposure to foreign exchange rates would likely increase this exposure the most by:
(Multiple Choice)
4.8/5 (81)
(81) If interest rate parity exists, the attempt to finance with a foreign currency while covering the position to avoid exchange rate risk will result in an effective financing rate that is ____ the domestic interest rate.
(Multiple Choice)
4.9/5 (84)
(84) Exhibit 20-2
To benefit from the low correlation between the Canadian dollar (C$) and the Japanese yen (¥), Luzar Corporation decides to borrow 50% of funds needed in Canadian dollars and the remainder in yen. The domestic financing rate for a one-year loan is 7%. The Canadian one-year interest rate is 6% and the Japanese one-year interest rate is 10%. Luzar has determined the following possible percentage changes in the two individual currencies as follows:
-Refer to Exhibit 20-2. What is the probability that the financing rate of the two-currency portfolio is less than the domestic financing rate?
-Refer to Exhibit 20-2. What is the probability that the financing rate of the two-currency portfolio is less than the domestic financing rate? (Multiple Choice)
4.8/5 (84)
(84) Assume that the U.S. interest rate is 11% while the interest rate on the euro is 7%. If euros are borrowed by a U.S. firm, they would have to ____ against the dollar by ____ in order to have the same effective financing rate from borrowing dollars.
(Multiple Choice)
4.8/5 (74)
(74) Assume the U.S. one-year interest rate is 8%, and the British one-year interest rate is 6%. The one-year forward rate of the pound is $1.97. The spot rate of the pound at the beginning of the year is $1.95. By the end of the year, the pound's spot rate is $2.05. Based on the information, what is the effective financing rate for a U.S. firm that takes out a one-year, uncovered British loan?
(Multiple Choice)
4.8/5 (80)
(80) Exhibit 20-3
Cameron Corporation would like to simultaneously borrow Japanese yen (¥) and Sudanese dinar (SDD) for a six-month period. Cameron would like to determine the expected financing rate and the variance of a portfolio consisting of 30% yen and 70% dinar. Cameron has gathered the following information:
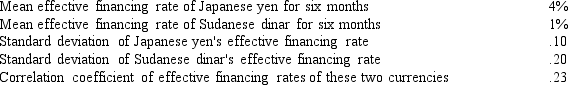 -Refer to Exhibit 20-3. What is the expected standard deviation of the portfolio contemplated by Cameron?
 (Multiple Choice)
4.9/5 (100)
(100) Exhibit 20-3
Cameron Corporation would like to simultaneously borrow Japanese yen (¥) and Sudanese dinar (SDD) for a six-month period. Cameron would like to determine the expected financing rate and the variance of a portfolio consisting of 30% yen and 70% dinar. Cameron has gathered the following information:
-Refer to Exhibit 20-3. What is the expected financing rate of the portfolio contemplated by Cameron Corporation?
-Refer to Exhibit 20-3. What is the expected financing rate of the portfolio contemplated by Cameron Corporation? (Multiple Choice)
4.9/5 (78)
(78) A firm forecasts the euro's value as follows for the next year: 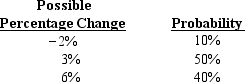 The annual interest rate on the euro is 7%. The expected value of the effective financing rate from a U.S. firm's perspective is about:
 (Multiple Choice)
4.7/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)