



 Chat with AI
Exam 9: Reporting and Interpreting Liabilities

Exam 1: Financial Statements and Business Decisions130 Questions
Exam 2: Investing and Financing Decisions and the Accounting System139 Questions
Exam 3: Operating Decisions and the Accounting System128 Questions
Exam 4: Adjustments, Financial Statements, and the Quality of Earnings138 Questions
Exam 5: Communicating and Interpreting Accounting Information119 Questions
Exam 6: Reporting and Interpreting Sales Revenue, Receivables, and Cash130 Questions
Exam 7: Reporting and Interpreting Cost of Goods Sold and Inventory137 Questions
Exam 8: Reporting and Interpreting Property, Plant, and Equipment; Intangibles; and Natural Resources131 Questions
Exam 9: Reporting and Interpreting Liabilities129 Questions
Exam 10: Reporting and Interpreting Bond Securities128 Questions
Exam 11: Reporting and Interpreting Stockholders Equity133 Questions
Exam 12: Statement of Cash Flows121 Questions
Exam 13: Analyzing Financial Statements125 Questions
Exam 14: PPA: Reporting and Interpreting Investments in Other Corporations115 Questions
Select questions type


Miranda Company borrowed $100,000 cash on September 1, 2016, and signed a one-year 6%, interest-bearing note payable. Assume no adjusting entries have been made during the year. Which of the following would be the required adjusting entry at the end of the December 31, 2016 accounting period?
(Multiple Choice)
4.8/5  (78)
(78) The following data is available for Tommy's Toys for the years 2014 through 2017: 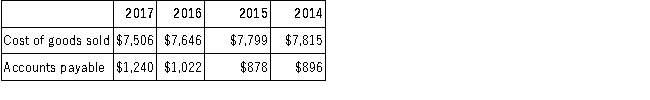 Required:
A.Calculate the accounts payable turnover ratio for the following years:
 B.Calculate the number of days it is taking Tommy's Toys to pay its vendors (assume a 365-day year):
 C.Explain whether Tommy's Toys is doing a better job over the years of paying its vendors in a timely manner.
Required:
A.Calculate the accounts payable turnover ratio for the following years:
B.Calculate the number of days it is taking Tommy's Toys to pay its vendors (assume a 365-day year):
C.Explain whether Tommy's Toys is doing a better job over the years of paying its vendors in a timely manner. (Essay)
4.8/5 (68)
(68) Mission Corp. borrowed $50,000 cash on April 1, 2016, and signed a one-year 12%, interest-bearing note payable. The interest and principal are both due on March 31, 2017. Assume that the appropriate adjusting entry was made on December 31, 2016 and that no adjusting entries have been made during 2017. What is the amount of interest expense to be recorded when the interest and principal are paid on March 31, 2017?
(Multiple Choice)
4.8/5 (81)
(81) The following data were provided by the detailed payroll records of Mountain Corporation for the last week of March 2017, which will not be paid until April 5, 2017: 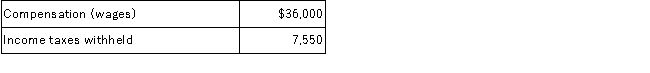 FICA taxes at a 7.65% rate (no employee had reached the maximum).
Required:
A.Prepare the March 31, 2017 journal entry to record the payroll and the related employee deductions.
B.Prepare the March 31, 2017 journal entry to record the employer's FICA payroll tax expense.
C.Calculate the total payroll-related liabilities at March 31, 2017 using the results of requirements (A) and (B).
FICA taxes at a 7.65% rate (no employee had reached the maximum).
Required:
A.Prepare the March 31, 2017 journal entry to record the payroll and the related employee deductions.
B.Prepare the March 31, 2017 journal entry to record the employer's FICA payroll tax expense.
C.Calculate the total payroll-related liabilities at March 31, 2017 using the results of requirements (A) and (B). (Essay)
4.9/5 (89)
(89) Rachel Corporation purchased a building by paying $90,000 cash on the purchase date, agreeing to pay $50,000 every year for the next nine years and one payment of $100,000 ten years from the purchase date. The first payment is due one year after the purchase date. Rachel's incremental borrowing rate is 10%. The building reported on the balance sheet as of the purchase date is closest to:
(Multiple Choice)
4.8/5 (91)
(91) Working capital increases when a company accrues sales revenue at year-end.
(True/False)
4.7/5 (75)
(75) Accounts payable and accrued liabilities are interchangeable account titles.
(True/False)
4.9/5 (65)
(65) Which of the following questions is incorrect with respect to determining the accounting for leases?
(Multiple Choice)
4.8/5 (72)
(72) Straight Industries purchased a large piece of equipment from Curvy Company on January 1, 2016. Straight Industries signed a note, agreeing to pay Curvy Company $400,000 for the equipment on December 31, 2018. The market rate of interest for similar notes was 8%. The present value of $400,000 discounted at 8% for three years was $317,520. On January 1, 2016, Straight Industries recorded the purchase with a debit to equipment for $317,520 and a credit to notes payable for $317,520. On Straight Industries' balance sheet for the year ended December 31, 2016, the book value of the liability for notes payable, including accrued interest would be closest to:
(Multiple Choice)
4.7/5 (66)
(66) Short Company purchased land by paying $10,000 cash on the purchase date and agreeing to pay $10,000 for each of the next ten years beginning one-year from the purchase date. Short's incremental borrowing rate is 10%. The land reported on the balance sheet is closest to:
(Multiple Choice)
4.8/5 (73)
(73) Melanie Corp. borrowed $100,000 cash on September 1, 2016, and signed a one-year 6%, interest-bearing note payable. The interest and principal are both due on August 31, 2017. Assume that the appropriate adjusting entry was made on December 31, 2016 and that no adjusting entries have been made during 2017. Which of the following would be the required journal entry to pay the note on August 31, 2017?
(Multiple Choice)
4.9/5 (83)
(83) On October 1, 2016, Donna Equipment signed a one-year, 8% interest-bearing note payable for $50,000. Assuming that Donna Equipment maintains its books on a calendar year basis, how much interest expense should be reported in the 2017 income statement?
(Multiple Choice)
4.9/5 (88)
(88) Husky Corporation is looking to purchase a building costing $500,000 by agreeing to make payments every three months for the next five years. The first payment is due three months after the purchase date. Husky's incremental borrowing rate is 12%. Each of the payments is closest to:
(Multiple Choice)
4.8/5 (76)
(76) Straight Industries purchased a large piece of equipment from Curvy Company on January 1, 2016. Straight Industries signed a note, agreeing to pay Curvy Company $400,000 for the equipment on December 31, 2018. The market rate of interest for similar notes was 8%. The present value of $400,000 discounted at 8% for three years was $317,520. On January 1, 2016, Straight Industries recorded the purchase with a debit to equipment for $317,520 and a credit to notes payable for $317,520. How much is the 2017 interest expense, assuming that the December 31, 2016 adjusting entry was made?
(Multiple Choice)
4.7/5 (82)
(82) The accrual of interest results in an increase liabilities and a decrease in cash.
(True/False)
4.7/5 (84)
(84) Grant Corporation is looking to purchase a building costing $900,000 by paying $300,000 cash on the purchase date, and agreeing to make payments every three months for the next five years. The first payment is due three months after the purchase date. Grant's incremental borrowing rate is 8%. Each of the payments is closest to:
(Multiple Choice)
4.9/5 (83)
(83) Which of the following would not be a result of the adjusting entry to record accrued interest on a note payable?
(Multiple Choice)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)