



 Chat with AI
Exam 9: Materiality and Risk

Exam 1: The Demand for Audit and Other Assurance Services47 Questions
Exam 2: The CPA Profession67 Questions
Exam 3: Audit Reports139 Questions
Exam 4: Professional Ethics114 Questions
Exam 5: Legal Liability113 Questions
Exam 6: The CPA Profession114 Questions
Exam 7: Audit Evidence94 Questions
Exam 8: Audit Planning and Analytical Procedures95 Questions
Exam 9: Materiality and Risk102 Questions
Exam 10: Section 404 Audits of Internal Control and Control Risk116 Questions
Exam 11: Fraud Auditing83 Questions
Exam 12: The Impact of Information Technology on the Audit Process106 Questions
Exam 13: Overall Audit Plan and Audit Program94 Questions
Exam 14: Audit of the Sales and Collection Cycle: Tests of Controls and Substantive Tests of Transactions108 Questions
Exam 15: Audit Sampling for Tests of Controls and Substantive Tests of Transactions117 Questions
Exam 16: Completing the Tests in the Sales and Collection Cycle: Accounts Receivable96 Questions
Exam 17: Audit Sampling for Tests of Details and Balances114 Questions
Exam 18: Audit of the Acquisition and Payment Cycle: Tests of Controls and Substantive Tests of Transactions, and Accounts Payable114 Questions
Exam 19: Completing the Tests in the Acquisition and Payment Cycle: Verification of Selected Accounts101 Questions
Exam 20: Audit of the Payroll and Personnel Cycle113 Questions
Exam 21: Audit of the Inventory and Warehousing Cycle115 Questions
Exam 22: Audit of the Capital Acquisition and Repayment Cycle91 Questions
Exam 23: Audit of Cash Balances92 Questions
Exam 24: Completing the Audit116 Questions
Exam 25: Other Assurance Services100 Questions
Exam 26: Internal and Governmental Financial Auditing and Operational Auditing73 Questions
Select questions type


The auditor's preliminary judgment about materiality is the maximum amount by which the auditor believes the financial statements could be misstated and still not affect the decisions of reasonable users.
(True/False)
4.8/5  (82)
(82) As the acceptable level of detection risk increases, an auditor may change the:
(Multiple Choice)
4.9/5 (83)
(83) If an auditor assigns a tolerable misstatement of $1,000 to accounts payable, he or she would need to obtain more audit evidence for that account than if $100,000 had been assigned.
(True/False)
4.8/5 (85)
(85) The measurement of the auditor's assessment of the likelihood that there are material misstatements due to error or fraud in a segment before considering the effectiveness of internal controls is defined as:
(Multiple Choice)
4.9/5 (97)
(97) The risk of material misstatement differs from detection risk in that it:
(Multiple Choice)
4.9/5 (79)
(79) Material misstatement is the magnitude of misstatement that makes a reasonable person either change their mind or be influenced by the misstatement. Audit standards require the auditor to consider the combined amount of misstatement early in the audit. This is known as preliminary materiality judgment. List and discuss the three main factors that affect an auditor's preliminary judgment about materiality.
(Essay)
4.9/5 (78)
(78) Certain types of misstatements are likely to be more important than other types to users, even if the dollar amounts are the same. Which of the following demonstrates this?
(Multiple Choice)
4.8/5 (81)
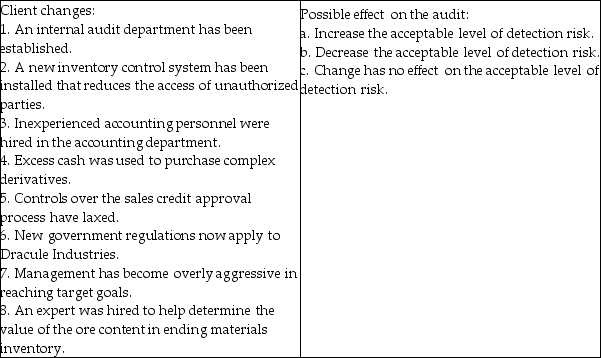
(81) Dracule Industries is a privately owned business that sells medical product and devices to hospitals, clinics and the public. Certain changes have occurred in Dracule Industries during the year undergoing the audit. Harker needs to evaluate the effect these changes have on audit risk. Audit risk at the financial statement level is influenced by the risk of material misstatement; which include factors related to management, the industry and the entity or a combination thereof. For each of the following changes that have occurred during the year under audit identify the appropriate audit response for the list of responses. Each response can be used once, more than once or not at all.
(Short Answer)
4.8/5 (76)
(76) If an auditor believes the client will have financial difficulties after the audit report is issued, and external users will be relying heavily on the financial statements, the auditor will probably set acceptable audit risk as low.
(True/False)
4.9/5 (79)
(79) Acceptable audit risk and the amount of substantive evidence required are inversely related.
(True/False)
4.9/5 (86)
(86) Due to qualitative factors, certain types of misstatements are likely to be more important to users than others, even if the dollar amounts are the same. Identify two qualitative factors that might significantly affect an auditor's materiality judgment, and give an example of each.
(Essay)
4.8/5 (79)
(79) When allocating materiality, most practitioners choose to allocate to:
(Multiple Choice)
4.9/5 (86)
(86) Amounts involving fraud are usually considered ________ important than unintentional errors of equal dollar amounts.
(Multiple Choice)
5.0/5 (93)
(93) Auditors frequently refer to the terms audit assurance, overall assurance, and level of assurance to refer to ________.
(Multiple Choice)
4.9/5 (79)
(79) To what extent do auditors typically rely on internal controls of their public company clients?
(Multiple Choice)
4.8/5 (77)
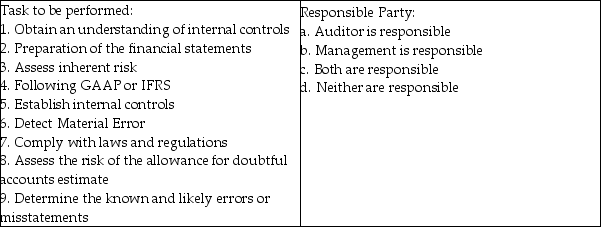
(77) Harker, CPA is in the audit planning phase of Dracule Industries. An understanding needs to be established regarding the responsibilities of Harker and Dracule's Management. For each of the task items listed below indicate the responsible party from the list of choices given. Each choice may be used once, more than once or not at all.
(Essay)
5.0/5 (85)
(85) The most important element of the audit risk model is control risk.
(True/False)
4.9/5 (87)
(87) Auditors have difficulty applying the concept of materiality in practice because they often do not know who the users of the financial statements are or what decisions will be made.
(True/False)
4.7/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)