



 Chat with AI
Exam 9: Materiality and Risk

Exam 1: The Demand for Audit and Other Assurance Services47 Questions
Exam 2: The CPA Profession67 Questions
Exam 3: Audit Reports139 Questions
Exam 4: Professional Ethics114 Questions
Exam 5: Legal Liability113 Questions
Exam 6: The CPA Profession114 Questions
Exam 7: Audit Evidence94 Questions
Exam 8: Audit Planning and Analytical Procedures95 Questions
Exam 9: Materiality and Risk102 Questions
Exam 10: Section 404 Audits of Internal Control and Control Risk116 Questions
Exam 11: Fraud Auditing83 Questions
Exam 12: The Impact of Information Technology on the Audit Process106 Questions
Exam 13: Overall Audit Plan and Audit Program94 Questions
Exam 14: Audit of the Sales and Collection Cycle: Tests of Controls and Substantive Tests of Transactions108 Questions
Exam 15: Audit Sampling for Tests of Controls and Substantive Tests of Transactions117 Questions
Exam 16: Completing the Tests in the Sales and Collection Cycle: Accounts Receivable96 Questions
Exam 17: Audit Sampling for Tests of Details and Balances114 Questions
Exam 18: Audit of the Acquisition and Payment Cycle: Tests of Controls and Substantive Tests of Transactions, and Accounts Payable114 Questions
Exam 19: Completing the Tests in the Acquisition and Payment Cycle: Verification of Selected Accounts101 Questions
Exam 20: Audit of the Payroll and Personnel Cycle113 Questions
Exam 21: Audit of the Inventory and Warehousing Cycle115 Questions
Exam 22: Audit of the Capital Acquisition and Repayment Cycle91 Questions
Exam 23: Audit of Cash Balances92 Questions
Exam 24: Completing the Audit116 Questions
Exam 25: Other Assurance Services100 Questions
Exam 26: Internal and Governmental Financial Auditing and Operational Auditing73 Questions
Select questions type


Tolerable misstatement does not affect audit risk, inherent risk, control risk, or planned detection risk yet the combination of the tolerable misstatement and the four risks will determine the amount of planned audit evidence.
(True/False)
4.9/5  (74)
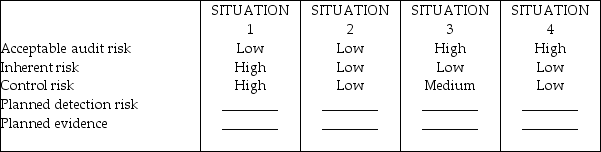
(74) In practice, auditors rarely assign numerical probabilities to inherent risk, control risk, or acceptable audit risk. It is more common to assess these risks as high, medium, or low. For each of the four situations below, fill in the blanks for planned detection risk and the amount of evidence you would plan to gather ("planned evidence") using the terms high, medium, or low.
(Essay)
4.9/5 (70)
(70) Preliminary judgments about materiality are often changed during the course of the engagement.
(True/False)
4.8/5 (77)
(77) Insert risk and control risk are normally assessed for the each segment but sets audit risk at the financial statement level.
(True/False)
4.8/5 (84)
(84) The risk that audit evidence for a segment will fail to detect misstatements exceeding tolerable misstatement is:
(Multiple Choice)
4.8/5 (79)
(79) In a financial statement audit, inherent risk is evaluated to help an auditor asses which of the following?
(Multiple Choice)
4.9/5 (81)
(81) Which of the following statements is true concerning the allocation of preliminary materiality?
(Multiple Choice)
4.9/5 (77)
(77) For a private company client, auditors are required to test any internal controls they believe have not been operating effectively during the period under audit.
(True/False)
4.8/5 (79)
(79) If it is probable that the judgment of a reasonable person will be changed or influenced by the omission or misstatement of information, then that information is, by definition of FASB Statement No. 2:
(Multiple Choice)
4.9/5 (82)
(82) Auditors are ________ to document the known and likely misstatements in the financial statements under audit.
(Multiple Choice)
4.8/5 (87)
(87) Based on audit evidence gathered and evaluated, an auditor decides to increase the assessed level of control risk from that originally planned. To achieve an overall audit risk level that is substantially the same as the planned audit risk level, the auditor would:
(Multiple Choice)
4.8/5 (78)
(78) Net assets are the most often used base for deciding materiality.
(True/False)
4.8/5 (80)
(80) ________ misstatements are those where the auditor can determine the amount of the misstatement in the account.
(Multiple Choice)
5.0/5 (67)
(67) The risk of material misstatement is a combination of two client controlled factors: inherent risk and control risk. What is inherent risk, why is it important and give examples of inherent risk factors.
(Essay)
4.8/5 (88)
(88) Qualitative factors can affect an auditor's assessment of materiality. Which of the following qualitative factors could influence the assessment of materiality?
I. Misstatements that are otherwise immaterial may be material if they affect earnings trends.
II. Minor misstatements resulting from the consequences of contractual obligations.
(Multiple Choice)
4.9/5 (71)
(71) When management has an adequate level of integrity for the auditor to accept the engagement but cannot be regarded as completely honest in all dealings, auditors normally:
(Multiple Choice)
4.9/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)