



 Chat with AI
Exam 23: Perfect Competition

Exam 1: The Nature of Economics348 Questions
Exam 2: Scarcity and the World of Trade-Offs411 Questions
Exam 3: Demand and Supply451 Questions
Exam 4: Extensions of Demand and Supply Analysis401 Questions
Exam 5: Public Spending and Public Choice362 Questions
Exam 6: Funding the Public Sector201 Questions
Exam 7: The Macroeconomy: Unemployment, Inflation, and Deflation413 Questions
Exam 8: Measuring the Economys Performance416 Questions
Exam 9: Global Economic Growth and Development290 Questions
Exam 10: Real GDP and the Price Level in the Long Run298 Questions
Exam 11: Classical and Keynesian Macro Analyses368 Questions
Exam 12: Consumption, Real GDP, and the Multiplier452 Questions
Exam 13: Fiscal Policy274 Questions
Exam 14: Deficit Spending and the Public Debt146 Questions
Exam 15: Money, Banking, and Central Banking516 Questions
Exam 16: Domestic and International Dimensions of Monetary Policy357 Questions
Exam 17: Stabilization in an Integrated World Economy321 Questions
Exam 18: Policies and Prospects for Global Economic Growth228 Questions
Exam 19: Demand and Supply Elasticity412 Questions
Exam 20: Consumer Choice459 Questions
Exam 21: Rents, Profits, and the Financial Environment of Business445 Questions
Exam 22: The Firm: Cost and Output Determination391 Questions
Exam 23: Perfect Competition432 Questions
Exam 24: Monopoly386 Questions
Exam 25: Monopolistic Competition307 Questions
Exam 26: Oligopoly and Strategic Behavior308 Questions
Exam 27: Regulation and Antitrust Policy in a Globalized Economy310 Questions
Exam 28: The Labor Market: Demand, Supply and Outsourcing376 Questions
Exam 29: Unions and Labor Market Monopoly Power319 Questions
Exam 30: Income, Poverty, and Health Care304 Questions
Exam 31: Environmental Economics299 Questions
Exam 32: Comparative Advantage and the Open Economy282 Questions
Exam 33: Exchange Rates and the Balance of Payments285 Questions
Select questions type


In the short run, the price at which a firm's total revenues equal its total costs is
(Multiple Choice)
4.9/5  (78)
(78) The demand curve faced by a perfectly competitive industry
(Multiple Choice)
4.9/5 (90)
(90) Assuming fixed factor prices, the short-run industry supply curve for a perfectly competitive industry is equal to the sum of the
(Multiple Choice)
4.7/5 (72)
(72)  -In the above figure, what is the price the firm receives if the output is 8?
 (Multiple Choice)
4.7/5 (78)
(78) In the long run when a perfectly competitive firm experiences negative economic profits
(Multiple Choice)
4.9/5 (80)
(80)  -In the above figure, the firm will shut down if price falls below
 (Multiple Choice)
4.8/5 (78)
(78) The demand curve for the product of a perfectly competitive firm is
(Multiple Choice)
4.7/5 (74)
(74) If a perfectly competitive industry is in long-run equilibrium, then
(Multiple Choice)
4.7/5 (87)
(87) A firm will continue to produce in the short run even though economic profits are negative as long as
(Multiple Choice)
4.8/5 (91)
(91) The rising portion of a perfectly competitive firm's marginal cost curve, above the intersection with AVC, is its
(Multiple Choice)
4.9/5 (71)
(71) Why is the demand curve horizontal for a perfectly competitive firm?
(Essay)
4.8/5 (83)
(83) In principle, how do we determine a perfectly competitive firm's profit-maximizing output and maximum profits given information about the market clearing price, and about the marginal cost and average total cost curves of the firm? Explain in words.
(Essay)
4.8/5 (80)
(80) Which of the following is closest to a perfectly competitive market?
(Multiple Choice)
4.8/5 (78)
(78)  -Refer to the above figure. The figure represents the market demand and supply curves for widgets. What statement can be made about the demand curve for an individual firm in this market?
 (Multiple Choice)
4.8/5 (88)
(88) Why would it be economically inefficient for a firm to charge the price of a good greater than its marginal cost?
(Essay)
4.9/5 (74)
(74) "In the long run, a perfectly competitive firm's average total cost is always below the market clearing price." Agree or disagree? Why?
(Essay)
4.8/5 (67)
(67) Which of the following could generate economic profits for perfectly competitive firms in the short run, if they initially earn zero economic profits?
(Multiple Choice)
4.9/5 (72)
(72) A firm in a perfectly competitive industry faces the following cost and revenue conditions: ATC = $6; AVC = $3; MR = MC = $5. The firm is
(Multiple Choice)
4.9/5 (78)
(78) 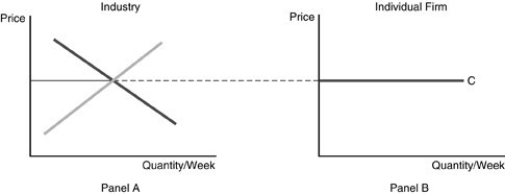 -Refer to the above figure. Line C in Panel B does NOT represent
 (Multiple Choice)
4.9/5 (74)
(74) 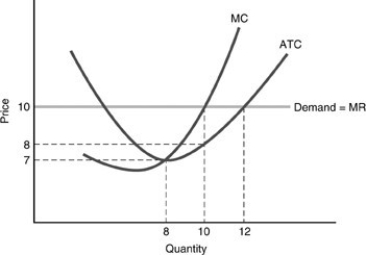 -If a firm is earning short-run economic profits shown in the above figure, in the long run
 (Multiple Choice)
4.8/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)