



 Chat with AI
Exam 7: Consolidated Financial Statements - Ownership Patterns and Income

Exam 1: The Equity Method of Accounting for Investments119 Questions
Exam 2: Consolidation of Financial Information115 Questions
Exam 3: Consolidations-Subsequent to the Date of Acquisition120 Questions
Exam 4: Consolidated Financial Statements and Outside Ownership117 Questions
Exam 5: Consolidated Financial Statements - Intra-Entity Asset Transactions127 Questions
Exam 6: Variable Interest Entities, Intra-Entity Debt, Consolidated Cash Flo115 Questions
Exam 7: Consolidated Financial Statements - Ownership Patterns and Income118 Questions
Exam 8: Segment and Interim Reporting113 Questions
Exam 9: Foreign Currency Transactions and Hedging Foreign Exchange Risk93 Questions
Exam 10: Translation of Foreign Currency Financial Statements97 Questions
Exam 11: Worldwide Accounting Diversity and International Standards60 Questions
Exam 12: Financial Reporting and the Securities and Exchange Commission77 Questions
Exam 13: Accounting for Legal Reorganizations and Liquidations82 Questions
Exam 14: Partnerships: Formation and Operations88 Questions
Exam 15: Partnerships: Termination and Liquidation70 Questions
Exam 16: Accounting for State and Local Governments78 Questions
Exam 17: Accounting for State and Local Governments46 Questions
Exam 18: Accounting and Reporting for Private Not-For-Profit Organizations62 Questions
Exam 19: Accounting for Estates and Trusts80 Questions
Select questions type


Kurton Inc. owned 90% of Luvyn Corp.'s voting common stock. The consideration paid exceeded book value by $110,000. Of this amount, one half is attributable to a patent and is to be amortized over 5 years. Luvyn held 20% of Kurton's voting common stock which cost $28,000 more than fair value.
During the current year, Kurton reported operating income of $224,000 and dividend income from Luvyn of $37,800. At the same time, Luvyn reported operating income of $70,000 and dividend income from Kurton of $19,600.
-Required:
Prepare a schedule to show consolidated net income.
(Essay)
4.9/5  (83)
(83) On January 1, 2010, Jones Company bought 15% of Whitton Company. Jones paid $150,000 for these shares, an amount that exactly equaled the proportionate book value of Whitton. On January 1, 2011, Whitton acquired 80% ownership of Jones. The following data are available concerning Whitton's acquisition of Jones:
Consideration transferred for 80% interest, January 1, 2011: $800,000
Jones' reported book value, January 1, 2011: 900,000
Excess fair value over book value (assigned to trademarks) is amortized over 20 years.
The initial value method is used by both companies.
The following information is available regarding Jones and Whitton: 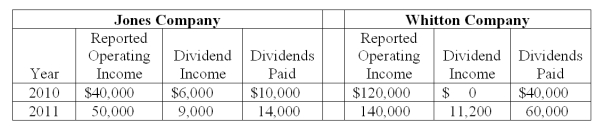 -Compute the amount allocated to trademarks recognized in the January 1, 2011 consolidated balance sheet.
 (Multiple Choice)
4.8/5 (87)
(87) River Co. owned 80% of Boat Inc. The two companies filed a consolidated income tax return and River used the initial value method to account for the investment. The following information was available from the two companies' financial statements: 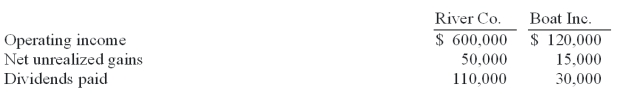 Operating income included net unrealized gains, which are associated with transfers of inventories between the two companies, but it did not include dividends received from a subsidiary. The income tax rate was 30%.
-What was the noncontrolling interest in Boat Inc.'s net income, assuming that the separate return method was used?
Operating income included net unrealized gains, which are associated with transfers of inventories between the two companies, but it did not include dividends received from a subsidiary. The income tax rate was 30%.
-What was the noncontrolling interest in Boat Inc.'s net income, assuming that the separate return method was used? (Multiple Choice)
4.8/5 (77)
(77) What amount should have been reported for consolidated net income?
(Multiple Choice)
4.9/5 (58)
(58) River Co. owned 80% of Boat Inc. The two companies filed a consolidated income tax return and River used the initial value method to account for the investment. The following information was available from the two companies' financial statements: Operating income included net unrealized gains, which are associated with transfers of inventories between the two companies, but it did not include dividends received from a subsidiary. The income tax rate was 30%.
-What is the amount of taxable income reported on the consolidated income tax return?
Operating income included net unrealized gains, which are associated with transfers of inventories between the two companies, but it did not include dividends received from a subsidiary. The income tax rate was 30%.
-What is the amount of taxable income reported on the consolidated income tax return? (Multiple Choice)
4.8/5 (88)
(88) White Company owns 60% of Cody Company. Separate tax returns are required. For 2010, White's operating income (excluding taxes and any income from Cody) was $300,000 while Cody reported a pretax income of $125,000. During the period, Cody paid a total of $25,000 in cash dividends; $15,000 (60%) to White and $10,000 to the noncontrolling interest. White paid dividends of $180,000. The income tax rate for both companies is 30%.
-Compute Cody's income tax expense for 2011.
(Multiple Choice)
4.7/5 (68)
(68) According to International Financial Reporting Standards: In the consolidation process for subsidiaries that are indirectly controlled:
(Multiple Choice)
4.7/5 (69)
(69) Dean, Inc. owns 90 percent of Ralph, Inc. During the current year, Dean sold merchandise costing $80,000 to Ralph for $100,000. At the end of the year, 30 percent of this merchandise was still on hand. The tax rate is 30 percent.
-Assuming that separate income tax returns are being filed, what deferred income tax asset is created?
(Multiple Choice)
4.9/5 (89)
(89) Patton's operating income excludes income from the investment in Stevens, but includes $150,000 of unrealized gains on intra-entity transfers of inventory. Patton uses the initial value method to account for the investment in Stevens.
-Assume Patton owns 90 percent of the voting stock of Stevens and they each file separate income tax returns. What amount of total income tax would be paid?
(Essay)
4.8/5 (81)
(81) Why might a consolidated group file separate income tax returns?
(Multiple Choice)
4.9/5 (84)
(84) White Company owns 60% of Cody Company. Separate tax returns are required. For 2010, White's operating income (excluding taxes and any income from Cody) was $300,000 while Cody reported a pretax income of $125,000. During the period, Cody paid a total of $25,000 in cash dividends; $15,000 (60%) to White and $10,000 to the noncontrolling interest. White paid dividends of $180,000. The income tax rate for both companies is 30%.
-Compute the income tax payable by White for 2011.
(Multiple Choice)
4.8/5 (77)
(77) Alpha Corporation owns 100 percent of Beta Company, and Beta owns 80 percent of Gamma, Inc., all of which are domestic corporations. Information for the three companies for the year ending December 31, 2011 follows: 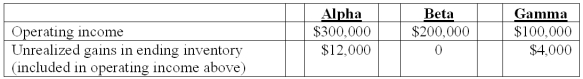 -What is Alpha's accrual-based income for 2011?
 (Multiple Choice)
4.7/5 (81)
(81) Beagle Co. owned 80% of Maroon Corp. Maroon owned 90% of Eckston Inc. Operating income totals for 2011 are shown below; these figures contained no investment income. Amortization expense was not required by any of these acquisitions. Included in Eckston's operating income was a $56,000 unrealized gain on intra-entity transfers to Maroon. 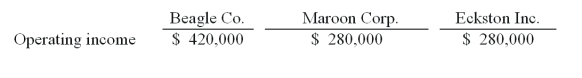 -The accrual-based income of Maroon Corp. is calculated to be
 (Multiple Choice)
4.9/5 (77)
(77) White Company owns 60% of Cody Company. Separate tax returns are required. For 2010, White's operating income (excluding taxes and any income from Cody) was $300,000 while Cody reported a pretax income of $125,000. During the period, Cody paid a total of $25,000 in cash dividends; $15,000 (60%) to White and $10,000 to the noncontrolling interest. White paid dividends of $180,000. The income tax rate for both companies is 30%.
-Compute Cody's undistributed earnings for 2011.
(Multiple Choice)
5.0/5 (79)
(79) Beagle Co. owned 80% of Maroon Corp. Maroon owned 90% of Eckston Inc. Operating income totals for 2011 are shown below; these figures contained no investment income. Amortization expense was not required by any of these acquisitions. Included in Eckston's operating income was a $56,000 unrealized gain on intra-entity transfers to Maroon.
-The accrual-based income of Eckston Inc. is calculated to be
-The accrual-based income of Eckston Inc. is calculated to be (Multiple Choice)
5.0/5 (80)
(80) What ownership pattern is referred to as mutual ownership? Describe briefly or illustrate with a diagram.
(Essay)
4.8/5 (65)
(65) What are the benefits or advantages of filing a consolidated income tax return?
(Essay)
4.9/5 (71)
(71) Dice Inc. owns 40% of the outstanding shares of Spalding Corp., an investment accounted for by the equity method. During 2011, Dice earned operating income (not including income from its investment in Spalding) of $370,000. For this same period, Spalding reported net income of $160,000 and paid cash dividends of $60,000. Dice has an effective income tax rate of 35% and anticipates holding its investment in Spalding for an indefinite period.
Required:
(A) What income tax expense journal entry would Dice Inc. record at the end of 2011?
(B) If Dice expects to sell its interest in Spalding in the near future, how does that decision change the 2011 income tax expense journal entry?
(Essay)
4.9/5 (62)
(62) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)