



 Chat with AI
Exam 5: Analyzing Investing Activities: Intercorporate Investments

Exam 1: Overview of Financial Statement Analysis79 Questions
Exam 2: Financial Reporting and Analysis74 Questions
Exam 3: Analyzing Financing Activities82 Questions
Exam 4: Analyzing Investing Activities67 Questions
Exam 5: Analyzing Investing Activities: Intercorporate Investments101 Questions
Exam 6: Analyzing Operating Activities83 Questions
Exam 7: Cash Flow Analysis80 Questions
Exam 8: Return on Invested Capital and Profitability Analysis76 Questions
Exam 9: Prospective Analysis65 Questions
Exam 10: Credit Analysis104 Questions
Exam 11: Equity Analysis and Valuation73 Questions
Select questions type


You are analyzing the financial statements of ABC Corp. at the end of fiscal 2006. You notice that during the year, they made a major acquisition. Nowhere in the annual report does it state whether ABC used purchase or pooling-of-interests accounting for this acquisition. It made no other acquisitions during the year, and there were no disposals of any lines of business.
How would you determine whether purchase accounting or pooling-of-interests accounting had been used. Give three ways. Explain fully.
(Essay)
4.8/5  (85)
(85) SFAS 159 requires that once fair value has been adopted for a class of securities, the company can reverse the option after one year.
(True/False)
4.7/5 (92)
(92) Which of the following is allowed to be reported on fair value basis under SFAS 159?
(Multiple Choice)
4.8/5 (65)
(65) Constant Corp. bought Steady Company on June 30, 2005 in a pooling-of-interests transaction. Both companies are in stagnant markets. Steady had total assets of $50,000 and total liabilities of $30,000 with fair market values of $60,000 and $30,000, respectively. Constant issued 1,000 shares, valued at $45 per share. Both companies operate in tax-free havens and take a half-year's depreciation in the year acquired using ten-year lives. Monthly operating results are as follows:
Sales \ 3,000 \ 1,000 Expenses 2,000 800 Net income \ 1,000 \ 200 Assume revenue and earnings remain same for the next year. Company is following SFAS 142.
-If accounted for as a purchase, 2005 consolidated earnings are reported as
(Multiple Choice)
4.7/5 (81)
(81) Compared to the equity method, the cost method of accounting for an investment in a profitable company results in:
(Multiple Choice)
4.7/5 (91)
(91) SFAS 142 requires that goodwill be tested using a two-step process as often as financial statements are presented.
(True/False)
4.8/5 (77)
(77) Parent Company Inc. successfully bids for Child Company Inc. in year X1. Parent Company Inc. has purchased all of Child's shares outstanding for $8,500. Following are excerpts from both companies' financial statements for year X1, prior to the acquisition.
Parent Company Inc. Child Company Inc. Total Assets \ 37,234 \ 5,379 Total Liabilities \ 23,467 \ 3,764 Total Shareholder's Equity \ 13,767 \ 1,615 Total Liabilities and Shareholders' Equity \ 37,234 \ 5,379 Also assume the following information: the acquisition was accounted for using the purchase method. $1,500 of the excess price relates to depreciable assets, and those assets have an additional useful life of 10 years at the time of the acquisition. Parent Company Inc. uses the straight line depreciation method and has a 34% tax rate. The combined net income for both companies for year X2 (excluding any expenses that need to be recorded as a result of the purchase method accounting for the merger) was $1,560.
-What would be the net income in the consolidated income statement for year X2?
(Multiple Choice)
4.8/5 (68)
(68) Under U.S. GAAP, the method used to convert financial statements of foreign subsidiaries in countries experiencing hyperinflation is:
(Multiple Choice)
4.9/5 (81)
(81) Below are the financial statements for Arden Cosmetics and Pia's Perfume. Arden Cosmetics Balance Sheet as of 12/31/06 (in millions) Pia's Perfume Balance Sheet as of (in millions) Assets Current Assets \ 9,000 \ 2,000 Property, Plant and Equipment 10,000 400 Total Assets \ 19,000 \ 2,400 Liabilities and Stockholders' Equity Current Liabilities \ 7,000 \ 600 Long-term Debt 2,000 600 Deferred Taxes 2,000 Stockholders' Equity 8,000 \ 1,200 \ 19,000 \2 ,400
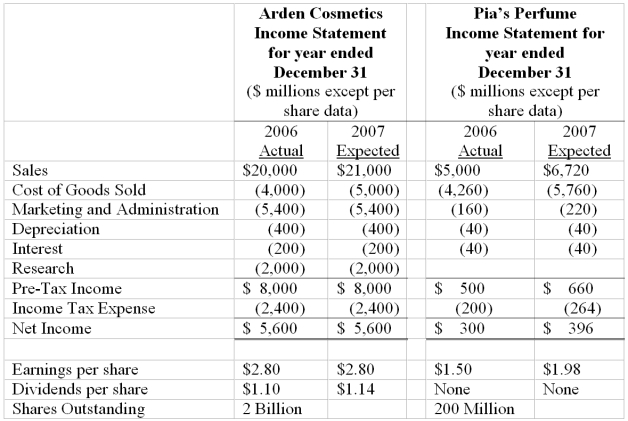 Arden is considering two alternative approaches to making the acquisition of Pia: share-for-share exchange or cash purchase. Assume the following: - The billion dollar cost of purchasing Pia at per share would be financed by debt with a 10 percent interest rate.
- All assets and liabilities of Pia have fair market values equal to their balance sheet values except property, plant and equipment, which have a fair market value of billion. Pia depreciates its property, plant, and equipment over 10 years using the straight-line method.
- The marginal tax rate is 40 percent.
Part a.
Assume Arden uses a share-for-share exchange to acquire Pia and accounts for the transaction as a pooling-of-interests:
i. Prepare a pro forma December 31, 2006 balance sheet for Arden reflecting the acquisition and calculate the resulting book value per share.
ii. Prepare a pro forma estimated 2007 income statement for Arden reflecting the acquisition, and calculate the resulting earnings per share.
Part b.
Assume Arden pays $30 cash per share to acquire 100 percent of the common stock of Pia and accounts for the transaction as a purchase.
i. Prepare a pro forma December 31, 2006 balance sheet for Arden reflecting the acquisition and calculate the resulting book value per share.
ii. Prepare a pro forma estimated 2007 income statement for Arden reflecting the acquisition, and calculate the resulting earnings per share.
Arden is considering two alternative approaches to making the acquisition of Pia: share-for-share exchange or cash purchase. Assume the following: - The billion dollar cost of purchasing Pia at per share would be financed by debt with a 10 percent interest rate.
- All assets and liabilities of Pia have fair market values equal to their balance sheet values except property, plant and equipment, which have a fair market value of billion. Pia depreciates its property, plant, and equipment over 10 years using the straight-line method.
- The marginal tax rate is 40 percent.
Part a.
Assume Arden uses a share-for-share exchange to acquire Pia and accounts for the transaction as a pooling-of-interests:
i. Prepare a pro forma December 31, 2006 balance sheet for Arden reflecting the acquisition and calculate the resulting book value per share.
ii. Prepare a pro forma estimated 2007 income statement for Arden reflecting the acquisition, and calculate the resulting earnings per share.
Part b.
Assume Arden pays $30 cash per share to acquire 100 percent of the common stock of Pia and accounts for the transaction as a purchase.
i. Prepare a pro forma December 31, 2006 balance sheet for Arden reflecting the acquisition and calculate the resulting book value per share.
ii. Prepare a pro forma estimated 2007 income statement for Arden reflecting the acquisition, and calculate the resulting earnings per share. (Essay)
4.9/5 (81)
(81) If the temporal method is used for foreign currency translation and the foreign subsidiary has an excess of monetary liabilities over monetary assets, an increase in the strength of the dollar will result in a translation loss.
(True/False)
4.8/5 (86)
(86) When accounting for an investment under the equity method, what situations may reduce the carrying value of the investment?
I. Investee experiences significant losses.
II. Investee distributes dividends in excess of earnings.
III. Investee sells additional shares for less than book value.
IV. Investee engages in a stock split.
(Multiple Choice)
4.9/5 (87)
(87) A U.S. company has a subsidiary located in Great Britain. Information for the subsidiary for the year ended December 31, 2006 is as follows:
British pound Gross profit margin 40\% Inventory 2,000 Exchange Rate Balance Sheet date 1 pound =\ 1.6 Average exchange rate 1 pound =\ 1.5 Historical rate 1 pound =\ 1.4
-After converting to U.S. dollars using the appropriate method, gross profit margin is 40%. What method is being used to record British subsidiaries financial statements?
(Multiple Choice)
4.9/5 (91)
(91) Constant Corp. bought Steady Company on June 30, 2005 in a pooling-of-interests transaction. Both companies are in stagnant markets. Steady had total assets of $50,000 and total liabilities of $30,000 with fair market values of $60,000 and $30,000, respectively. Constant issued 1,000 shares, valued at $45 per share. Both companies operate in tax-free havens and take a half-year's depreciation in the year acquired using ten-year lives. Monthly operating results are as follows:
Sales \ 3,000 \ 1,000 Expenses 2,000 800 Net income \ 1,000 \ 200 Assume revenue and earnings remain same for the next year. Company is following SFAS 142.
-If accounted for as a purchase, 2006 consolidated earnings are reported as
(Multiple Choice)
4.9/5 (85)
(85) Which exchange rates are used for foreign subsidiaries with different functional currencies? Using the following abbreviations, identify which of the below are correct methods for converting inventory.
Year-end rates: YE
Average rates: AR
Historical rates: HR Temporal Current Rate A) YE AR B) HR YE C) YE HR D) HR HR
(Multiple Choice)
4.8/5 (80)
(80) Investment securities should always be reported at lower-of-cost-or-market.
(True/False)
4.7/5 (87)
(87) The equity method of accounting for investments should be used when the company has a controlling interest in the investee.
(True/False)
4.8/5 (77)
(77) A U.S. company has a subsidiary located in Great Britain. Information for the subsidiary for the year ended December 31, 2006 is as follows:
British pound Gross profit margin 40\% Inventory 2,000 Exchange Rate Balance Sheet date 1 pound =\ 1.6 Average exchange rate 1 pound =\ 1.5 Historical rate 1 pound =\ 1.4
-If the British pound was determined to be the functional currency, what would inventory be in US dollars?
(Multiple Choice)
4.8/5 (69)
(69) One of the problems with pooling-of-interests accounting is that the true cost of an acquisition is not reflected in the balance sheet of the acquirer.
(True/False)
4.8/5 (69)
(69) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)