



 Chat with AI
Exam 7: Allocating Costs of Support Departments and Joint Products

Exam 1: Introduction to Cost Management157 Questions
Exam 2: Basic Cost Management Concepts201 Questions
Exam 3: Cost Behavior200 Questions
Exam 4: Activity-Based Costing201 Questions
Exam 5: Product and Service Costing: Job-Order System150 Questions
Exam 6: Process Costing188 Questions
Exam 7: Allocating Costs of Support Departments and Joint Products173 Questions
Exam 8: Budgeting for Planning and Control Key200 Questions
Exam 9: Standard Costing: a Functional-Based Control Approach123 Questions
Exam 10: Decentralization: Responsibility Accounting, Performance Evaluation, and Transfer Pricing139 Questions
Exam 11: Strategic Cost Management151 Questions
Exam 12: Activity-Based Management146 Questions
Exam 13: The Balanced Scorecard: Strategic-Based Control124 Questions
Exam 14: Quality and Environmental Cost Management202 Questions
Exam 15: Lean Accounting and Productivity Measurement172 Questions
Exam 16: Cost-Volume-Profit Analysis138 Questions
Exam 17: Activity Resource Usage Model and Tactical Decision Making128 Questions
Exam 18: Pricing and Profitability Analysis164 Questions
Exam 19: Capital Investment126 Questions
Exam 20: Inventory Management: Economic Order Quantity, Jit, and the Theory of Constraints127 Questions
Select questions type


__________ are mutually beneficial costs to joint product costing.
(Short Answer)
4.9/5  (73)
(73) Abound Company has two support departments (S1 and S2) and two producing departments (X and Y). Department S1 serves Departments S2, X, and Y in the following percentages, respectively: 10%, 35%, 55%. Department S2 serves Departments S1, X, and Y in the following percentages, respectively: 6%, 50%, and 44%. Direct department costs for S1, S2, X, and Y are $15,000, $8,000, $105,000, and $97,500, respectively. What are the total costs to be allocated from Department S1?
(Multiple Choice)
4.8/5 (68)
(68) McDuff Company uses a job-order costing system to compute product costs. There are two producing departments (P1 and P2) and two support departments (S1 and S2). The costs incurred in S1 and S2 are allocated to Departments A and B and included in their factory overhead rates for costing products. S1 costs are allocated based on the number of employees, S2 costs are allocated based on direct labor hours, and the production departmental overhead rates are also based on direct labor hours. The following data are available for a recent period:
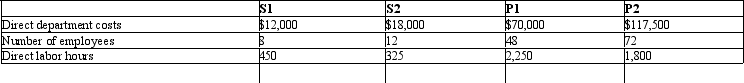 Required:
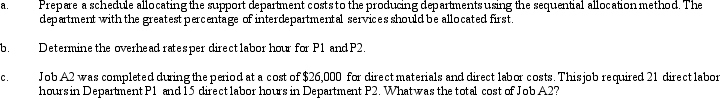
Required:
(Essay)
4.8/5 (89)
(89) Deli Products produces two products, X and Y, in a single process. In 2011, the joint costs of this process were $25,000. In addition, 4,000 units of X and 6,000 units of Y were produced and sold. Separable processing costs beyond the split-off point were: X - $10,000; Y - $20,000. X sells for $10.00 per unit; Y sells for $7.50 per unit. What is the gross profit of product Y assuming the physical units method is used?
(Multiple Choice)
4.8/5 (69)
(69) The activities or variables within a producing department that provoke the incurrence of support costs are called:
(Multiple Choice)
4.8/5 (87)
(87) Producing departments provide essential services for support departments.
(True/False)
5.0/5 (85)
(85) Soy Products produces two products, Soyburgers and Soy steaks, in a single process. In 2014, the joint costs of this process were $36,000. In addition, 20,000 pounds of soyburgers and 10,000 pounds of soy steaks were produced. Separable processing costs beyond the split-off point were: soyburgers, $7,500; soy steaks, $4,500. Soyburgers sells for $2 per pound; Soy steaks sells for $4 per pound.
Required:
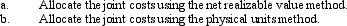
(Essay)
4.8/5 (67)
(67) Costs that are easily traced to individual products are called separable costs.
(True/False)
4.9/5 (76)
(76) The choice of allocation method depends on an evaluation of costs and benefits, and circumstances.
(True/False)
4.9/5 (75)
(75) Evergreen Company has two support departments (S1 and S2) and two producing departments (P1 and P2). Department S1 costs are allocated on the basis of number of employees, and Department S2 costs are allocated on the basis of space occupied expressed in square feet. Data on direct department costs, number of employees, and space occupied are as follows:
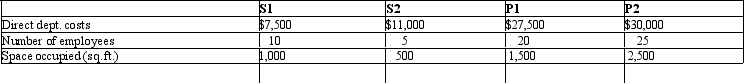 If Evergreen uses the direct method, the ratio representing the portion of Department S2 allocated to P1 is
 (Multiple Choice)
4.8/5 (77)
(77) Figure 7-7 Garden of Eden Company manufactures two products, Brights and Dulls, from a joint process. A production run costs $50,000 and results in 250 units of Brights and 1,000 units of Dulls. Both products must be processed past the split-off point, incurring separable costs for Brights of $60 per unit and $40 per unit for Dulls. The market price is $250 for Brights and $200 for Dulls.
Refer to Figure 7-7. What is the amount of joint costs allocated to Dulls using the physical units method?
(Multiple Choice)
4.9/5 (72)
(72) Vladimir, Inc. began the current period with no inventories. During the period, it processed 50,000 pounds of materials costing $450,000. Conversion costs incurred during the period amounted to $660,000. The firm ended the period with no work-in-process. During the period, the firm produced 16,000, 24,000, and 10,000 units of X, Y, and Z, respectively. All costs are considered joint costs. The firm sold 12,000 units of X, 16,000 units of Y, and 9,000 units of Z. X sells for $30 per unit, Y for $44 per unit, and Z for $4 per unit. The firm uses the net realizable value method for cost allocation. Z is considered a by-product.
Required:
(Essay)
4.8/5 (77)
(77) The split-off point is the ending point of a joint product process.
(True/False)
4.7/5 (84)
(84) Andover, Inc., has two producing departments. Each producing department is held responsible for a share of the costs of a support department. Actual and budgeted data are as follows:
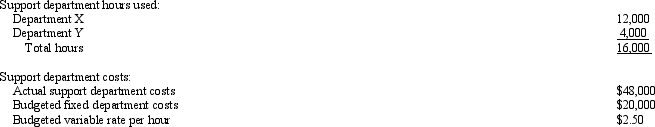 Normal support department usage is 8,000 hours each for Department X and Department Y. Assuming the direct method is used and the purpose is performance evaluation, support department costs allocated to Department X are
 (Multiple Choice)
4.8/5 (89)
(89) If the allocation is for product costing, the allocation of variable support department costs would be calculated as
(Multiple Choice)
4.9/5 (92)
(92) Henderson Company pays a flat fee of $500 for the right to retrieve stray golf balls from lakes and ponds at golf and country clubs. The recovered balls are then cleaned, graded as to quality (birdie, bogey, or duffer), and sold to sporting goods stores at the following prices per dozen: birdie quality, $5; bogey quality, $4; and duffer quality, $3. Last month $8,000 of cost was incurred retrieving the following quantities of golf balls: birdie quality, 1,000 dozen; bogey quality, 3,000 dozen; and duffer quality, 2,000 dozen.
Required: (Calculate relative quantity to three decimal points.)

(Essay)
5.0/5 (79)
(79) Support department fixed costs are allocated on the basis of original capacity.
(True/False)
4.9/5 (79)
(79) The __________ method of allocating costs, allocates costs from support to producing departments.
(Short Answer)
4.9/5 (94)
(94) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)