



 Chat with AI
Exam 7: Allocating Costs of Support Departments and Joint Products

Exam 1: Introduction to Cost Management157 Questions
Exam 2: Basic Cost Management Concepts201 Questions
Exam 3: Cost Behavior200 Questions
Exam 4: Activity-Based Costing201 Questions
Exam 5: Product and Service Costing: Job-Order System150 Questions
Exam 6: Process Costing188 Questions
Exam 7: Allocating Costs of Support Departments and Joint Products173 Questions
Exam 8: Budgeting for Planning and Control Key200 Questions
Exam 9: Standard Costing: a Functional-Based Control Approach123 Questions
Exam 10: Decentralization: Responsibility Accounting, Performance Evaluation, and Transfer Pricing139 Questions
Exam 11: Strategic Cost Management151 Questions
Exam 12: Activity-Based Management146 Questions
Exam 13: The Balanced Scorecard: Strategic-Based Control124 Questions
Exam 14: Quality and Environmental Cost Management202 Questions
Exam 15: Lean Accounting and Productivity Measurement172 Questions
Exam 16: Cost-Volume-Profit Analysis138 Questions
Exam 17: Activity Resource Usage Model and Tactical Decision Making128 Questions
Exam 18: Pricing and Profitability Analysis164 Questions
Exam 19: Capital Investment126 Questions
Exam 20: Inventory Management: Economic Order Quantity, Jit, and the Theory of Constraints127 Questions
Select questions type


A company incurred $120,000 of common fixed costs and $180,000 of common variable costs. These costs are to be allocated to Departments XX and YY. Data on capacity provided and capacity used are as follows:  Assume that common fixed costs are to be allocated to Departments XX and YY on the basis of capacity provided and that common variable costs are to be allocated to Departments XX and YY on the basis of capacity used. The fixed and variable costs allocated to Department XX are

Assume that common fixed costs are to be allocated to Departments XX and YY on the basis of capacity provided and that common variable costs are to be allocated to Departments XX and YY on the basis of capacity used. The fixed and variable costs allocated to Department XX are
(Multiple Choice)
4.8/5  (82)
(82) If the allocation is for performance evaluation, the allocation of variable support department costs would be calculated as
(Multiple Choice)
4.9/5 (69)
(69) Which of the major objectives of allocation as identified by the IMA would NOT be relevant in a service organization?
(Multiple Choice)
4.9/5 (73)
(73) Departmental __________ is applied to products passing through the department.
(Short Answer)
4.8/5 (85)
(85) Products with substantial value which are produced simultaneously by the same process up to a split-off point are called:
(Multiple Choice)
4.8/5 (72)
(72) Which of the following would NOT be a criteria used to rank departments to determine order of allocation under the sequential method?
(Multiple Choice)
4.9/5 (84)
(84) Figure 7-3 Hanover and Trust, a large law firm, utilizes an internal centralized printing center to serve its three departments: Individuals, Corporate, Trust. The costs of the printing department include fixed costs of $69,190 and variable costs of $0.04 per page. Total estimated print pages are estimated to be 330,000 pages. Individuals are estimated to use 130,000; Corporate will use
165,000 and 35,000 from the trust area.
Refer to Figure 7-3. Assuming a single charging rate is used, what would be the charge per page? (round to the nearest cent)
(Multiple Choice)
4.8/5 (80)
(80) After allocation, total overhead in producing department is divided by the budgeted measure of activity to get the __________ overhead rate.
(Short Answer)
4.8/5 (78)
(78) Mandala Inc. obtains two products and a by-product from its production process. By-product revenues are treated as other income and a noncost approach is used to assign costs to them. During the period, 1,200 units were processed at a cost of $12,000 for materials and conversion costs, resulting in the following:
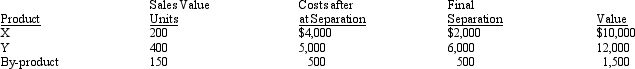 Required:
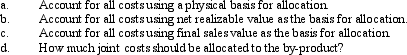
Required:
(Essay)
4.7/5 (72)
(72) Chrome Enterprises has two support departments (S1 and S2) and two producing departments (A and B). The distribution of services by the support departments is as follows:
 Total department costs for the support and producing departments are as follows:
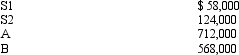 Required:
Find the amount of total costs for A and B using the reciprocal method.
Total department costs for the support and producing departments are as follows:
Required:
Find the amount of total costs for A and B using the reciprocal method. (Essay)
4.8/5 (82)
(82) Joint production processes result in the output of two or more products produced simultaneously.
(True/False)
4.8/5 (98)
(98) FIGURE 7-5 Stronghold, Inc., operates a brochure business at two different locations. Stronghold, Inc., has one support department that is responsible for cleaning, service, and maintenance of its printing equipment. The costs of the support department are allocated to each brochure center on the basis of total brochures made.
During the first month, the costs of the support department were expected to be $400,000. Of this amount, $120,000 is considered a fixed cost. During the month, the support department incurred actual variable costs of $256,000 and actual fixed costs of $144,000.
Normal and actual activity (brochures made) are as follows:
 Refer to Figure 7-5. For purposes of performance evaluation, fixed costs allocated to
Brochure Center 2 are
Refer to Figure 7-5. For purposes of performance evaluation, fixed costs allocated to
Brochure Center 2 are (Multiple Choice)
5.0/5 (96)
(96) Julius Manufacturing prices its products at full cost plus 30 percent. The company operates two support departments and two producing departments. Budgeted costs and normal activity levels are as follows: 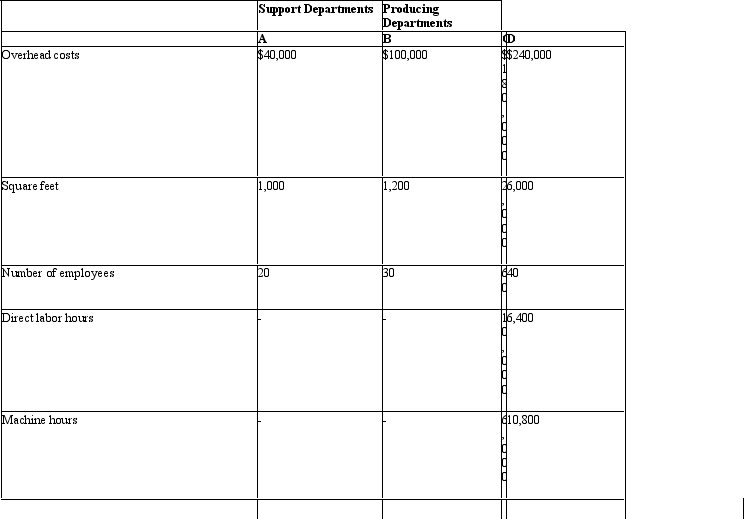 Support Department A's costs are allocated based on square feet, and Support Department B's costs are allocated based on number of employees.
Department C uses direct labor hours to assign overhead costs to products, while Department D uses machine hours.
One of the products the company produces requires 4 direct labor hours per unit in Department C and no time in Department D. Direct materials for the product cost $180 per unit, and direct labor is $80 per unit.
If the direct method of allocation is used and the company follows its usual pricing policy, the selling price of the product would be
Support Department A's costs are allocated based on square feet, and Support Department B's costs are allocated based on number of employees.
Department C uses direct labor hours to assign overhead costs to products, while Department D uses machine hours.
One of the products the company produces requires 4 direct labor hours per unit in Department C and no time in Department D. Direct materials for the product cost $180 per unit, and direct labor is $80 per unit.
If the direct method of allocation is used and the company follows its usual pricing policy, the selling price of the product would be (Multiple Choice)
5.0/5 (85)
(85) Saturn Company manufactures products X, Y, and Z in a joint process. The following information is available:
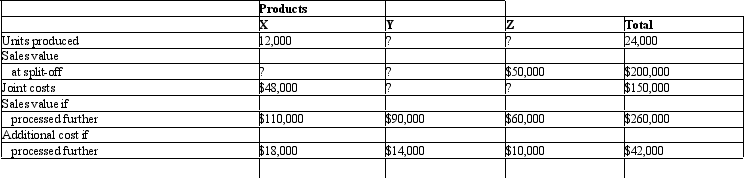 Joint product costs are allocated using the sales value at split-off approach.
Required:
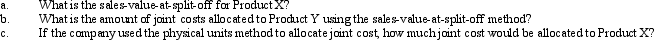
Joint product costs are allocated using the sales value at split-off approach.
Required:
(Essay)
4.9/5 (75)
(75) Cumadin Corporation, which manufactures products W, X, Y, and Z through a joint process costing $18,000, has the following data for 2014: 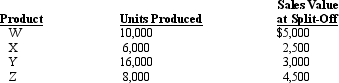 What is the amount of joint costs assigned to Product X using the sales-value-at-split-off method?
 (Multiple Choice)
4.8/5 (84)
(84) Andover,, Inc., has two producing departments. Each producing department is held responsible for a share of the costs of a support department. Actual and budgeted data are as follows:
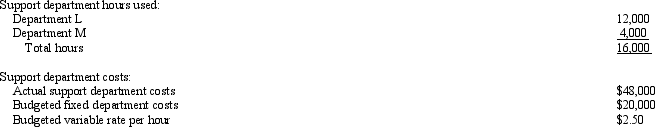 Normal support department usage is 8,000 hours each for Department L and Department M. Assuming the direct method is used and the purpose is product costing, support department costs allocated to Department L are
 (Multiple Choice)
4.8/5 (81)
(81) The reciprocal method of allocation recognizes only some of the support departments' interactions.
(True/False)
4.8/5 (92)
(92) Which of the following methods allocates support department costs?
(Multiple Choice)
4.7/5 (76)
(76) FIGURE 7-5 Stronghold, Inc., operates a brochure business at two different locations. Stronghold, Inc., has one support department that is responsible for cleaning, service, and maintenance of its printing equipment. The costs of the support department are allocated to each brochure center on the basis of total brochures made.
During the first month, the costs of the support department were expected to be $400,000. Of this amount, $120,000 is considered a fixed cost. During the month, the support department incurred actual variable costs of $256,000 and actual fixed costs of $144,000.
Normal and actual activity (brochures made) are as follows:
 Refer to Figure 7-5.For purposes of performance evaluation, fixed costs allocated to
Brochure Center 1 are
Refer to Figure 7-5.For purposes of performance evaluation, fixed costs allocated to
Brochure Center 1 are (Multiple Choice)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)