



 Chat with AI
Exam 19: Corporations: Distributions Not in Complete Liquidation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law195 Questions
Exam 2: Working With the Tax Law86 Questions
Exam 3: Computing the Tax187 Questions
Exam 4: Gross Income: Concepts and Inclusions124 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: in General146 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses95 Questions
Exam 8: Depreciation, cost Recovery, amortization, and Depletion103 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses181 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions105 Questions
Exam 11: Investor Losses111 Questions
Exam 12: Tax Credits and Payments118 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, basis Considerations, and Nontaxable Exchanges280 Questions
Exam 14: Property Transactions, capital Gains and Losses, sec1231, and Recapture Provisions145 Questions
Exam 15: Alternative Minimum Tax132 Questions
Exam 16: Accounting Periods and Methods91 Questions
Exam 17: Corporations: Introduction and Operating Rules112 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation192 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganization72 Questions
Exam 21: Partnerships163 Questions
Exam 22: S Corporations145 Questions
Exam 23: Exempt Entities141 Questions
Exam 24: Multistate Corporate Taxation196 Questions
Exam 25: Taxation of International Transactions164 Questions
Exam 26: Tax Practice and Ethics183 Questions
Exam 27: The Federal Gift and Estate Taxes167 Questions
Exam 28: Income Taxation of Trusts and Estates167 Questions
Select questions type


Matching
Using the legend provided, classify each statement accordingly. In all cases, assume that taxable income is being adjusted to arrive at current E & P for 2017.
a.Increase
b.Decrease
c.No effect
-Premiums paid on key employee life insurance policy (assume no increase in cash surrender value of policy) in 2017.
(Short Answer)
4.7/5  (83)
(83) Ethel,Hannah,and Samuel,unrelated individuals,own the stock in Broadbill Corporation (E & P of $700,000) as follows: Ethel,300 shares; Hannah,300 shares; and Samuel,400 shares.Broadbill redeems 200 of Samuel's shares (basis of $175,000) for $250,000.If Samuel's stock is a capital asset and has been held for over three years,Samuel has:
(Multiple Choice)
4.9/5 (88)
(88) Yolanda owns 60% of the outstanding stock of Amber Corporation.In a qualifying stock redemption,Amber distributes $20,000 to Yolanda in exchange for one-half of her shares (basis of $35,000).As a result of the redemption,Yolanda has a recognized capital loss of $15,000.
(True/False)
4.8/5 (71)
(71) The tax treatment of corporate distributions at the shareholder level does not depend on:
(Multiple Choice)
4.8/5 (85)
(85) Corporate shareholders generally receive less favorable tax treatment from a qualifying stock redemption than from a dividend distribution.
(True/False)
4.9/5 (77)
(77) Last year,Crow Corporation acquired land in a transaction that qualified under § 351.The land had a basis of $400,000 to the contributing shareholder and a fair market value of $310,000.Assume that the shareholder also transferred equipment (basis of $100,000,fair market value of $200,000) in the same § 351 exchange.In the current year,Crow Corporation adopted a plan of liquidation and distributes the land to Ali,a shareholder who owns 20% of the stock in Crow Corporation.The land's fair market value was $230,000 on the date of the distribution to Ali.Crow Corporation acquired the land to use as security for a loan it had hoped to obtain from a local bank.In negotiating with the bank for a loan,the bank required the additional capital investment as a condition of its making a loan to Crow Corporation.How much loss can Crow Corporation recognize on the distribution of the land?
(Multiple Choice)
4.9/5 (79)
(79) In general,if a shareholder's ownership interest is not diminished as a result of a stock redemption,the Code will treat the transaction as a sale or exchange.
(True/False)
4.9/5 (73)
(73) Certain dividends from foreign corporations can be qualified dividends for purposes of the preferential rate available to individuals.
(True/False)
4.8/5 (85)
(85) Explain why the antistuffing rules were enacted to limit the deductibility of losses realized by a corporation upon liquidation.
(Essay)
4.9/5 (80)
(80) A realized gain from an involuntary conversion under § 1033 that is not recognized for income tax purposes has no effect on E & P.
(True/False)
4.8/5 (86)
(86) On January 30,Juan receives a nontaxable distribution of stock rights from Platinum Corporation.Each right entitles the holder to purchase one share of stock for $40.One right is issued for every share of stock owned.Juan owns 100 shares of stock purchased two years ago for $4,000.At the date of distribution,the rights are worth $1,000 (100 rights at $10 per right) and Juan's stock in Platinum is worth $5,000 (or $50 per share).On December 1,Juan sells all 100 stock rights for $12 per right.How much gain does Juan recognize on the sale?
(Multiple Choice)
4.8/5 (61)
(61) Which of the following statements is incorrect with respect to determining current E & P?
(Multiple Choice)
4.8/5 (75)
(75) In general,how are current and accumulated earnings and profits allocated to corporate distributions?
(Essay)
4.9/5 (77)
(77) The terms "earnings and profits" and "retained earnings" are identical in meaning.
(True/False)
4.9/5 (68)
(68) Briefly describe the reason a corporation might distribute a property dividend to a shareholder in lieu of a cash distribution.Describe the tax effects of the property distribution on the shareholder and on the corporation.
(Essay)
4.9/5 (74)
(74) What is a constructive dividend? Provide several examples of the term.
(Essay)
4.9/5 (77)
(77) Pebble Corporation,an accrual basis taxpayer,has struggled to survive since its formation,six years ago.As a result,it has a deficit in accumulated E & P at the beginning of the year of $340,000.This year,however,Pebble earned a significant profit; taxable income was $240,000.Consequently,Pebble made two cash distributions to Martha,its sole shareholder: $150,000 on July 1 and $200,000 December 31.The following information might be relevant to determining the tax treatment of the distributions.
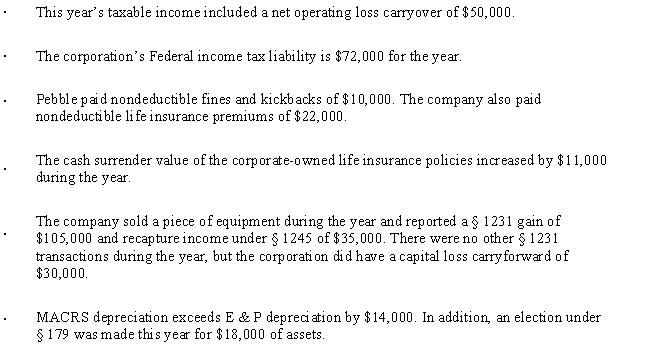 a.Compute Pebble's E & P for the year.
b.What are the tax consequences of the two distributions made during the year to Martha (her stock basis is $74,000)?
a.Compute Pebble's E & P for the year.
b.What are the tax consequences of the two distributions made during the year to Martha (her stock basis is $74,000)? (Essay)
4.9/5 (82)
(82) Matching
Using the legend provided, classify each statement accordingly. In all cases, assume that taxable income is being adjusted to arrive at current E & P for 2017.
a.Increase
b.Decrease
c.No effect
-Federal income tax refunds from tax paid in prior years.
(Short Answer)
4.8/5 (83)
(83) Falcon Corporation ended its first year of operations with taxable income of $250,000.At the time of Falcon's formation,it incurred $50,000 of organizational expenses.In calculating its taxable income for the year,Falcon claimed an $8,000 deduction for the organizational expenses.What is Falcon's current E & P?
(Multiple Choice)
4.8/5 (68)
(68) Tangelo Corporation has an August 31 year-end.Tangelo had $50,000 in accumulated E & P at the beginning of its 2018 fiscal year (September 1,2017) and during the year,it incurred a $75,000 operating loss.It also distributed $65,000 to its sole shareholder,Cass,on November 30,2017.If Cass is a calendar year taxpayer,how should she treat the distribution when she files her 2017 income tax return (assuming the return is filed by April 15,2018)?
(Multiple Choice)
4.9/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)