



 Chat with AI
Exam 19: Corporations: Distributions Not in Complete Liquidation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law195 Questions
Exam 2: Working With the Tax Law86 Questions
Exam 3: Computing the Tax187 Questions
Exam 4: Gross Income: Concepts and Inclusions124 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: in General146 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses95 Questions
Exam 8: Depreciation, cost Recovery, amortization, and Depletion103 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses181 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions105 Questions
Exam 11: Investor Losses111 Questions
Exam 12: Tax Credits and Payments118 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, basis Considerations, and Nontaxable Exchanges280 Questions
Exam 14: Property Transactions, capital Gains and Losses, sec1231, and Recapture Provisions145 Questions
Exam 15: Alternative Minimum Tax132 Questions
Exam 16: Accounting Periods and Methods91 Questions
Exam 17: Corporations: Introduction and Operating Rules112 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation192 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganization72 Questions
Exam 21: Partnerships163 Questions
Exam 22: S Corporations145 Questions
Exam 23: Exempt Entities141 Questions
Exam 24: Multistate Corporate Taxation196 Questions
Exam 25: Taxation of International Transactions164 Questions
Exam 26: Tax Practice and Ethics183 Questions
Exam 27: The Federal Gift and Estate Taxes167 Questions
Exam 28: Income Taxation of Trusts and Estates167 Questions
Select questions type


When does a redemption qualify as a not essentially equivalent redemption under § 302(b)(1)?
(Essay)
4.9/5  (83)
(83) Seven years ago,Eleanor transferred property she had used in her sole proprietorship to Blue Corporation for 2,000 shares of Blue Corporation in a transaction that qualified under § 351.The assets had a tax basis to her of $400,000 and a fair market value of $700,000 on the date of the transfer.In the current year,Blue Corporation (E & P of $1 million) redeems 600 shares from Eleanor for $260,000 in a transaction that qualifies for sale or exchange treatment.With respect to the redemption,Eleanor will have a:
(Multiple Choice)
4.7/5 (103)
(103) Distributions by a corporation to its shareholders are presumed to be a dividend unless the parties can prove otherwise.
(True/False)
4.8/5 (63)
(63) Aaron and Michele,equal shareholders in Cavalier Corporation,receive $25,000 each in distributions on December 31 of the current year.During the current year,Cavalier sold an appreciated asset for $60,000 (basis of $15,000).Payment for the sale of the asset will be made as follows: 50% next year and 50% in the following year,with interest payable at a rate of 6 percent.Before considering the effect of the asset sale,Cavalier's current year E & P is $40,000 and it has no accumulated E & P.How much of Aaron's distribution will be taxed as a dividend?
(Multiple Choice)
4.9/5 (84)
(84) Raul's gross estate includes 1,500 shares of stock of Orange Corporation (basis to Raul of $600,000,fair market value on date of death of $4.1 million).The estate will incur $2.2 million of death taxes and funeral and administration expenses,and the adjusted gross estate is $9 million.Denise,Raul's daughter and sole heir of his estate,owns the remaining 500 shares of Orange Corporation's shares outstanding.In the current year,Orange (E&P of $5 million) redeems all of the estate's 1,500 shares for $4.1 million.What are the tax consequences of the redemption to Raul's estate?
(Essay)
4.8/5 (82)
(82) Matching
Using the legend provided, classify each statement accordingly. In all cases, assume that taxable income is being adjusted to arrive at current E & P for 2017.
a.Increase
b.Decrease
c.No effect
-Gain on installment sale in 2017 deferred until 2018.
(Short Answer)
4.7/5 (88)
(88) Explain the stock attribution rules that apply in the case of stock redemptions.
(Essay)
4.9/5 (73)
(73) Goldfinch Corporation distributes stock rights to its shareholders.How is the basis of the stock rights received by Goldfinch's shareholders determined?
(Essay)
4.8/5 (100)
(100) No E & P adjustment is required for regular tax gains under the installment method.
(True/False)
4.9/5 (80)
(80) Maria and Christopher each own 50% of Cockatoo Corporation,a calendar year taxpayer.Distributions from Cockatoo are: $750,000 to Maria on April 1 and $250,000 to Christopher on May 1.Cockatoo's current E & P is $300,000 and its accumulated E & P is $600,000.How much of the accumulated E & P is allocated to Christopher's distribution?
(Multiple Choice)
4.9/5 (71)
(71) Reginald and Roland (Reginald's son) each own 50% of the stock of Robin Corporation.Reginald's stock interest is entirely redeemed by Robin Corporation.Two years later,Reginald loans Robin Corporation $250,000.The loan to Robin Corporation does not constitute a prohibited interest for purposes of the family attribution waiver.
(True/False)
4.9/5 (84)
(84) The adjusted gross estate of Keith,decedent,is $12 million.Included in the gross estate is stock in Gold Corporation (E & P of $1.3 million),a closely held corporation,valued at $4.6 million as of the date of Keith's death.Keith had acquired the stock twelve years ago at a cost of $900,000.Death taxes and funeral and administration expenses for Keith's estate are $2.3 million.Gold Corporation redeems one-half of the stock from Keith's estate in a § 303 redemption to pay death taxes using property with a fair market value of $2.3 million (adjusted basis of $1.9 million).Which of the following is a correct statement regarding the tax consequences of this redemption?
(Multiple Choice)
4.9/5 (83)
(83) Property distributed by a corporation as a dividend is subject to a liability in excess of its basis.For purposes of determining gain on the distribution,the basis of the property is treated as being not less than the amount of liability.
(True/False)
4.8/5 (83)
(83) To carry out a qualifying stock redemption,Turaco Corporation (E & P of $800,000) transfers land held for investment purposes to Aida,a shareholder.The land had a basis of $250,000,a fair market value of $400,000,and is subject to a $300,000 liability.Aida has a basis of $70,000 in the shares redeemed.Which of the following is a correct statement regarding the tax consequences of this redemption?
(Multiple Choice)
4.8/5 (78)
(78) Starling Corporation was organized fifteen years ago to construct office furniture.Eight years ago,Starling began a fast food business.In the current year,Starling discontinues its fast food business and sells all of the assets used in that business for $2 million.Further,Starling distributes the entire sales proceeds in a pro rata redemption of 250 shares of stock from each of its two equal shareholders-Morgan,an individual,and Magpie Corporation.Morgan has a basis of $100,000 in her redeemed stock,Magpie Corporation has a basis of $125,000 in its redeemed stock,and both shareholders have held their stock interest in Starling for several years.Starling Corporation has E & P of $4 million and 2,000 shares outstanding at the time of the distribution.What are the tax consequences of the stock redemption to Morgan,to Magpie Corporation,and to Starling Corporation?
(Essay)
4.8/5 (79)
(79) At the beginning of the current year,Doug and Alfred each own 50% of Amaryllis Corporation (a calendar year taxpayer).In July,Doug sold his stock to Kevin for $140,000.At the beginning of the year,Amaryllis Corporation had accumulated E & P of $240,000 and its current E & P is $280,000 (prior to any distributions).Amaryllis distributed $300,000 on February 15 ($150,000 to Doug and $150,000 to Alfred) and distributed another $300,000 on November 1 ($150,000 to Kevin and $150,000 to Alfred).Kevin has dividend income of:
(Multiple Choice)
4.7/5 (84)
(84) Matching
Using the legend provided, classify each statement accordingly. In all cases, assume that taxable income is being adjusted to arrive at current E & P for 2017.
a.Increase
b.Decrease
c.No effect
-Cash dividends distributed to shareholders in 2017.
(Short Answer)
4.9/5 (87)
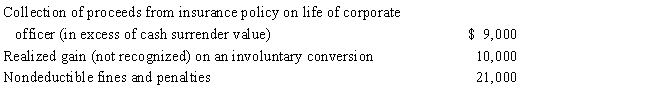
(87) Kite Corporation,a calendar year taxpayer,has taxable income of $360,000 for 2018.Among its transactions for the year are the following:
Disregarding any provision for Federal income taxes,determine Kite Corporation's current E & P for 2018.
(Essay)
4.8/5 (70)
(70) Jen,the sole shareholder of Mahogany Corporation,sold her stock to Jason on July 1 for $90,000.Jen's stock basis at the beginning of the year was $60,000.Mahogany made a $30,000 cash distribution to Jen immediately before the sale,while Jason received a $60,000 cash distribution from Mahogany on November 1.As of the beginning of the current year,Mahogany had $16,000 in accumulated E & P,while current E & P (before distributions) is $30,000.What are the tax consequences of these transactions to Jen and Jason?
(Essay)
4.8/5 (91)
(91) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)