



 Chat with AI
Exam 21: Partnerships

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law195 Questions
Exam 2: Working With the Tax Law86 Questions
Exam 3: Computing the Tax187 Questions
Exam 4: Gross Income: Concepts and Inclusions124 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: in General146 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses95 Questions
Exam 8: Depreciation, cost Recovery, amortization, and Depletion103 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses181 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions105 Questions
Exam 11: Investor Losses111 Questions
Exam 12: Tax Credits and Payments118 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, basis Considerations, and Nontaxable Exchanges280 Questions
Exam 14: Property Transactions, capital Gains and Losses, sec1231, and Recapture Provisions145 Questions
Exam 15: Alternative Minimum Tax132 Questions
Exam 16: Accounting Periods and Methods91 Questions
Exam 17: Corporations: Introduction and Operating Rules112 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation192 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganization72 Questions
Exam 21: Partnerships163 Questions
Exam 22: S Corporations145 Questions
Exam 23: Exempt Entities141 Questions
Exam 24: Multistate Corporate Taxation196 Questions
Exam 25: Taxation of International Transactions164 Questions
Exam 26: Tax Practice and Ethics183 Questions
Exam 27: The Federal Gift and Estate Taxes167 Questions
Exam 28: Income Taxation of Trusts and Estates167 Questions
Select questions type


Match each of the following statements with the terms below that provide the best definition.
a.Organizational choice of many large accounting firms.
b.Partner's percentage allocation of current operating income.
c.Might affect any two partners' tax liabilities in different ways.
d.Brokerage and registration fees incurred for promoting and marketing partnership interests.
e.Transfer of asset to partnership followed by immediate distribution of cash to partner.
f.Must have at least one general and one limited partner.
g.All partners are jointly and severally liable for entity debts.
h.Theory treating the partner and partnership as separate economic units.
i.Partner's basis in partnership interest after tax-free contribution of asset to partnership.
j.Partnership's basis in asset after tax-free contribution of asset to partnership.
k.Owners are "members."
l.Theory treating the partnership as a collection of taxpayers joined in an agency relationship.
m.Allows many unincorporated entities to select their Federal tax status.
n.No correct match provided.
-Disguised sale
(Short Answer)
4.8/5  (68)
(68) Rebecca is a limited partner in the RST Partnership,which is not publicly traded.Her allocable share of RST's passive ordinary losses from a nonrealty activity for the current year is ($60,000).Rebecca has a $40,000 adjusted basis (outside basis) for her interest in RST (before deduction of any of the passive losses).Her amount "at risk" is $30,000 (before deduction of any of the passive losses).She also has $25,000 of passive income from other sources.How much of her ($60,000) allocable loss can Rebecca deduct on her current year's tax return?
(Multiple Choice)
4.8/5 (62)
(62) Which of the following entity owners cannot participate in management of the entity?
(Multiple Choice)
4.9/5 (71)
(71) Ryan is a 25% partner in the ROCC Partnership.At the beginning of the tax year,Ryan's basis in the partnership interest was $90,000,including his share of partnership liabilities.During the current year,ROCC reported net ordinary income of $100,000.In addition,ROCC distributed $10,000 to each of the partners ($40,000 total).At the end of the year,Ryan's share of partnership liabilities increased by $10,000.Ryan's basis in the partnership interest at the end of the year is:
(Multiple Choice)
4.9/5 (89)
(89) Match each of the following statements with the terms below that provide the best definition.
a.Organizational choice of many large accounting firms.
b.Partner's percentage allocation of current operating income.
c.Might affect any two partners' tax liabilities in different ways.
d.Brokerage and registration fees incurred for promoting and marketing partnership interests.
e.Transfer of asset to partnership followed by immediate distribution of cash to partner.
f.Must have at least one general and one limited partner.
g.All partners are jointly and severally liable for entity debts.
h.Theory treating the partner and partnership as separate economic units.
i.Partner's basis in partnership interest after tax-free contribution of asset to partnership.
j.Partnership's basis in asset after tax-free contribution of asset to partnership.
k.Owners are "members."
l.Theory treating the partnership as a collection of taxpayers joined in an agency relationship.
m.Allows many unincorporated entities to select their Federal tax status.
n.No correct match provided.
-Separately stated item
(Short Answer)
4.8/5 (77)
(77) JLK Partnership incurred $6,000 of organizational costs and $50,000 of startup costs in 2016.JKL may deduct $5,000 each of organizational and startup costs,and the remaining costs ($1,000 of organizational costs and $45,000 of startup costs) may be amortized over 60 months.
(True/False)
4.8/5 (88)
(88) The MOP Partnership is involved in construction activities.Patricia has an adjusted basis for her partnership interest on January 1 of the current year of $600,000,consisting of the following.
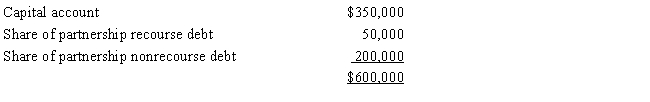 During the year,the partnership has an operating loss of $1.2 million and distributes $60,000 of cash to Patricia.Partnership liabilities were the same at the end of the tax year,and the nonrecourse debt is not "qualified nonrecourse debt." If she owns a 60% share of partnership profits,capital,and losses,and is an active ("material") participant in the partnership,how much of her share of the operating loss can Patricia deduct? What Code provisions could cause a suspension of the loss? How would your answer change if MOP were an LLC and Patricia had not personally guaranteed any of the debt?
 (Essay)
4.9/5 (72)
(72) A partnership must provide any information to the partners that the partners would need to calculate deductions not permitted at the partnership level,such as for oil and gas depletion or the corporate dividends received deduction.
(True/False)
4.7/5 (81)
(81) Kristie is a 30% partner in the KKM Partnership.During the current year,KKM reported gross receipts of $280,000 and a charitable contribution of $30,000.The partnership paid office expenses of $80,000.In addition,KKM distributed $20,000 each to partners Kaylyn and Megan,and the partnership paid partner Kaylyn $20,000 for administrative services.Kristie reports the following income from KKM during the current tax year:
(Multiple Choice)
4.9/5 (72)
(72) When Kevin and Marshall formed the equal KM LLC,the fair market values of their interests were each $100,000.Kevin contributed $60,000 cash,equipment with a basis of $0 and a fair market value of $10,000,and a small parcel of land in which he had a basis of $50,000 and which was valued at $30,000.Marshall contributed an account receivable that was valued at $100,000 and which his basis was $0.Kevin has a basis in his partnership interest of $110,000 and Marshall's basis is $0.
(True/False)
4.9/5 (82)
(82) BRW Partnership reported gross income from operations of $60,000,interest income of $3,000,rental expense of $20,000,and a charitable contribution of $6,000.On its Schedule K,the partnership reports ordinary business income of $40,000,and separately stated interest income ($3,000) and charitable contributions ($6,000).
(True/False)
4.8/5 (82)
(82) George and James are forming the GJ Partnership.George contributes $600,000 cash and James contributes nondepreciable property with an adjusted basis of $400,000 and a fair market value of $750,000.The property is subject to a $150,000 liability,which is also transferred into the partnership and is shared equally by the partners for basis purposes.George and James share in all partnership profits equally except for any precontribution gain,which must be allocated according to the statutory rules for built-in gain allocations.
a.What is James's adjusted tax basis for his partnership interest immediately after the partnership is formed?
b.What is the partnership's adjusted basis for the property contributed by James?
c.If the partnership sells the property contributed by James for $800,000, how is the tax gain allocated between the partners?
(Essay)
4.9/5 (86)
(86) George received a fully-vested 10% interest in partnership capital and a 20% interest in future partnership profits in exchange for services rendered to the GHP,LLC (not a publicly-traded partnership interest).The future profits of the partnership are subject to normal operating risks.George will report ordinary income equal to the fair market value of the profits interest,but the capital interest will not be currently taxed to him.
(True/False)
5.0/5 (73)
(73) Section 721 provides that no gain or loss is recognized on a contribution of property to a partnership in exchange for an interest in the partnership.An exception might apply if the taxpayer receives a cash distribution from the partnership soon after the property contribution is made.
(True/False)
4.8/5 (84)
(84) At the beginning of the tax year,Zach's basis for his partnership interest and his amount at risk in the partnership was $30,000.His share of partnership items for the year consisted of tax-exempt interest income of $2,000 and an ordinary loss of $44,000.He also received a distribution from the partnership of $20,000 cash during the year.For the tax year,Zach will report:
(Multiple Choice)
4.8/5 (83)
(83) George is a limited partner in the GLH Partnership.His basis is $40,000 before considering the current year operations,and includes a $20,000 recourse debt share and a $10,000 nonrecourse debt share.The nonrecourse debt is not treated as qualified nonrecourse financing.GLH reported a $200,000 loss for the year,of which George's 40% share is $80,000.George has passive income of $50,000 from another activity (not eligible for the special real estate deduction).How much of the $80,000 loss can George deduct this year?
(Multiple Choice)
4.8/5 (84)
(84) ABC LLC reported the following items on the LLC's Schedule K: ordinary income,$100,000; interest income,$3,000; long-term capital loss,($4,000); charitable contributions,$1,000; post-1986 depreciation adjustment,$10,000; and cash distributions to partners,$50,000.How much will ABC show as net income (loss) on its Analysis of Income (Loss)?
(Multiple Choice)
4.9/5 (89)
(89) Match each of the following statements with the terms below that provide the best definition.
Match each of the following statements with the terms below that provide the best definition.
a. Adjusted basis of each partnership asset.
b. Operating expenses incurred after entity is formed but before it begins doing business.
c. Each partner's basis in the partnership.
d. Reconciles book income to "taxable income."
e. Tax accounting election made by partnership.
f. Tax accounting calculation made by partner.
g. Tax accounting election made by partner.
h. Does not include liabilities.
i. Designed to prevent excessive deferral of taxation of partnership income.
j. Amount that may be received by partner for performance of services for the partnership.
k. Theory under which a partnership's recourse debt is shared among the partners.
l. Will eventually be allocated to partner making tax-free property contribution to partnership.
m. Partner's share of partnership items.
n. Must generally be satisfied by any allocation to the partners.
o. Justification for a tax year other than the required taxable year.
p. No correct match is provided.
-Economic risk of loss
(Short Answer)
4.8/5 (67)
(67) The taxable income of a partnership flows through to the partners,who report the income on their tax returns.
(True/False)
4.9/5 (73)
(73) ABC,LLC is equally-owned by three corporations.Two corporations have June 30 fiscal year ends,the third is a calendar-year taxpayer.ABC will use the least aggregate deferral method to determine its taxable year-end.
(True/False)
4.9/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)