



 Chat with AI
Exam 21: Partnerships

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law195 Questions
Exam 2: Working With the Tax Law86 Questions
Exam 3: Computing the Tax187 Questions
Exam 4: Gross Income: Concepts and Inclusions124 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: in General146 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses95 Questions
Exam 8: Depreciation, cost Recovery, amortization, and Depletion103 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses181 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions105 Questions
Exam 11: Investor Losses111 Questions
Exam 12: Tax Credits and Payments118 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, basis Considerations, and Nontaxable Exchanges280 Questions
Exam 14: Property Transactions, capital Gains and Losses, sec1231, and Recapture Provisions145 Questions
Exam 15: Alternative Minimum Tax132 Questions
Exam 16: Accounting Periods and Methods91 Questions
Exam 17: Corporations: Introduction and Operating Rules112 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation192 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganization72 Questions
Exam 21: Partnerships163 Questions
Exam 22: S Corporations145 Questions
Exam 23: Exempt Entities141 Questions
Exam 24: Multistate Corporate Taxation196 Questions
Exam 25: Taxation of International Transactions164 Questions
Exam 26: Tax Practice and Ethics183 Questions
Exam 27: The Federal Gift and Estate Taxes167 Questions
Exam 28: Income Taxation of Trusts and Estates167 Questions
Select questions type


Micah's beginning capital account on his Schedule K-1 is $60,000.During the year,he is allocated $20,000 of partnership income,$8,000 of nondeductible expenses,and a $12,000 share of tax-exempt income.His Schedule K-1s show allocations of nonrecourse debt of $20,000 (last year) and $30,000 (this year).Micah's ending capital account is $94,000.
(True/False)
4.8/5  (78)
(78) Section 721 provides that,in general,no gain or loss is recognized by the partnership or the partner on contribution of appreciated or depreciated property to a partnership in exchange for an interest in the partnership.
(True/False)
4.9/5 (77)
(77) Allison is a 40% partner in the BAM Partnership.At the beginning of the tax year,Allison's basis in the partnership interest was $100,000,including her share of partnership liabilities.During the current year,BAM reported an ordinary loss of $60,000 (before the following payments to the partners).In addition,BAM made an ordinary distribution of $8,000 to Allison and paid partner Brian a $20,000 consulting fee.At the end of the year,Allison's share of partnership liabilities decreased by $10,000.Assuming loss limitation rules do not apply,Allison's basis in the partnership interest at the end of the year is:
(Multiple Choice)
5.0/5 (82)
(82) Match each of the following statements with the terms below that provide the best definition.
a.Organizational choice of many large accounting firms.
b.Partner's percentage allocation of current operating income.
c.Might affect any two partners' tax liabilities in different ways.
d.Brokerage and registration fees incurred for promoting and marketing partnership interests.
e.Transfer of asset to partnership followed by immediate distribution of cash to partner.
f.Must have at least one general and one limited partner.
g.All partners are jointly and severally liable for entity debts.
h.Theory treating the partner and partnership as separate economic units.
i.Partner's basis in partnership interest after tax-free contribution of asset to partnership.
j.Partnership's basis in asset after tax-free contribution of asset to partnership.
k.Owners are "members."
l.Theory treating the partnership as a collection of taxpayers joined in an agency relationship.
m.Allows many unincorporated entities to select their Federal tax status.
n.No correct match provided.
-Limited liability company
(Short Answer)
4.9/5 (78)
(78) If a partnership earns tax-exempt income,the income should not affect the partners' bases in their partnership interests.Do you agree with this statement? Explain.
(Essay)
4.8/5 (79)
(79) Match each of the following statements with the terms below that provide the best definition.
a.Organizational choice of many large accounting firms.
b.Partner's percentage allocation of current operating income.
c.Might affect any two partners' tax liabilities in different ways.
d.Brokerage and registration fees incurred for promoting and marketing partnership interests.
e.Transfer of asset to partnership followed by immediate distribution of cash to partner.
f.Must have at least one general and one limited partner.
g.All partners are jointly and severally liable for entity debts.
h.Theory treating the partner and partnership as separate economic units.
i.Partner's basis in partnership interest after tax-free contribution of asset to partnership.
j.Partnership's basis in asset after tax-free contribution of asset to partnership.
k.Owners are "members."
l.Theory treating the partnership as a collection of taxpayers joined in an agency relationship.
m.Allows many unincorporated entities to select their Federal tax status.
n.No correct match provided.
-Profits interest
(Short Answer)
4.8/5 (75)
(75) Which of the following is not a correct statement regarding the advantage of the partnership entity form over the C corporation form?
(Multiple Choice)
4.7/5 (80)
(80) A limited partnership (LP) offers all partners protection from claims by the LP's creditors.
(True/False)
4.8/5 (82)
(82) Debt of a limited liability company is allocated among LLC members using the nonrecourse debt allocation rules unless an LLC member has personally guaranteed the debt.
(True/False)
4.9/5 (79)
(79) Match each of the following statements with the terms below that provide the best definition.
Match each of the following statements with the terms below that provide the best definition.
a. Adjusted basis of each partnership asset.
b. Operating expenses incurred after entity is formed but before it begins doing business.
c. Each partner's basis in the partnership.
d. Reconciles book income to "taxable income."
e. Tax accounting election made by partnership.
f. Tax accounting calculation made by partner.
g. Tax accounting election made by partner.
h. Does not include liabilities.
i. Designed to prevent excessive deferral of taxation of partnership income.
j. Amount that may be received by partner for performance of services for the partnership.
k. Theory under which a partnership's recourse debt is shared among the partners.
l. Will eventually be allocated to partner making tax-free property contribution to partnership.
m. Partner's share of partnership items.
n. Must generally be satisfied by any allocation to the partners.
o. Justification for a tax year other than the required taxable year.
p. No correct match is provided.
-Inside basis
(Short Answer)
5.0/5 (88)
(88) Sharon contributed property to the newly formed QRST Partnership.The property had a $100,000 adjusted basis to Sharon and a $160,000 fair market value on the contribution date.The property was also encumbered by a $120,000 nonrecourse debt,which was transferred to the partnership on that date.Another partner,Rochelle,shares 30% of the partnership income,gain,loss,deduction,and credit.Under IRS regulations,Rochelle's share of the nonrecourse debt for basis purposes is:
(Multiple Choice)
4.8/5 (76)
(76) An examination of the RB Partnership's tax books provides the following information for the current year.
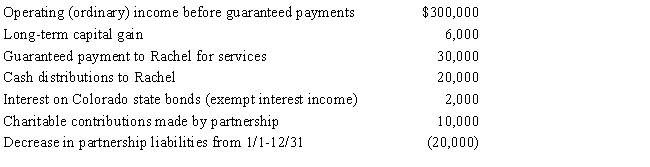 Rachel is a 30% general partner in partnership capital,profits,and losses.Assume the adjusted basis of her partnership interest is $60,000 at the beginning of the year,and she shares in 30% of the partnership's liabilities for basis purposes.
a.What is Rachel's adjusted basis for the partnership interest at the end of the year?
b.How much income must Rachel report on her tax return for the current year? What is the character of the income and what types of tax might apply to it?
Rachel is a 30% general partner in partnership capital,profits,and losses.Assume the adjusted basis of her partnership interest is $60,000 at the beginning of the year,and she shares in 30% of the partnership's liabilities for basis purposes.
a.What is Rachel's adjusted basis for the partnership interest at the end of the year?
b.How much income must Rachel report on her tax return for the current year? What is the character of the income and what types of tax might apply to it? (Essay)
4.8/5 (79)
(79) Which one of the following statements is TRUE regarding a partner's personal liability for partnership assets?
(Multiple Choice)
4.8/5 (85)
(85) Match each of the following statements with the terms below that provide the best definition.
Match each of the following statements with the terms below that provide the best definition.
a. Adjusted basis of each partnership asset.
b. Operating expenses incurred after entity is formed but before it begins doing business.
c. Each partner's basis in the partnership.
d. Reconciles book income to "taxable income."
e. Tax accounting election made by partnership.
f. Tax accounting calculation made by partner.
g. Tax accounting election made by partner.
h. Does not include liabilities.
i. Designed to prevent excessive deferral of taxation of partnership income.
j. Amount that may be received by partner for performance of services for the partnership.
k. Theory under which a partnership's recourse debt is shared among the partners.
l. Will eventually be allocated to partner making tax-free property contribution to partnership.
m. Partner's share of partnership items.
n. Must generally be satisfied by any allocation to the partners.
o. Justification for a tax year other than the required taxable year.
p. No correct match is provided.
-Foreign tax credit vs.deduction
(Short Answer)
4.8/5 (78)
(78) Molly is a 30% partner in the MAP Partnership.During the current tax year,the partnership reported ordinary income of $200,000 before payment of guaranteed payments and distributions to partners.The partnership made an ordinary cash distribution of $20,000 to Molly,and paid guaranteed payments to partners Molly,Amber,and Pat of $20,000 each ($60,000 total guaranteed payments).How much will Molly's adjusted gross income increase as a result of the above items?
(Multiple Choice)
4.9/5 (86)
(86) Match each of the following statements with the terms below that provide the best definition.
a.Organizational choice of many large accounting firms.
b.Partner's percentage allocation of current operating income.
c.Might affect any two partners' tax liabilities in different ways.
d.Brokerage and registration fees incurred for promoting and marketing partnership interests.
e.Transfer of asset to partnership followed by immediate distribution of cash to partner.
f.Must have at least one general and one limited partner.
g.All partners are jointly and severally liable for entity debts.
h.Theory treating the partner and partnership as separate economic units.
i.Partner's basis in partnership interest after tax-free contribution of asset to partnership.
j.Partnership's basis in asset after tax-free contribution of asset to partnership.
k.Owners are "members."
l.Theory treating the partnership as a collection of taxpayers joined in an agency relationship.
m.Allows many unincorporated entities to select their Federal tax status.
n.No correct match provided.
-Substituted
(Short Answer)
4.9/5 (94)
(94) Which of the following statements is always true regarding accounting methods available to a partnership?
(Multiple Choice)
4.8/5 (69)
(69) Xena and Xavier form the XX LLC.Xena contributes cash of $20,000,land (basis = $40,000; fair market value = $25,000),equipment (basis = $0; fair market value = $35,000),and inventory (basis = $30,000; fair market value = $40,000).Xavier contributed $100,000 of cash.How much is the partnership's basis in the land,equipment,and inventory,and how much is Xena's basis in the partnership interest?
(Multiple Choice)
4.9/5 (72)
(72) Samuel is the managing general partner of STU,in which he owns a 25% interest.For the year,STU reported ordinary income of $400,000 (after deducting all guaranteed payments).In addition,the LLC reported interest income of $12,000.Samuel received a guaranteed payment of $120,000 for services he performed for STU.How much income from self-employment did Samuel earn from STU?
(Multiple Choice)
4.7/5 (80)
(80) Laura is a real estate developer and owns property that is treated as inventory (not a capital asset) in her business.She contributes a parcel of this land (basis of $15,000) to a partnership,also to be held as inventory.The fair market value of the property is $12,000 at the contribution date.After three years,the partnership sells the land for $10,000.The partnership will recognize a $5,000 ordinary loss on sale of the property.
(True/False)
4.9/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)