



 Chat with AI
Exam 16: Option Contracts

Exam 1: The Investment Setting72 Questions
Exam 1: The Investment Setting: Part A6 Questions
Exam 2: Asset Allocation and Security Selection77 Questions
Exam 2: Asset Allocation and Security Selection: Part A3 Questions
Exam 3: Organization and Functioning of Securities Markets87 Questions
Exam 4: Security Market Indexes and Index Funds89 Questions
Exam 5: Efficient Capital Markets, Behavioral Finance, and Technical Analysis162 Questions
Exam 6: An Introduction to Portfolio Management114 Questions
Exam 6: An Introduction to Portfolio Management: Part A2 Questions
Exam 6: An Introduction to Portfolio Management: Part B2 Questions
Exam 7: Asset Pricing Models152 Questions
Exam 8: Equity Valuation83 Questions
Exam 9: The Top-Down Approach to Market, Industry, and Company Analysis216 Questions
Exam 10: The Practice of Fundamental Investing60 Questions
Exam 11: Equity Portfolio Management Strategies65 Questions
Exam 12: Bond Fundamentals and Valuation138 Questions
Exam 13: Bond Analysis and Portfolio Management Strategies125 Questions
Exam 14: An Introduction to Derivative Markets and Securities102 Questions
Exam 15: Forward, Futures, and Swap Contracts148 Questions
Exam 16: Option Contracts122 Questions
Exam 17: Professional Money Management, Alternative Assets, and Industry Ethics109 Questions
Exam 18: Evaluation of Portfolio Performance111 Questions
Select questions type


USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
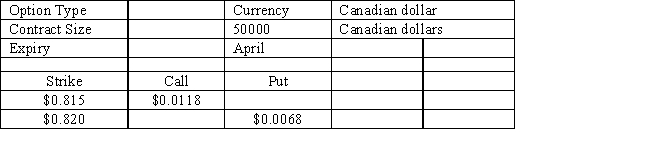 -Refer to Exhibit 16.1. If the spot rate at expiration is $0.75 and the put option was purchased, what is the dollar gain or loss?
 (Multiple Choice)
5.0/5  (89)
(89) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
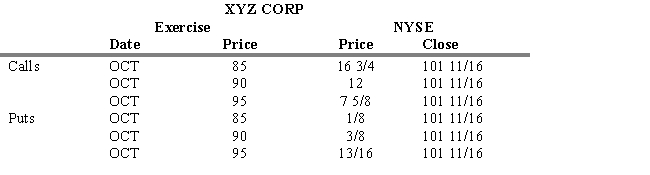 -Refer to Exhibit 16.8. If you establish a long strip using the options with a 90 exercise price, what is your dollar gain or loss if at expiration XYZ is still trading at 101 11/16?
 (Multiple Choice)
4.9/5 (93)
(93) All of the following are normal characteristics of a convertible bond, EXCEPT
(Multiple Choice)
5.0/5 (76)
(76) A price spread (or vertical spread) involves buying and selling an option for the same stock and expiration date but with different exercise prices.
(True/False)
4.8/5 (83)
(83) In the Black-Scholes option pricing model, an increase in security price (S) will cause
(Multiple Choice)
5.0/5 (84)
(84) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
A stock currently trades for $130 per share. Options on the stock are available with a strike price of $125. The options expire in 10 days. The risk-free rate is 3 three over this time period, and the expected volatility is 0.35.
-Refer to Exhibit 16.3. Use the Black-Scholes option pricing model to calculate the price of a call option.
(Multiple Choice)
4.9/5 (82)
(82) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
Consider the following information on put and call options for Citigroup
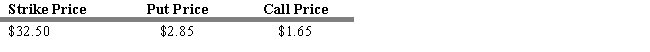 -Refer to Exhibit 16.4. Calculate the net value of a covered call position at a stock price at expiration of $20 and a stock price at expiration of $45.
 (Multiple Choice)
4.9/5 (80)
(80) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
Consider the following information on put and call options for Citigroup
-Refer to Exhibit 16.4. A long straddle is an appropriate strategy if
-Refer to Exhibit 16.4. A long straddle is an appropriate strategy if (Multiple Choice)
4.9/5 (70)
(70) The creation of the CBOE led to all the following innovations in options EXCEPT
(Multiple Choice)
4.8/5 (89)
(89) Credit risk in the options market is only a concern to the option seller.
(True/False)
4.8/5 (93)
(93) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
-Refer to Exhibit 16.8. If you establish a long straddle using the options with a 90 exercise price, what is your dollar gain or loss if at expiration XYZ is still trading at 101 11/16?
-Refer to Exhibit 16.8. If you establish a long straddle using the options with a 90 exercise price, what is your dollar gain or loss if at expiration XYZ is still trading at 101 11/16? (Multiple Choice)
4.9/5 (81)
(81) Assume that you have just sold a stock for a loss at a price of $75 for tax purposes. You still wish to maintain exposure to the sold stock. Suppose that you buy a call with a strike price of $70 and a price of $6.75. Calculate the effective price paid to repurchase the stock if the price after 35 days is $80.
(Multiple Choice)
4.8/5 (77)
(77) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
The following information is provided in the context of a two-period (two six-month periods) binomial option pricing model. A stock currently trades at $60 per share, and a call option on the stock has an exercise price of $65. The stock is equally likely to rise by 15 percent or fall by 15 percent during each six-month period. The one-year risk free rate is 3 percent.
-Refer to Exhibit 16.2. Calculate the price of the call option after the stock price has already moved down in value once (Cd).
(Multiple Choice)
5.0/5 (93)
(93) The common stock of BioTech Industries pays a dividend of $1 per share and has a current market price of $27 per share. The convertible bond is selling for $1100. The payback or breakeven time for the bond is
(Multiple Choice)
4.7/5 (78)
(78) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
A stock currently trades for $130 per share. Options on the stock are available with a strike price of $125. The options expire in 10 days. The risk-free rate is 3 three over this time period, and the expected volatility is 0.35.
-Refer to Exhibit 16.3. Calculate the price of the put option.
(Multiple Choice)
4.9/5 (82)
(82) The payment of any compensation for loss is contingent on the actual occurrence of a credit-related event under a
(Multiple Choice)
4.9/5 (89)
(89) The standardization of option contracts and the creation of the Options Clearing Corporation are two important results of the opening of the Chicago Board of Options Exchange.
(True/False)
4.9/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)