



 Chat with AI
Exam 13: Bond Analysis and Portfolio Management Strategies

Exam 1: The Investment Setting72 Questions
Exam 1: The Investment Setting: Part A6 Questions
Exam 2: Asset Allocation and Security Selection77 Questions
Exam 2: Asset Allocation and Security Selection: Part A3 Questions
Exam 3: Organization and Functioning of Securities Markets87 Questions
Exam 4: Security Market Indexes and Index Funds89 Questions
Exam 5: Efficient Capital Markets, Behavioral Finance, and Technical Analysis162 Questions
Exam 6: An Introduction to Portfolio Management114 Questions
Exam 6: An Introduction to Portfolio Management: Part A2 Questions
Exam 6: An Introduction to Portfolio Management: Part B2 Questions
Exam 7: Asset Pricing Models152 Questions
Exam 8: Equity Valuation83 Questions
Exam 9: The Top-Down Approach to Market, Industry, and Company Analysis216 Questions
Exam 10: The Practice of Fundamental Investing60 Questions
Exam 11: Equity Portfolio Management Strategies65 Questions
Exam 12: Bond Fundamentals and Valuation138 Questions
Exam 13: Bond Analysis and Portfolio Management Strategies125 Questions
Exam 14: An Introduction to Derivative Markets and Securities102 Questions
Exam 15: Forward, Futures, and Swap Contracts148 Questions
Exam 16: Option Contracts122 Questions
Exam 17: Professional Money Management, Alternative Assets, and Industry Ethics109 Questions
Exam 18: Evaluation of Portfolio Performance111 Questions
Select questions type


USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
Talmart Corporation bonds have a $1,000 face value and will mature in four years. The bonds have a 7 percent coupon rate. Interest is paid annually, and the required rate of return is 6 percent for these bonds.
-Refer to Exhibit 13.2. What is the Macaulay duration of the Talmart corporate bonds?
(Multiple Choice)
4.8/5  (94)
(94) Investment horizon is the future time when an investor must begin an investment program to generate the required funds for a future liability.
(True/False)
4.8/5 (79)
(79) Which duration is computed by discounting flows using the yield to maturity of the bond?
(Multiple Choice)
4.8/5 (79)
(79) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
You are creating a portfolio that consists of the following two bonds. Bond A pays an annual 7 percent coupon, matures in two years, has a yield to maturity of 8 percent, and a face value of $1,000. Bond B pays an annual 8 percent coupon, matures in three years, has a yield to maturity of 9 percent, and a face value of $1,000.
-Refer to Exhibit 13.14. Calculate the Modified Duration for Bond A.
(Multiple Choice)
4.7/5 (72)
(72) The investment style of a bond portfolio can be summarized by its two most important characteristics: credit quality and interest rate sensitivity.
(True/False)
5.0/5 (70)
(70) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
The following information is given concerning a substitution swap. You currently hold a 15-year, 7 percent coupon bond priced to yield 8 percent. As a swap candidate you are considering a 15-year, 7 percent coupon bond priced to yield 8.5 percent. Assume a reinvestment rate of 8.5 percent, semiannual compounding, and a one-year workout period.
 -Refer to Exhibit 13.5. The dollar investment in the candidate bond is
 (Multiple Choice)
4.8/5 (77)
(77) A portfolio manager that attempts to select bonds based on their intrinsic value would be carrying out
(Multiple Choice)
4.8/5 (73)
(73) Indexing is an active portfolio management strategy that seeks to copy the composition and performance of a selected market index.
(True/False)
4.7/5 (73)
(73) When applying active management techniques to a global portfolio, the additional concern is an expectation regarding exchange rates between countries.
(True/False)
4.8/5 (70)
(70) The option adjusted duration will approach the duration to maturity, when
(Multiple Choice)
5.0/5 (79)
(79) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
The following information is given concerning a pure yield pick-up swap: You currently hold a 10-year, 7 percent coupon bond priced to yield 8 percent. As a swap candidate, you are considering a 10-year, 8 percent coupon bond priced to yield 9 percent. Assume a reinvestment at 9 percent, semiannual compounding, and a one-year workout period.
 -Refer to Exhibit 13.4. The interest on one coupon for the candidate bond is
 (Multiple Choice)
4.9/5 (97)
(97) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
The following information is given concerning a pure yield pick-up swap: You currently hold a 20-year, Aa 8 percent coupon bond priced to yield 10 percent. As a swap candidate you are considering a 20-year, Aa 10 percent coupon bond priced to yield 10.75 percent. Assume a reinvestment rate of 12.00 percent, semiannual compounding, and a one-year workout period.
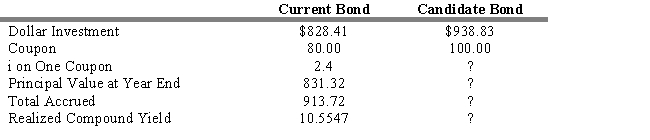 -Refer to Exhibit 13.6. The value of the swap is ____ basis points in one year.
 (Multiple Choice)
5.0/5 (83)
(83) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
The following information is given concerning a substitution swap. You currently hold a 25-year, Aa 10-percent coupon bond priced to yield 12 percent. As a swap candidate, you are considering a 25-year, Aa 10 percent coupon bond priced to yield 13 percent. Assume a reinvestment rate of 12 percent, semiannual compounding, and a one-year workout period.
 -Refer to Exhibit 13.9. The value of the swap is ____ basis points in one year.
 (Multiple Choice)
4.9/5 (72)
(72) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
The following information is given concerning a substitution swap. You currently hold a 25-year, Aa 10-percent coupon bond priced to yield 12 percent. As a swap candidate, you are considering a 25-year, Aa 10 percent coupon bond priced to yield 13 percent. Assume a reinvestment rate of 12 percent, semiannual compounding, and a one-year workout period.
-Refer to Exhibit 13.9. The realized compound yield on the current bond is
-Refer to Exhibit 13.9. The realized compound yield on the current bond is (Multiple Choice)
4.9/5 (88)
(88) If you expected interest rates to fall, you would prefer to own bonds with
(Multiple Choice)
4.7/5 (62)
(62) Assuming no change in interest rates, the duration of a coupon bond
(Multiple Choice)
4.9/5 (71)
(71) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
A $1000 par value bond with five years to maturity and a 6 percent coupon has a yield to maturity of 8 percent. Interest is paid semiannually.
-Refer to Exhibit 13.1. Calculate the Macaulay duration for the bond.
(Multiple Choice)
4.8/5 (77)
(77) A bond portfolio is immunized from interest rate risk if the modified duration of the portfolio is always equal to the desired investment horizon.
(True/False)
4.9/5 (82)
(82) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
Consider two bonds: both pay semiannual interest. Bond X has a coupon of 7 percent per year, maturity of 20 years, yield to maturity of 8 percent per year, and a face value of $1000. Bond Y has a coupon of 7 percent per year, maturity of 20 years, yield to maturity of 8.5 percent per year, and a face value of $1000.
-Refer to Exhibit 13.11. Calculate the percentage gain per invested dollar for Bond X assuming a one-year horizon and a reinvestment rate of 8 percent per year.
(Multiple Choice)
4.8/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)