



 Chat with AI
Exam 6: An Introduction to Portfolio Management

Exam 1: The Investment Setting72 Questions
Exam 1: The Investment Setting: Part A6 Questions
Exam 2: Asset Allocation and Security Selection77 Questions
Exam 2: Asset Allocation and Security Selection: Part A3 Questions
Exam 3: Organization and Functioning of Securities Markets87 Questions
Exam 4: Security Market Indexes and Index Funds89 Questions
Exam 5: Efficient Capital Markets, Behavioral Finance, and Technical Analysis162 Questions
Exam 6: An Introduction to Portfolio Management114 Questions
Exam 6: An Introduction to Portfolio Management: Part A2 Questions
Exam 6: An Introduction to Portfolio Management: Part B2 Questions
Exam 7: Asset Pricing Models152 Questions
Exam 8: Equity Valuation83 Questions
Exam 9: The Top-Down Approach to Market, Industry, and Company Analysis216 Questions
Exam 10: The Practice of Fundamental Investing60 Questions
Exam 11: Equity Portfolio Management Strategies65 Questions
Exam 12: Bond Fundamentals and Valuation138 Questions
Exam 13: Bond Analysis and Portfolio Management Strategies125 Questions
Exam 14: An Introduction to Derivative Markets and Securities102 Questions
Exam 15: Forward, Futures, and Swap Contracts148 Questions
Exam 16: Option Contracts122 Questions
Exam 17: Professional Money Management, Alternative Assets, and Industry Ethics109 Questions
Exam 18: Evaluation of Portfolio Performance111 Questions
Select questions type


USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
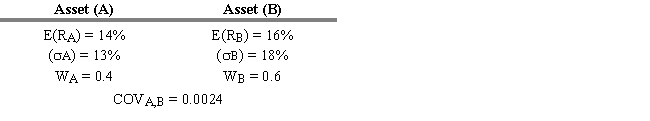 -Refer to Exhibit 6.15. What is the expected return of a portfolio of two risky assets if the expected return E(Ri), standard deviation ( i), covariance (COVi,j), and asset weight (Wi) are as shown above?
 (Multiple Choice)
4.8/5  (71)
(71) The Markowitz model is based on several assumptions regarding investor behavior. Which of the following is NOT such any assumption?
(Multiple Choice)
4.8/5 (87)
(87) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
Stocks A and B have a correlation coefficient of -0.8. The stocks' expected returns and standard deviations are in the table below. A portfolio consisting of 40% of stock A and 60% of stock B is constructed.
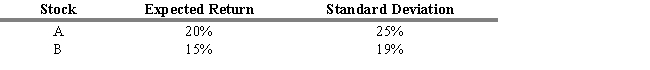 -Refer to Exhibit 6.14. What percentage of stock A should be invested to obtain the minimum risk portfolio that contains stock A and B?
 (Multiple Choice)
4.7/5 (90)
(90) In a three-asset portfolio, the standard deviation of the portfolio is one-third of the square root of the sum of the individual standard deviations.
(True/False)
4.8/5 (94)
(94) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
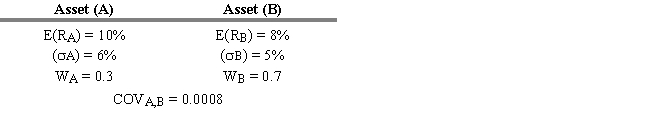 -Refer to Exhibit 6.4. What is the standard deviation of this portfolio?
 (Multiple Choice)
4.9/5 (79)
(79) The portfolios on the capital market line are combinations of the risk-free asset and the market portfolio.
(True/False)
4.8/5 (92)
(92) What is the expected return of the three-stock portfolio described below? 
(Multiple Choice)
4.9/5 (71)
(71) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
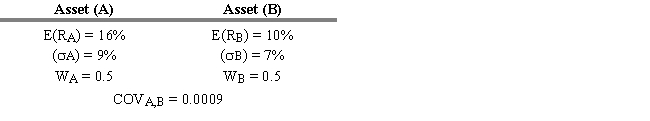 -Refer to Exhibit 6.6. What is the standard deviation of this portfolio?
 (Multiple Choice)
4.9/5 (75)
(75) The capital market line is the tangent line between the risk-free rate of return and the efficient frontier.
(True/False)
4.9/5 (74)
(74) Which of the following statements about the correlation coefficient is FALSE?
(Multiple Choice)
4.8/5 (66)
(66) In a two-stock portfolio, if the correlation coefficient between two stocks were to decrease over time, everything else remaining constant, the portfolio's risk would
(Multiple Choice)
4.8/5 (98)
(98) What is the expected return of the three-stock portfolio described below? 
(Multiple Choice)
5.0/5 (84)
(84) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
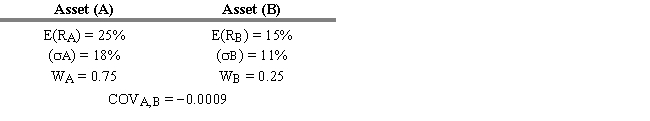 -Refer to Exhibit 6.2. What is the standard deviation of this portfolio?
 (Multiple Choice)
4.8/5 (77)
(77) The correlation coefficient between the market return and a risk-free asset would
(Multiple Choice)
4.9/5 (83)
(83) A completely diversified portfolio would have a correlation with the market portfolio that is
(Multiple Choice)
4.9/5 (81)
(81) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
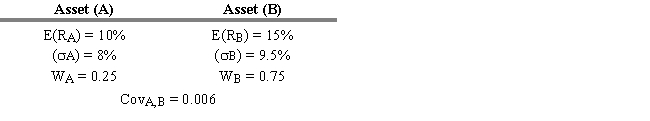 -Refer to Exhibit 6.1. What is the expected return of a portfolio of two risky assets if the expected return E(Ri), standard deviation ( i), covariance (COVi,j), and asset weight (Wi) are as shown above?
 (Multiple Choice)
4.9/5 (68)
(68) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
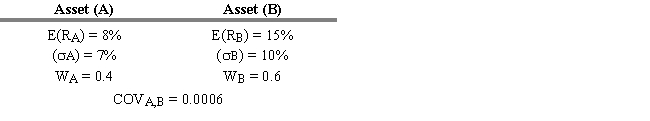 -Refer to Exhibit 6.5. What is the expected return of a portfolio of two risky assets if the expected return E(Ri), standard deviation ( i), covariance (COVi,j), and asset weight (Wi) are as shown above?
 (Multiple Choice)
4.8/5 (65)
(65) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)