



 Chat with AI
Exam 23: Transfer Pricing and Multinational Management Control Systems

Exam 1: The Accountants Vital Role in Decision Making141 Questions
Exam 2: An Introduction to Cost Terms and Purposes165 Questions
Exam 3: Cost-Volume-Profit Analysis139 Questions
Exam 4: Job Costing138 Questions
Exam 5: Activity-Based Costing and Management133 Questions
Exam 6: Master Budget and Responsibility Accounting150 Questions
Exam 7: Flexible Budgets, Variances, and Management Control: I146 Questions
Exam 8: Flexible Budgets, Variances, and Management Control: II137 Questions
Exam 9: Income Effects of Denominator Level on Inventory Valuation154 Questions
Exam 10: Quantitative Analyses of Cost Functions114 Questions
Exam 11: Decision Making and Relevant Information146 Questions
Exam 12: Pricing Decisions, Product Profitability Decisions, and Cost Management135 Questions
Exam 13: Strategy, Balanced Scorecard, and Profitability Analysis140 Questions
Exam 14: Period Cost Allocation153 Questions
Exam 15: Cost Allocation: Joint Products and Byproducts149 Questions
Exam 16: Revenue and Customer Profitability Analysis137 Questions
Exam 17: Process Costing128 Questions
Exam 18: Spoilage, Rework, and Scrap121 Questions
Exam 19: Cost Management: Quality, Time, and the Theory of Constraints158 Questions
Exam 20: Inventory Cost Management Strategies136 Questions
Exam 21: Capital Budgeting: Methods of Investment Analysis128 Questions
Exam 22: Capital Budgeting: a Closer Look120 Questions
Exam 23: Transfer Pricing and Multinational Management Control Systems141 Questions
Exam 24: Multinational Performance Measurement and Compensation139 Questions
Select questions type


A company has two divisions. The Bottle Division produces products that have variable costs of $3 per unit. For the current year, sales were 150,000 to outsiders at $5 per unit and 40,000 units to the Mixing Division at 140 percent of variable costs. Under a dual transfer pricing system, the Mixing Division pays only the variable cost per unit. The fixed costs of Bottle Division were $125,000 per year.
Mixing sells its finished products to outside customers for $11.50 per unit. Mixing has variable costs of $2.50 per unit in addition to the costs from Bottle. The annual fixed costs of Mixing were $85,000. There were no beginning or ending inventories during the year.
Required:
What are the operating incomes of the two divisions and the company as a whole for the year? Explain why the company operating income is less than the sum of the two divisions' total income.
(Essay)
4.8/5  (82)
(82) The Surrey Division of Columbia Ltd. has approached the Burnaby Division and requested that it supply 25,000 units of the component at a transfer price of $150. Assuming Burnaby Division has idle capacity, what is the minimum transfer price the Burnaby Division should agree to accept?
(Multiple Choice)
4.7/5 (89)
(89) Answer the following question(s) using the information below.
Cool Air Ltd. manufactures only one type of air conditioner and has two divisions, the Compressor Division, and the Assembly Division. The Compressor Division manufactures compressors for the Assembly Division, which completes the air conditioner and sells it to retailers. The Compressor Division "sells" compressors to the Assembly Division. The market price for the Assembly Division to purchase a compressor is $77. (Ignore changes in inventory.) The fixed costs for the Compressor Division are assumed to be the same over the range of 5,000-10,000 units. The fixed costs for the Assembly Division are assumed to be $15.00 per unit at 10,000 units.
Compressor's costs per compressor are:
 Assembly's costs per completed air conditioner are:
 -What is the transfer price per compressor from the Compressor Division to the Assembly Division if the method used to place a value on each compressor is 150% of variable costs?
Assembly's costs per completed air conditioner are:
-What is the transfer price per compressor from the Compressor Division to the Assembly Division if the method used to place a value on each compressor is 150% of variable costs? (Multiple Choice)
4.8/5 (86)
(86) A management control system is a means of gathering and using information to aid and coordinate the process of making planning and control decisions throughout the organization, and to guide employee behaviour.
(True/False)
4.9/5 (93)
(93) Use the information below to answer the following question(s).
Blackoil Corp. has two divisions, Refining and Production. The company's primary product is Clean Oil. Each division's costs are provided below:
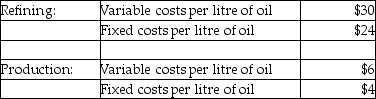 The Production Division is able to sell the oil to other areas for $24 per litre. The Refining Division has been operating at a capacity of 80,000 litres a day, using oil from the Production Division and oil purchased from other suppliers. The Refining Division usually purchases 50,000 litres of oil, on average, from the Production Division and 30,000 litres, on average, from other suppliers at $40/litre.
-Division A sells soybean paste internally to Division B, which, in turn, produces soybean burgers that sell for $5 per kilogram. Division A incurs costs of $0.75 per kilogram, while Division B incurs additional costs of $2.50 per kilogram. Which of the following formulas correctly reflects the company's operating income per kilogram?
The Production Division is able to sell the oil to other areas for $24 per litre. The Refining Division has been operating at a capacity of 80,000 litres a day, using oil from the Production Division and oil purchased from other suppliers. The Refining Division usually purchases 50,000 litres of oil, on average, from the Production Division and 30,000 litres, on average, from other suppliers at $40/litre.
-Division A sells soybean paste internally to Division B, which, in turn, produces soybean burgers that sell for $5 per kilogram. Division A incurs costs of $0.75 per kilogram, while Division B incurs additional costs of $2.50 per kilogram. Which of the following formulas correctly reflects the company's operating income per kilogram? (Multiple Choice)
4.9/5 (85)
(85) Answer the following question(s) using the information below.
Cool Air Ltd. manufactures only one type of air conditioner and has two divisions, the Compressor Division, and the Assembly Division. The Compressor Division manufactures compressors for the Assembly Division, which completes the air conditioner and sells it to retailers. The Compressor Division "sells" compressors to the Assembly Division. The market price for the Assembly Division to purchase a compressor is $77. (Ignore changes in inventory.) The fixed costs for the Compressor Division are assumed to be the same over the range of 5,000-10,000 units. The fixed costs for the Assembly Division are assumed to be $15.00 per unit at 10,000 units.
Compressor's costs per compressor are:
Assembly's costs per completed air conditioner are:
-What is the transfer price per compressor from the Compressor Division to the Assembly Division if the transfer price per compressor is 110% of full costs?
Assembly's costs per completed air conditioner are:
-What is the transfer price per compressor from the Compressor Division to the Assembly Division if the transfer price per compressor is 110% of full costs? (Multiple Choice)
4.8/5 (68)
(68) When companies are unable to choose a transfer-pricing method which meets their requirements, they may use
(Multiple Choice)
4.8/5 (85)
(85) The choice of a transfer-pricing method has minimal effect on the allocation of company-wide operating income among divisions.
(True/False)
4.7/5 (89)
(89) Full-cost transfer pricing may be used because it yields relevant costs for short-run decisions even though full-cost allocations may lead to poor long-run decisions.
(True/False)
4.9/5 (81)
(81) Centralia Components Ltd. manufactures cable assemblies used in transportation, recreational products and medical industries in its Assemblies Division. The capacity of the Assemblies Division is currently 200,000 units and it sells 160,000 units to the outside market at an average price of $96/unit. Cost to manufacture the cable assemblies are $42 variable and $8 fixed. Fixed costs per unit are based on its normal volume of 160,000 units.
Centralia's Mobility Division uses cable assemblies in the manufacture of wheelchairs. It has offered to buy 25,000 units from the Assemblies Division at $48 per unit. Calculate the operating income of the Assemblies Division with and without the offer from the Mobility Division. Should Assemblies accept the offer?
(Essay)
4.8/5 (79)
(79) Answer the following question(s) using the information below.
Cool Air Ltd. manufactures only one type of air conditioner and has two divisions, the Compressor Division, and the Assembly Division. The Compressor Division manufactures compressors for the Assembly Division, which completes the air conditioner and sells it to retailers. The Compressor Division "sells" compressors to the Assembly Division. The market price for the Assembly Division to purchase a compressor is $77. (Ignore changes in inventory.) The fixed costs for the Compressor Division are assumed to be the same over the range of 5,000-10,000 units. The fixed costs for the Assembly Division are assumed to be $15.00 per unit at 10,000 units.
Compressor's costs per compressor are:
Assembly's costs per completed air conditioner are:
-Assume the transfer price for a compressor is 150% of total costs of the Compressor Division and 1,000 of the compressors are produced and transferred to the Assembly Division. The Compressor Division's operating income is:
Assembly's costs per completed air conditioner are:
-Assume the transfer price for a compressor is 150% of total costs of the Compressor Division and 1,000 of the compressors are produced and transferred to the Assembly Division. The Compressor Division's operating income is: (Multiple Choice)
4.9/5 (78)
(78) Answer the following question(s) using the information below:
Greenlawn Ltd. has two divisions, Distribution and Production. The company's primary product is fertilizer. Each division's costs are provided below:
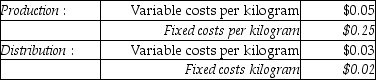 The Distribution Division has been operating at a capacity of 4,000,000 kilograms a week and usually purchases 2,000,000 kilograms from the Production Division and 2,000,000 kilograms from other suppliers at $0.45 per kilogram.
-What is the transfer price per kilogram from the Production Division to the Distribution Division, assuming the method used to place a value on each kilogram of fertilizer is 160% of variable costs?
The Distribution Division has been operating at a capacity of 4,000,000 kilograms a week and usually purchases 2,000,000 kilograms from the Production Division and 2,000,000 kilograms from other suppliers at $0.45 per kilogram.
-What is the transfer price per kilogram from the Production Division to the Distribution Division, assuming the method used to place a value on each kilogram of fertilizer is 160% of variable costs? (Multiple Choice)
4.8/5 (63)
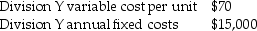
(63) Mar Company has two decentralized divisions, X and Y. Division X has been purchasing certain component parts from Division Y at $75 per unit. Because Division Y plans to raise the price to $100 per unit, Division X desires to purchase these parts from external suppliers for $75 per unit. The following information is available:
 Division Y annual production
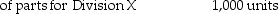 If Division X buys from an external supplier, the facilities Division Y uses to manufacture these parts will be idle. Assuming Division Y's fixed costs cannot be avoided, what is the result if Mar requires Division X to buy from Division Y at a transfer price of $100 per unit?
Division Y annual production
If Division X buys from an external supplier, the facilities Division Y uses to manufacture these parts will be idle. Assuming Division Y's fixed costs cannot be avoided, what is the result if Mar requires Division X to buy from Division Y at a transfer price of $100 per unit? (Essay)
4.9/5 (81)
(81) A benefit of decentralization should be increased motivation of subunit managers.
(True/False)
4.8/5 (86)
(86) All of the following criteria may be used to choose a transfer-pricing method EXCEPT
(Multiple Choice)
4.8/5 (88)
(88) Under distress pricing conditions, long run average prices may be used in setting transfer prices. Such actions negatively affect the supplying division.
(True/False)
4.8/5 (78)
(78) Answer the following question(s) using the information below.
Beta Shoe Ltd. manufactures only one type of shoe and has two divisions, the Sole Division, and the Assembly Division. The Sole Division manufactures soles for the Assembly Division, which completes the shoe and sells it to retailers. The Sole Division "sells" soles to the Assembly Division. The market price for the Assembly Division to purchase a pair of soles is $20. (Ignore changes in inventory.) The fixed costs for the Sole Division are assumed to be the same over the range of 40,000-100,000 units. The fixed costs for the Assembly Division are assumed to be $7 per pair at 100,000 units.
Sole's costs per pair of soles are:
 Assembly's costs per completed pair of shoes are:
 -What is the market-based transfer price per pair of soles from the Sole Division to the Assembly Division?
Assembly's costs per completed pair of shoes are:
-What is the market-based transfer price per pair of soles from the Sole Division to the Assembly Division? (Multiple Choice)
4.8/5 (77)
(77) The costs used in cost-based transfer prices can only be actual costs.
(True/False)
4.9/5 (76)
(76) For each of the following transfer price descriptions or operating situations, tell which of the general methods of transfer pricing it is probably categorized as:
a. Bargaining between selling and buying units.
b. Budgeted costs.
c. 145% of full costs.
d. Internal product transfers are required if goods are available internally.
e. Manufacturing plus marketing plus distribution plus customer service costs.
f. Prices listed in a trade journal.
g. Selling price less normal sales commissions.
h. Variable manufacturing cost plus a mark-up.
(Essay)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)