



 Chat with AI
Exam 8: Flexible Budgets, Variances, and Management Control: II

Exam 1: The Accountants Vital Role in Decision Making141 Questions
Exam 2: An Introduction to Cost Terms and Purposes165 Questions
Exam 3: Cost-Volume-Profit Analysis139 Questions
Exam 4: Job Costing138 Questions
Exam 5: Activity-Based Costing and Management133 Questions
Exam 6: Master Budget and Responsibility Accounting150 Questions
Exam 7: Flexible Budgets, Variances, and Management Control: I146 Questions
Exam 8: Flexible Budgets, Variances, and Management Control: II137 Questions
Exam 9: Income Effects of Denominator Level on Inventory Valuation154 Questions
Exam 10: Quantitative Analyses of Cost Functions114 Questions
Exam 11: Decision Making and Relevant Information146 Questions
Exam 12: Pricing Decisions, Product Profitability Decisions, and Cost Management135 Questions
Exam 13: Strategy, Balanced Scorecard, and Profitability Analysis140 Questions
Exam 14: Period Cost Allocation153 Questions
Exam 15: Cost Allocation: Joint Products and Byproducts149 Questions
Exam 16: Revenue and Customer Profitability Analysis137 Questions
Exam 17: Process Costing128 Questions
Exam 18: Spoilage, Rework, and Scrap121 Questions
Exam 19: Cost Management: Quality, Time, and the Theory of Constraints158 Questions
Exam 20: Inventory Cost Management Strategies136 Questions
Exam 21: Capital Budgeting: Methods of Investment Analysis128 Questions
Exam 22: Capital Budgeting: a Closer Look120 Questions
Exam 23: Transfer Pricing and Multinational Management Control Systems141 Questions
Exam 24: Multinational Performance Measurement and Compensation139 Questions
Select questions type


Even where separate variable and fixed manufacturing overhead control accounts are used for job costing, it is not necessary to have separate overhead allocated accounts.
(True/False)
4.8/5  (94)
(94) What are the arguments for prorating a production-volume variance that has been deemed to be material among work-in-process, finished goods, and cost of goods sold, as opposed to writing it all off to cost of goods sold?
(Essay)
4.8/5 (83)
(83) Casey Corporation produces a special line of basketball hoops in batches. To manufacture a batch of the basketball hoops Casey Corporation must setup the machines and moulds. Setup costs are batch-level costs because they are associated with batches rather than individual units of products. A separate Setup Department is responsible for setting up machines and moulds for different styles of basketball hoops.
Setup overhead costs consist of some costs that are variable and some costs that are fixed with
respect to the number of setup hours. The following information pertains to January 2012.
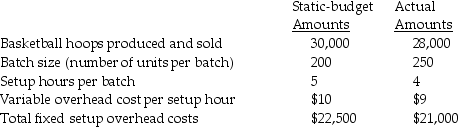 Required:
a. Calculate the efficiency variance for variable setup overhead costs.
b. Calculate the rate variance for variable setup overhead costs.
c. Calculate the flexible-budget variance for variable setup overhead costs.
d. Calculate the rate variance for fixed setup overhead costs.
e. Calculate the production-volume variance for fixed setup overhead costs.
Required:
a. Calculate the efficiency variance for variable setup overhead costs.
b. Calculate the rate variance for variable setup overhead costs.
c. Calculate the flexible-budget variance for variable setup overhead costs.
d. Calculate the rate variance for fixed setup overhead costs.
e. Calculate the production-volume variance for fixed setup overhead costs. (Essay)
4.7/5 (85)
(85) Brown Dental Equipment uses a flexible budget for its indirect manufacturing costs. For 2012 the company anticipated that it would produce 36,000 components with 7,000 machine hours and 14,400 employee days. The costs and cost drivers were to be as follows:
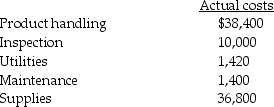
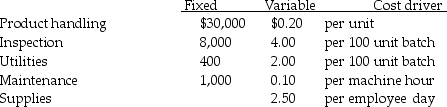 During the year the company processed 40,000 units, worked 15,000 employee days, and had 8,000 machine hours. The actual costs for 2012 were:
 Required:
a. Prepare an overhead static budget for 2012 with variances.
b. Prepare an overhead flexible budget for 2012 with variances.
During the year the company processed 40,000 units, worked 15,000 employee days, and had 8,000 machine hours. The actual costs for 2012 were:
Required:
a. Prepare an overhead static budget for 2012 with variances.
b. Prepare an overhead flexible budget for 2012 with variances. (Essay)
4.7/5 (84)
(84) Answer the following question(s) using the information below.
Jenny's Corporation manufactured 25,000 grooming kits for horses during March. The fixed-overhead cost allocation rate is $20.00 per machine-hour. The following fixed overhead data pertain to March:
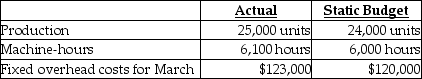 -What is the amount of fixed overhead allocated to production?
 (Multiple Choice)
4.8/5 (75)
(75) Answer the following question(s) using the information below.
Munoz Inc. produces a special line of plastic toy racing cars in batches. To manufacture a batch of the cars Munoz Inc. must setup the machines and molds. Setup costs are batch-level costs because they are associated with batches rather than individual units of products. A separate Setup Department is responsible for setting up machines and molds for different styles of car.
Setup overhead costs consist of some costs that are variable and some costs that are fixed with respect to the number of setup hours. The following information pertains to June 2012:
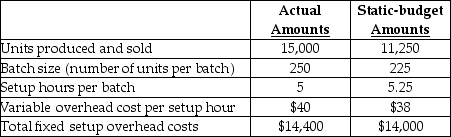 -Calculate the efficiency variance for variable setup overhead costs.
 (Multiple Choice)
4.9/5 (88)
(88) What is the variable manufacturing overhead static-budget variance given the following information? 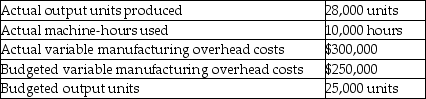
(Multiple Choice)
4.8/5 (86)
(86) Johnston Equipment develops food processing equipment. The budgeted fixed overhead costs for 2012 total $768,000. The company uses direct labour-hours for fixed overhead allocation and anticipates 480,000 hours during the year for 960,000 units. An equal number of units are budgeted for each month.
During April 84,000 packages (units) were produced and $66,000 was spent on fixed overhead.
Required:
a. Determine the fixed overhead rate for 2012 based on direct labour-hours.
b. Determine the fixed overhead static-budget variance for April.
c. Determine the production-volume overhead variance for April.
(Essay)
4.9/5 (77)
(77) When machine-hours are used as a cost allocation base, the item MOST likely to contribute to a favourable production-volume variance is
(Multiple Choice)
4.9/5 (64)
(64) Heather's Pillow Company manufactures pillows. The 2012 operating budget is based on production of 20,000 pillows with 0.5 machine-hour allowed per pillow. Variable manufacturing overhead is anticipated to be $220,000.
Actual production for 2012 was 18,000 pillows using 9,500 machine-hours.
Actual variable costs were $20 per machine-hour.
Required:
Calculate the variable overhead rate and efficiency variances.
(Essay)
4.8/5 (74)
(74) Teri's Furniture uses variance analysis to evaluate manufacturing overhead in its' table factory. The information for the May overhead expenditures is as follows:
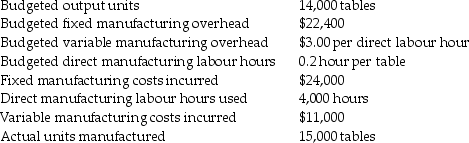 Required:
a. Calculate the variable manufacturing overhead rate and efficiency variances; and, the fixed manufacturing overhead rate and production-volume variances for the plant controller.
b. Prepare all necessary journal entries to record the actual costs, allocated costs, and variances. Keep variable and fixed entries separate.
Required:
a. Calculate the variable manufacturing overhead rate and efficiency variances; and, the fixed manufacturing overhead rate and production-volume variances for the plant controller.
b. Prepare all necessary journal entries to record the actual costs, allocated costs, and variances. Keep variable and fixed entries separate. (Essay)
4.8/5 (83)
(83) Two of the primary ways to manage variable-overhead costs include
(Multiple Choice)
4.9/5 (81)
(81) One of the primary differences between overhead costs in non-manufacturing settings and manufacturing settings is
(Multiple Choice)
4.9/5 (78)
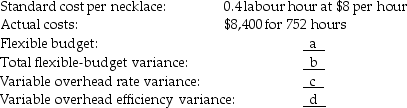
(78) Zebra Jewellers manufactured 2,000 necklaces during March with a total overhead budget of $49,600. However, while manufacturing the 2,000th necklace the microcomputer that contained the month's cost information broke down. With the computer out of commission, the accountant has been unable to complete the variance analysis report. The missing information of the report is lettered in the following set of data:
Variable overhead:
 Fixed overhead:
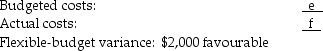 Required:
Compute the missing elements in the report represented by the lettered items.
Fixed overhead:
Required:
Compute the missing elements in the report represented by the lettered items. (Essay)
4.9/5 (81)
(81) Fixed and variable cost variances can ________ be applied to activity-based costing systems.
(Multiple Choice)
4.9/5 (65)
(65) Mostly Miniatures has just implemented a new cost accounting system that provides two variances for fixed manufacturing overhead. While the company's managers are familiar with the concept of static-budget variance, they are unclear as to how to interpret the production-volume overhead variances. Currently the company has a production capacity of 54,000 miniatures a month although it generally produces only 46,000 cases. However, in any given month the actual production is probably something other than 46,000.
Required:
a. Does the production-volume overhead variance measure the difference between the 54,000 and 46,000, or the difference between the 46,000 and the actual monthly production? Explain.
b. What advice can you provide the managers that will help them interpret the production-volume overhead variances?
(Essay)
4.8/5 (79)
(79) A leased factory building has a fixed monthly rental payment, and a variable overhead cost of energy and indirect labour. Which of the following is TRUE, assuming that all activity levels are within the relevant range?
(Multiple Choice)
4.8/5 (67)
(67) Fixed Manufacturing Overhead Variances that are material should only be written off to Cost of Goods Sold.
(True/False)
4.9/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)