



 Chat with AI
Exam 15: Property Transactions: Nontaxable Exchanges

Exam 1: An Introduction to Taxation and Understanding Federal Tax Law194 Questions
Exam 2: Working With the Tax Law86 Questions
Exam 3: Tax Formula and Tax Determination; an Overview of Property Transactions187 Questions
Exam 4: Gross Income: Concepts and Inclusions124 Questions
Exam 5: Gross Income: Exclusions114 Questions
Exam 6: Deductions and Losses: in General155 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses124 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion103 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses178 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses111 Questions
Exam 12: Alternative Minimum Tax134 Questions
Exam 13: Tax Credits and Payment Procedures120 Questions
Exam 14: Property Transactions: Determination of Gain or Loss and Basis Considerations148 Questions
Exam 15: Property Transactions: Nontaxable Exchanges138 Questions
Exam 16: Property Transactions: Capital Gains and Losses78 Questions
Exam 17: Property Transactions: 1231 and Recapture Provisions74 Questions
Exam 18: Accounting Periods and Methods110 Questions
Exam 19: Deferred Compensation101 Questions
Exam 20: Corporations and Partnerships198 Questions
Select questions type


An office building with an adjusted basis of $320,000 was destroyed by fire on December 30, 2017. On January 11, 2018, the insurance company paid the owner $450,000. The fair market value of the building was $500,000, but under the co-insurance clause, the insurance company is responsible for only 90 percent of the loss. The owner reinvested $410,000 in a new office building on February 12, 2018, that was smaller than the original office building. What is the recognized gain and the basis of the new building if § 1033 (nonrecognition of gain from an involuntary conversion) is elected?
(Multiple Choice)
4.7/5  (81)
(81) Abby exchanges an SUV that she has held for personal use plus $24,000 for a new SUV which she will use exclusively in her sole proprietorship business. This exchange qualifies for nontaxable exchange treatment.
(True/False)
4.9/5 (87)
(87) Jake exchanges an airplane used in his business for a smaller airplane to be used in his business. His adjusted basis for the airplane is $325,000 and the fair market value is $310,000. The fair market value of the smaller airplane is $300,000. In addition, Jake receives cash of $10,000. Calculate Jake's realized and recognized gain or loss and his adjusted basis for the assets received.
(Essay)
4.7/5 (90)
(90) Sammy exchanges equipment used in his business in a like-kind exchange. The property exchanged is as follows:
The other party assumes the liability.
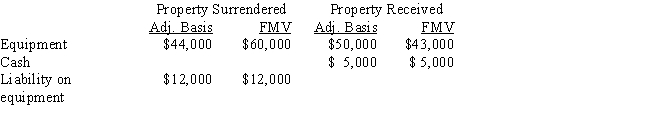 a.What is Sammy's recognized gain or loss?
b.What is Sammy's basis for the assets he received?
a.What is Sammy's recognized gain or loss?
b.What is Sammy's basis for the assets he received? (Essay)
4.7/5 (90)
(90) Which of the following statements is correct with respect to § 1044 (rollover of publicly traded securities gain into specialized small business investment companies)?
(Multiple Choice)
4.8/5 (72)
(72) During 2017, Howard and Mabel, a married couple, decided to sell their residence. The residence has a basis of $162,000 and has been owned and occupied by them for 11 years. The house was sold in May for $395,000 with broker's commissions and other selling expenses being $24,000. They purchased a new residence in June for $400,000. What is the adjusted basis of the new residence?
(Multiple Choice)
4.8/5 (79)
(79) What kinds of property do not qualify under the like-kind provisions?
(Essay)
4.8/5 (57)
(57) For each of the following involuntary conversions, determine if the property qualifies as replacement property.
a.Chuck's restaurant building is destroyed by fire. He clears the site and builds another restaurant building.
b.Diane's warehouse which she used for storing inventory is destroyed by a tornado. She purchases another warehouse in which she will store inventory.
c.Part of Andrew's dairy farm land is condemned to make way for an interstate highway. He uses the condemnation proceeds to construct a barn to be used for storing cattle feed.
d.Liz owns a shopping mall which is destroyed by a flood. Since the tenant occupancy rate was down, she uses the insurance proceeds to purchase an office building which she will rent to tenants.
e.Eleanor's Maserati Gran Turismo is stolen. The original cost was $125,000, and she had used it exclusively for personal use. Due to the limited supply of this model, it had appreciated in value. Eleanor received insurance proceeds of $130,000 and uses the proceeds to purchase a replacement Gran Turismo.
(Essay)
4.8/5 (77)
(77) Melvin receives stock as a gift from his uncle. No gift tax is paid. The adjusted basis of the stock is $30,000 and the fair market value is $38,000. Melvin trades the stock for bonds with a fair market value of $35,000 and $3,000 cash. What is his recognized gain and the basis for the bonds?
(Multiple Choice)
4.8/5 (89)
(89) Which of the following might motivate a taxpayer to try to avoid like-kind exchange treatment?
(Multiple Choice)
4.8/5 (85)
(85) If there is an involuntary conversion (i.e., casualty, theft, or condemnation) of the taxpayer's principal residence, the realized gain may be postponed as a § 1033 involuntary conversion and/or excluded as a § 121 sale of a principal residence.
(True/False)
4.8/5 (77)
(77) When boot in the form of cash is given in a like-kind exchange, recognized gain is the greater of the boot or the realized gain.
(True/False)
4.9/5 (71)
(71) Carlos, who is single, sells his personal residence on November 5, 2017, for $400,000. His adjusted basis was $125,000. He pays realtor's commissions of $20,000. He owned and occupied the residence for 12 years. Having decided that he no longer wants the burdens of home ownership, he invests the sales proceeds in a mutual fund and enters into a 1-year lease on an apartment. The detriments of renting, including a crying child next door, cause Carlos to rethink his decision. Therefore, he purchases another residence on November 6, 2018, for $275,000. Is Carlos eligible for exclusion of gain treatment under § 121 (exclusion of gain on sale of principal residence)? Calculate Carlos's recognized gain and his basis for the new residence.
(Essay)
5.0/5 (79)
(79) Lucinda, a calendar year taxpayer, owned a rental property with an adjusted basis of $312,000 in a major coastal city. Her property was condemned by the city government on October 12, 2017. In order to build a convention center, Lucinda eventually received qualified replacement property from the city government on March 9, 2018. This new property has a fair market value of $410,000.
a.What is Lucinda's recognized gain or loss on the condemnation?
b.What is her adjusted basis for the new property?
c.If, instead of receiving qualifying replacement property, Lucinda was paid $410,000, what is the latest date that she can acquire qualifying replacement property?
(Essay)
4.8/5 (77)
(77) Eric and Faye, who are married, jointly own a house in which they have resided for the past 17 years. They sell the house for $375,000 with realtor's fees of $10,000. Their adjusted basis for the house is $80,000. Since they are in their retirement years, they plan on moving around the country and renting. What is their recognized gain on the sale of the residence if they use the § 121 exclusion (exclusion of gain on sale of principal residence) and if they elect to forgo the § 121 exclusion?
With exclusion Elect to forgo
(Multiple Choice)
4.7/5 (85)
(85) If boot is received in a § 1031 like-kind exchange, the recognized gain cannot exceed the realized gain.
(True/False)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)