



 Chat with AI
Exam 6: Intercompany Profit Transactions - Plant Assets

Exam 1: Business Combinations36 Questions
Exam 2: Stock Investments Investor Accounting and Reporting41 Questions
Exam 3: An Introduction to Consolidated Financial Statements39 Questions
Exam 4: Consolidated Techniques and Procedures38 Questions
Exam 5: Intercompany Profit Transactions - Inventories39 Questions
Exam 6: Intercompany Profit Transactions - Plant Assets39 Questions
Exam 7: Intercompany Profit Transactions - Bonds40 Questions
Exam 8: Consolidations - Changes in Ownership Interests38 Questions
Exam 9: Indirect and Mutual Holdings37 Questions
Exam 10: Subsidiary Preferred Stock,consolidated Earnings Per Share,and Consolidated Income Taxation36 Questions
Exam 11: Consolidation Theories,push-Down Accounting,and Corporate Joint Ventures39 Questions
Exam 12: Derivatives and Foreign Currency: Concepts and Common Transactions40 Questions
Exam 13: Accounting for Derivatives and Hedging Activities40 Questions
Exam 14: Foreign Currency Financial Statements39 Questions
Exam 15: Segment and Interim Financial Reporting38 Questions
Exam 16: Partnerships - Formation,operations,and Changes in Ownership Interests38 Questions
Exam 17: Partnership Liquidation40 Questions
Exam 18: Corporate Liquidations and Reorganizations38 Questions
Exam 19: An Introduction to Accounting for State and Local Governmental Units38 Questions
Exam 20: Accounting for State and Local Governmental Units - Governmental Funds34 Questions
Exam 21: Accounting for State and Local Governmental Units - Proprietary and Fiduciary Funds39 Questions
Exam 22: Accounting for Not-For-Profit Organizations39 Questions
Exam 23: Estates and Trusts36 Questions
Select questions type


Plenny Corporation sold equipment to its 90%-owned subsidiary,Sourdough Corp. ,on January 1,2014.Plenny sold the equipment for $100,000 when its book value was $75,000 and it had a 5-year remaining useful life with no expected salvage value.Straight-line depreciation is used by both companies.Separate balance sheets for Plenny and Sourdough included the following equipment and accumulated depreciation amounts on December 31,2014: 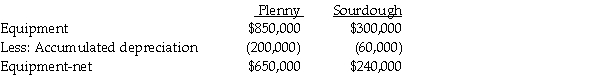 Consolidated amounts for equipment and accumulated depreciation at December 31,2014 were respectively
 (Multiple Choice)
4.8/5  (75)
(75) Several years ago,Peacock International purchased 80% of the outstanding stock of Strutt Incorporated,at a time when Strutt's book values were equal to its fair values.On January 1,2009,Strutt purchased a truck for $160,000 which had no salvage value with a useful life of 8 years,depreciated on a straight-line basis.On January 1,2012,Strutt sold the truck to Peacock Corporation for $56,000.The equipment was estimated to have a five-year remaining life on this date,with no salvage value.All affiliates use the straight-line depreciation method.
Required:
Prepare the consolidation entries required for Peacock and subsidiary at:
1.December 31,2012
2.December 31,2013
3.December 31,2014
4.December 31,2015
(Essay)
4.7/5 (77)
(77) Passo Corporation acquired a 70% interest in Saun Corporation in 2009 at a time when Saun's book values and fair values were equal.In 2012,Saun sold land to Passo for $82,000 that cost $72,000.The land remained in Passo's possession until 2014 when Passo sold it outside the combined entity for $102,000.
After the books were closed in 2014,it was discovered that Passo had not considered the unrealized gain from its intercompany purchase of land in preparing the consolidated financial statements.The only entry on Passo's books was a debit to Land and a credit to Cash in 2012 for $82,000,and in 2014,a debit to Cash for $102,000 and credits to Land for $82,000 and Gain on sale of land for $20,000.
Before the discovery of the error,the consolidated financial statements disclosed the following amounts: 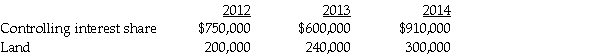 Required:
1.Prepare elimination/adjusting entries relating to the land on the consolidated working papers for December 31,2012,December 31,2013 and December 31,2014.
2.Determine the correct amounts for Land in 2012,2013,and 2014.
3.Calculate the amount at which the gain on the sale of land should have been reported in 2014.
Required:
1.Prepare elimination/adjusting entries relating to the land on the consolidated working papers for December 31,2012,December 31,2013 and December 31,2014.
2.Determine the correct amounts for Land in 2012,2013,and 2014.
3.Calculate the amount at which the gain on the sale of land should have been reported in 2014. (Essay)
4.7/5 (83)
(83) Plock Corporation,the 75% owner of Seraphim Company,reported net income of $400,000 in 2013,prior to recording any income from Seraphim.Seraphim reported net income for that same year of $80,000 on their stand-alone statements.During 2013,an intercompany sale of a vehicle resulted in a gain of $4,000,and the vehicle was assumed to have a four-year remaining useful life.The vehicle has no salvage value.Straight-line depreciation is used.
Required:
1.Assuming that the vehicle transfer was downstream,calculate Plock's consolidated net income for 2013,and controlling share of consolidated net income for 2013.
2.Assuming that the vehicle transfer was upstream,calculate Plock's consolidated net income for 2013,and controlling share of consolidated net income for 2013.
(Essay)
4.9/5 (82)
(82) Parrot Company owns all the outstanding voting stock of Southern Manufacturing.On January 1,2014,Parrot sold machinery to Southern at its book value of $24,000.Parrot had the machinery three years before selling it and used an eight-year straight-line depreciation method,with zero salvage value.Southern will use the straight-line depreciation method,and assumes the machine has five years remaining and no salvage value.In the 2014 consolidating working papers,the depreciation expense
(Multiple Choice)
4.8/5 (90)
(90) Assume an upstream sale of machinery occurs on January 1,2014.The parent owns 70% of the subsidiary.There is a gain on the intercompany transfer and the machine has five remaining years of useful life and no salvage value.Straight-line depreciation is used.Which of the following statements is correct?
(Multiple Choice)
4.9/5 (84)
(84) Use the following information to answer the question(s)below.
On December 31,2014,Pinne Corporation sold equipment with a three-year remaining useful life and a book value of $21,000 to its 70%-owned subsidiary,Sull Company,for a price of $27,000.Pinne bought the equipment four years ago for $49,000.The salvage value is zero.Straight-line depreciation is used by both companies.
-On January 2,2014,Paogo Company sold a truck with book value of $15,000 to Sanall Corporation,its wholly-owned subsidiary,for $20,000.The truck had a remaining useful life of five years with zero salvage value.Both firms use the straight-line depreciation method.If Paogo failed to make year-end adjustments/eliminations on the consolidated working papers in 2014,consolidated depreciation expense for 2014 would be
(Multiple Choice)
4.8/5 (73)
(73) Controlling interest share in consolidated net income for 2014 was
(Multiple Choice)
4.8/5 (80)
(80) Pogo Corporation acquired a 75% interest in Sperry Corporation on January 1,2011 at a cost equal to book value and fair value.In the same year Sperry sold land costing $25,000 to Pogo for $50,000.On July 1,2014,Pogo sold the land to an unrelated party for $85,000.What was the gain on the sale of the land on the consolidated income statement for 2014?
(Multiple Choice)
4.9/5 (69)
(69) Several years ago,Pilot International purchased 70% of the outstanding stock of Skyway Incorporated,at a time when Skyway's book values were equal to its fair values.On January 1,2011 Skyway purchased a truck for $80,000 which had no salvage value with a useful life of 8 years,depreciated on a straight-line basis.On January 1,2014,Skyway sold the truck to Pilot Corporation for $28,000.The truck was estimated to have a five-year remaining life on this date,and no salvage value.All affiliates use the straight-line depreciation method.
Required:
Prepare all relevant entries with respect to the truck.
1.Record the journal entries on Pilot's books for 2014.
2.Record the journal entries on Skyway's books for 2014.
3.Prepare the consolidation entries required for Pilot and subsidiary for 2014 as a result of this transaction.
(Essay)
4.9/5 (98)
(98) Parrot Corporation acquired a 70% interest in Swifti Corp.on January 1,2013,when Swifti's book values and fair values were equivalent.On January 1,2014,Swifti sold a building with a book value of $60,000 to Parrot for $80,000.The building had a remaining life of five years,no salvage value,and was depreciated by the straight-line method.Swifti reported net income of $200,000 for 2014.What was the noncontrolling interest share for 2014?
(Multiple Choice)
4.8/5 (77)
(77) Separate income statements of Plantation Corporation and its 90%-owned subsidiary,Savannah Corporation,for 2014 are as follows,prior to Plantation recording any income related to its subsidiary: 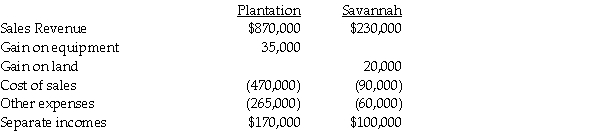 Additional information:
1.Plantation acquired its 90% interest in Savannah Corporation when the book values were equal to the fair values.
2.The gain on equipment relates to equipment with a book value of $95,000 and a 7-year remaining useful life that Plantation sold to Savannah for $130,000 on January 1,2014.The straight-line depreciation method was used and the equipment has no salvage value.
3.On January 1,2014,Savannah sold land to an outside entity for $90,000.The land was acquired from Plantation in 2009 for $70,000.The original cost of the land to Plantation was $45,000.
4.Savannah did not declare or distribute dividends in 2014.
Required:
1.Prepare elimination/adjusting entries on the consolidated worksheet for the year 2014.
2.Prepare the consolidated income statement for the year ended December 31,2014.
Additional information:
1.Plantation acquired its 90% interest in Savannah Corporation when the book values were equal to the fair values.
2.The gain on equipment relates to equipment with a book value of $95,000 and a 7-year remaining useful life that Plantation sold to Savannah for $130,000 on January 1,2014.The straight-line depreciation method was used and the equipment has no salvage value.
3.On January 1,2014,Savannah sold land to an outside entity for $90,000.The land was acquired from Plantation in 2009 for $70,000.The original cost of the land to Plantation was $45,000.
4.Savannah did not declare or distribute dividends in 2014.
Required:
1.Prepare elimination/adjusting entries on the consolidated worksheet for the year 2014.
2.Prepare the consolidated income statement for the year ended December 31,2014. (Essay)
4.9/5 (77)
(77) Pigeon Corporation purchased land from its 60%-owned subsidiary,Seed Inc. ,in 2012 at a cost $50,000 greater than Seed's book value.In 2014,Pigeon sold the land to an outside entity for $20,000 more than Pigeon's book value.The 2014 consolidated income statement should report a gain on the sale of land of
(Multiple Choice)
4.8/5 (85)
(85) On January 1,2013,Pilgrim Imaging purchased 90% of the outstanding common stock of Snapshot Productions for $585,000 cash.The remaining 10% of Snapshot had an assessed fair value of $65,000 at that time.Snapshot had equipment that was undervalued on their books by $50,000,and an unrecorded patent with a fair value of $15,000.The equipment had five years remaining to its useful life,and the patent had 10 years remaining to its useful life.
On January 1,2014,Pilgrim sold Snapshot a building for $100,000 that had originally cost $140,000.The book value was $60,000 at the date of transfer,and had a five-year remaining life at the date of transfer.Straight-line depreciation is used with no salvage value.Several line items from the companies' separate December 31,2014 trial balances are shown below.
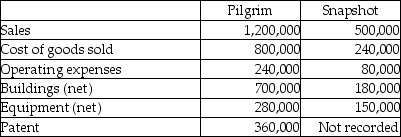 Required: Determine consolidated balances for each of the accounts listed as of December 31,2014.
 (Essay)
4.8/5 (93)
(93) Prey Corporation created a wholly owned subsidiary,Sage Corporation,on January 1,2013,at which time Prey sold land with a book value of $90,000 to Sage at its fair market value of $140,000.Also,on January 1,2013,Prey sold to Sage equipment with a book value of $130,000 and a selling price of $165,000.The equipment had a remaining useful life of 4 years and is being depreciated under the straight-line method.The equipment has no salvage value.On January 1,2015,Sage resold the land to an outside entity for $150,000.Sage continues to use the equipment purchased from Prey.Income statements for Prey and Sage for the year ended December 31,2015 are summarized below: 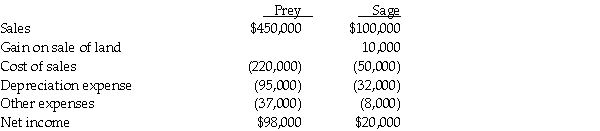 Required:
At what amounts did the following items appear on the consolidated income statement for Prey and Subsidiary for the year ended December 31,2015?
1.Gain on Sale of Land
2.Depreciation Expense
3.Consolidated net income
4.Controlling interest share of consolidated net income
Required:
At what amounts did the following items appear on the consolidated income statement for Prey and Subsidiary for the year ended December 31,2015?
1.Gain on Sale of Land
2.Depreciation Expense
3.Consolidated net income
4.Controlling interest share of consolidated net income (Essay)
4.9/5 (78)
(78) Piglet Incorporated purchased 90% of the outstanding stock of Sourgrape Company several years ago at book value.At January 1,2012,Sourgrape sold land with a book value of $30,000 to Piglet at its fair market value of $40,000.At the same time,Sourgrape sold the building that was on the land to Piglet.The building had a book value of $80,000 and was sold at its fair value of $120,000.The building had a remaining useful life of 8 years and is depreciated using the straight-line method.The building has no salvage value.On January 1,2014,Piglet sold the land and building to a third party.The sales price was allocated so that the land was sold for $50,000 and the building was sold for $150,000.Income statements for Piglet and Sourgrape for the year ended December 31,2014 are summarized below: 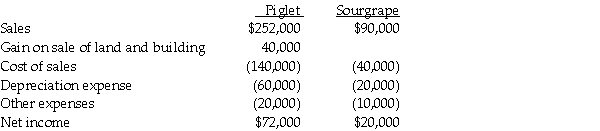 Required:
Prepare the eliminating/adjusting entries related to the land and building on the consolidated working papers on the following dates:
1.December 31,2012
2.December 31,2013
3.December 31,2014
Required:
Prepare the eliminating/adjusting entries related to the land and building on the consolidated working papers on the following dates:
1.December 31,2012
2.December 31,2013
3.December 31,2014 (Essay)
4.9/5 (77)
(77) Palmer Corporation purchased 75% of Stone Industries' common stock on January 2,2012.On January 1,2013,Stone sold equipment to Palmer that had a net book value of $16,000 and an original cost of $24,000 for $20,000.On January 1,2013,Palmer sold a building to Stone that had a net book value of $200,000 and an original cost of $250,000 for $300,000.The equipment had a remaining useful life of 8 years,and the building had a remaining useful life of 20 years.Neither asset had salvage value.Both companies use straight-line depreciation.
Selected account balances are shown below for Palmer and Stone for the year ended December 31,2013: 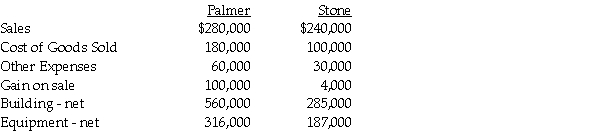 Required:
1.Prepare the consolidating working paper entries relating to the equipment and building for the year ended December 31,2013.
2.Calculate the following balances for the year ended December 31,2013:
A.Consolidated "Other Expenses"
B.Consolidated Buildings
C.Consolidated Equipment
D.Noncontrolling interest in Stone's net income
Required:
1.Prepare the consolidating working paper entries relating to the equipment and building for the year ended December 31,2013.
2.Calculate the following balances for the year ended December 31,2013:
A.Consolidated "Other Expenses"
B.Consolidated Buildings
C.Consolidated Equipment
D.Noncontrolling interest in Stone's net income (Essay)
5.0/5 (94)
(94) Plower Corporation acquired all of the outstanding voting common stock of the Squab Corporation several years ago when the book values and fair values of Squab's net assets were equal.
On April 1,2012,Plower sold land that cost $25,000 to Squab for $40,000.Squab resold the land for $45,000 on December 1,2014.
On July 1,2014,Plower sold equipment with a book value of $10,000 to Squab for $26,000.Squab is depreciating the equipment over a four-year period using the straight-line method.The equipment has no salvage value.
Required:
The first two columns in the working papers presented below summarize income statement information from the separate company financial statements of Plower and Squab for the year ended December 31,2014.Fill in the consolidated working paper columns to show how each of the items from the separate company reports will appear in the consolidated income statement for the year ended December 31,2014.
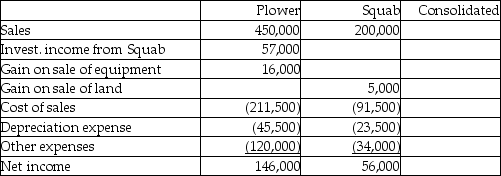
(Essay)
4.9/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)