



 Chat with AI
Exam 6: Intercompany Profit Transactions - Plant Assets

Exam 1: Business Combinations36 Questions
Exam 2: Stock Investments Investor Accounting and Reporting41 Questions
Exam 3: An Introduction to Consolidated Financial Statements39 Questions
Exam 4: Consolidated Techniques and Procedures38 Questions
Exam 5: Intercompany Profit Transactions - Inventories39 Questions
Exam 6: Intercompany Profit Transactions - Plant Assets39 Questions
Exam 7: Intercompany Profit Transactions - Bonds40 Questions
Exam 8: Consolidations - Changes in Ownership Interests38 Questions
Exam 9: Indirect and Mutual Holdings37 Questions
Exam 10: Subsidiary Preferred Stock,consolidated Earnings Per Share,and Consolidated Income Taxation36 Questions
Exam 11: Consolidation Theories,push-Down Accounting,and Corporate Joint Ventures39 Questions
Exam 12: Derivatives and Foreign Currency: Concepts and Common Transactions40 Questions
Exam 13: Accounting for Derivatives and Hedging Activities40 Questions
Exam 14: Foreign Currency Financial Statements39 Questions
Exam 15: Segment and Interim Financial Reporting38 Questions
Exam 16: Partnerships - Formation,operations,and Changes in Ownership Interests38 Questions
Exam 17: Partnership Liquidation40 Questions
Exam 18: Corporate Liquidations and Reorganizations38 Questions
Exam 19: An Introduction to Accounting for State and Local Governmental Units38 Questions
Exam 20: Accounting for State and Local Governmental Units - Governmental Funds34 Questions
Exam 21: Accounting for State and Local Governmental Units - Proprietary and Fiduciary Funds39 Questions
Exam 22: Accounting for Not-For-Profit Organizations39 Questions
Exam 23: Estates and Trusts36 Questions
Select questions type


Park Incorporated purchased a 70% interest in Silk Company in 2012 at book value.On January 1,2014,equipment having a historical cost of $100,000 and a net book value of $70,000 is sold in an intercompany transfer for $90,000.The equipment has a remaining useful life of five years and no salvage value.Straight-line depreciation is used by both companies.Silk reports net income of $180,000 in 2014 and $200,000 in 2015.
Required:
1.Assume Park sold the equipment to Silk.
A.Prepare the consolidating worksheet entries for the equipment for 2014 and 2015.
B.Calculate the noncontrolling interest share in Silk's income for 2014 and 2015.
2.Assume that Silk sold the equipment to Park.
A.Prepare the consolidating worksheet entries for the equipment for 2014 and 2015.
B.Calculate the noncontrolling interest share in Silk's income for 2014 and 2015.

Free
(Essay)
4.7/5  (79)
(79) Correct Answer: Verified
Requirement 1A 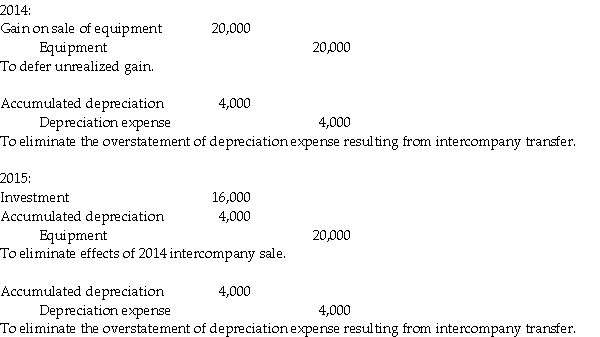
Requirement 1B 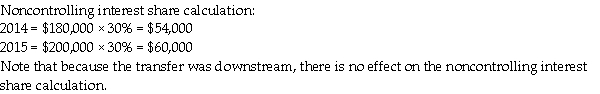
Requirement 2A
2014: 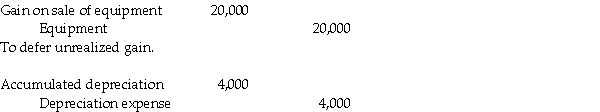
To eliminate the overstatement of depreciation expense resulting from intercompany transfer.
2015: 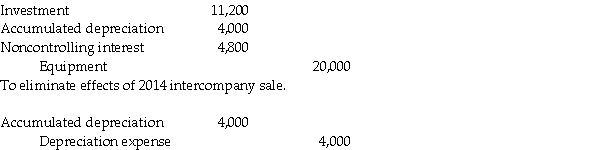
To eliminate the overstatement of depreciation expense resulting from intercompany transfer.
Requirement 2B
2014: 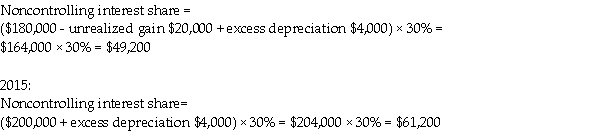
Paula's Pizzas purchased 80% of their supplier,Sarah's Sauces.Sarah's book values equaled fair value at the time of the acquisition.Paula sold Sarah some packaging equipment on January 2,2013 for $100,000.The equipment had a carrying value of $90,000,and original cost of $120,000,and had a remaining life of 10 years.Both Paula and Sarah depreciate their assets on the straight-line method.The equipment has no salvage value.
Required: Prepare the following entries:
1.Journal entries Paula and Sarah will prepare on their separate books in 2013.
2.Eliminating/adjusting entries on the consolidation worksheet at the end of 2013.
3.Eliminating/adjusting entries on the consolidation worksheet at the end of 2014.
Free
(Essay)
4.8/5 (99)
(99) Correct Answer:Verified
Verified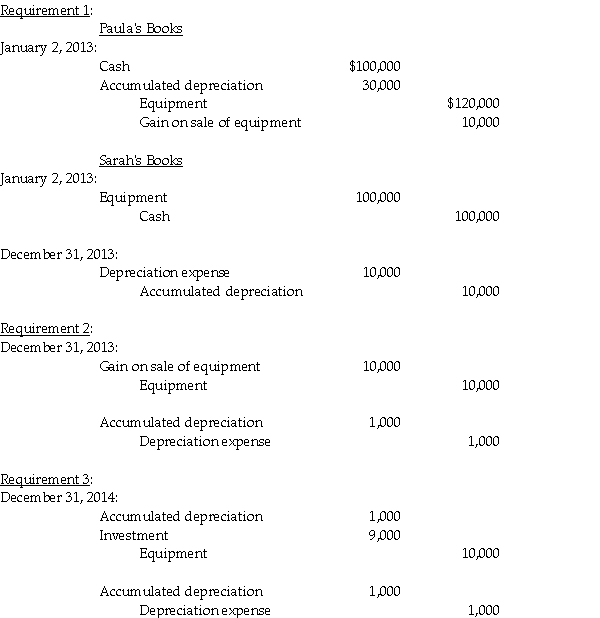
Pied Imperial Corporation acquired a 90% interest in Somest Corporation in 2012 when Somest's book values were equivalent to fair values.Somest sold equipment with a book value of $80,000 to Pied for $130,000 on January 1,2014.Pied is fully depreciating the equipment over a 4-year period by using the straight-line method.Somest reported net income for 2014 was $320,000.Pied's 2014 income from Somest was
Free
(Multiple Choice)
4.7/5 (74)
(74) Correct Answer:Verified
VerifiedC
On January 2,2014,Pal Corporation sold warehouse equipment to SimCo,a wholly-owned subsidiary.The equipment had an original cost of $130,000 and a net book value of $100,000 when it was sold to SimCo for $150,000.Both companies agreed that the equipment had a five-year remaining life and compute depreciation on the straight-line method.The equipment has no salvage value.
Pal reported $470,000 in net income in 2014 (prior to reporting any income from SimCo),and SimCo reported $160,000 in net income.
Required:
1.Calculate consolidated net income for 2014.
2.Determine the controlling share of net income for the year if Pal only owned 75% of SimCo.
3.Determine the controlling share of net income for the year if Pal only owned 75% of SimCo AND the equipment transfer was upstream.
(Essay)
4.9/5 (85)
(85) Snow Company is a wholly owned subsidiary of Penguin Corporation.On January 1,2011,Penguin transferred equipment to Snow for $195,000.The equipment had originally cost $250,000,but at the time of transfer,had a $180,000 book value and a five year remaining life.Both companies use the straight-line method of depreciation and assume no salvage value for the equipment.
Required: Prepare the consolidation worksheet entries for this asset on the following dates:
1.December 31,2011
2.December 31,2012
3.December 31,2013
(Essay)
4.9/5 (82)
(82) On January 1,2014,Bigg Corporation sold equipment with a book value of $20,000 and a 10-year remaining useful life to its wholly-owned subsidiary,Little Corporation,for $30,000.Both Bigg and Little use the straight-line depreciation method,assuming no salvage value.On December 31,2014,the separate company financial statements held the following balances associated with the equipment: 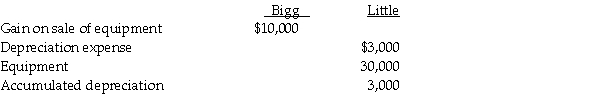 A working paper entry to consolidate the financial statements of Bigg and Little on December 31,2014 included a
 (Multiple Choice)
5.0/5 (86)
(86) Pierce Manufacturing owns all of the outstanding voting common stock of Sylvia Company,as acquired several years ago when the book values and fair values of Sylvia's net assets were equal.
In 2013,Pierce set out to re-structure the company,and in doing so,re-aligned the manufacturing processes to streamline the use of automated equipment.As a result,they set out to move certain equipment around between the facilities owned by both Pierce and Sylvia,and ultimately agreed on the following transfers and exchange prices.It was agreed that the exchange price would be paid in cash on January 1,2014,the date the equipment was transferred.Straight-line depreciation is used and the different pieces of equipment have no salvage value.
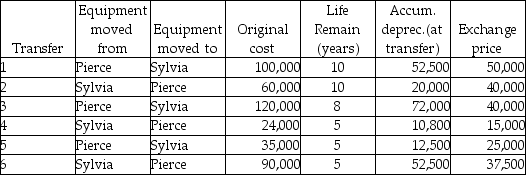 Required:
1.Prepare the journal entry that Pierce would record for each transfer listed.
2.Prepare the journal entry that Sylvia would record for each transfer listed.
3.Prepare the consolidation worksheet entries that would be required as a result of the above transactions for 2014.
Required:
1.Prepare the journal entry that Pierce would record for each transfer listed.
2.Prepare the journal entry that Sylvia would record for each transfer listed.
3.Prepare the consolidation worksheet entries that would be required as a result of the above transactions for 2014. (Essay)
4.9/5 (90)
(90) Porter Corporation acquired 70% of the outstanding voting common stock of Sherman Inc.in 2008.On January 1,2009,Sherman Inc.purchased a depreciable machine for $120,000 cash with an estimated useful life of 10 years that was depreciated on a straight-line basis.The machine has no estimated salvage value.Sherman used the machine until the end of 2011.On January 2,2012,Sherman sold the machine to Porter who continued to use the same estimated life (seven years remaining),salvage value and depreciation method that was used by Sherman.At the end of 2012,Sherman reported a gain on sale of the machine of $14,000.
Required:
Answer the following questions concerning Porter and Sherman.
1.Prepare elimination/adjusting entries for the consolidated working papers for the year ended December 31,2012.
2.How much depreciation expense relating to the transferred asset did Porter record in 2012 on the company's separate books?
3.How much depreciation expense relating to the transferred asset was reported on the consolidated income statement in 2012?
4.What amounts were reported for the Machine and the Accumulated Depreciation in the consolidated balance sheet on December 31,2012?
(Essay)
4.9/5 (75)
(75) Use the following information to answer the question(s)below.
On December 31,2014,Pinne Corporation sold equipment with a three-year remaining useful life and a book value of $21,000 to its 70%-owned subsidiary,Sull Company,for a price of $27,000.Pinne bought the equipment four years ago for $49,000.The salvage value is zero.Straight-line depreciation is used by both companies.
-An elimination entry at December 31,2014 for the intercompany sale will include a
(Multiple Choice)
4.9/5 (75)
(75) Use the following information to answer the question(s)below.
On January 1,2012,Shrimp Corporation purchased a delivery truck with an expected useful life of five years,and a salvage value of $8,000.On January 1,2014,Shrimp sold the truck to Pacet Corporation.Pacet assumed the same salvage value and remaining life of three years used by Shrimp.Straight-line depreciation is used by both companies.On January 1,2014,Shrimp recorded the following journal entry:  Pacet holds 60% of Shrimp.Shrimp reported net income of $55,000 in 2014 and Pacet's separate net income (excludes interest in Shrimp)for 2014 was $98,000.
-In preparing the consolidated financial statements for 2014,the elimination entry for depreciation expense was a
Pacet holds 60% of Shrimp.Shrimp reported net income of $55,000 in 2014 and Pacet's separate net income (excludes interest in Shrimp)for 2014 was $98,000.
-In preparing the consolidated financial statements for 2014,the elimination entry for depreciation expense was a (Multiple Choice)
4.8/5 (75)
(75) Use the following information to answer the question(s)below.
On December 31,2014,Pinne Corporation sold equipment with a three-year remaining useful life and a book value of $21,000 to its 70%-owned subsidiary,Sull Company,for a price of $27,000.Pinne bought the equipment four years ago for $49,000.The salvage value is zero.Straight-line depreciation is used by both companies.
-After eliminating/adjusting entries are prepared,what was the intercompany sale impact on the consolidated financial statements for the year ended December 31,2014? \( \begin{array}{ll}\text {
(Multiple Choice)
4.9/5 (71)
(71) Peregrine Corporation acquired an 80% interest in Serine Corporation in 2011 at a time when Serine's book values and fair values were equal to one another.On January 1,2014,Serine sold a truck with a $55,000 book value to Peregrine for $100,000.Peregrine is depreciating the truck over 10 years using the straight-line method.The truck has no salvage value.Separate incomes for Peregrine and Serine for 2014 were as follows: 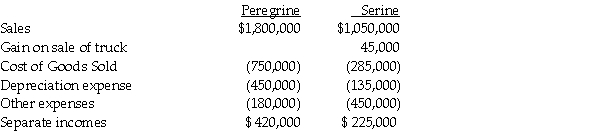 Peregrine's investment income from Serine for 2014 was
 (Multiple Choice)
4.8/5 (84)
(84) Use the following information to answer the question(s)below.
On January 1,2012,Shrimp Corporation purchased a delivery truck with an expected useful life of five years,and a salvage value of $8,000.On January 1,2014,Shrimp sold the truck to Pacet Corporation.Pacet assumed the same salvage value and remaining life of three years used by Shrimp.Straight-line depreciation is used by both companies.On January 1,2014,Shrimp recorded the following journal entry: Pacet holds 60% of Shrimp.Shrimp reported net income of $55,000 in 2014 and Pacet's separate net income (excludes interest in Shrimp)for 2014 was $98,000.
-In the eliminating/adjusting entries on consolidation working papers for 2014,the Truck account was
Pacet holds 60% of Shrimp.Shrimp reported net income of $55,000 in 2014 and Pacet's separate net income (excludes interest in Shrimp)for 2014 was $98,000.
-In the eliminating/adjusting entries on consolidation working papers for 2014,the Truck account was (Multiple Choice)
4.8/5 (74)
(74) Separate income statements of Pingair Corporation and its 90%-owned subsidiary,Staunch Inc. ,for 2014 were as follows: 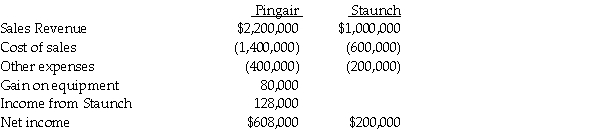 Additional information:
1.Pingair acquired its 90% interest in Staunch Inc.when the book values were equal to the fair values.
2.The gain on equipment relates to equipment with a book value of $120,000 and a 4-year remaining useful life that Pingair sold to Staunch for $200,000 on January 2,2014.The straight-line depreciation method is used.The equipment has no salvage value.
3.Pingair sold inventory to Staunch in 2013 and 2014 as shown in the table below.(The 2013 ending inventory is sold in 2014 . )
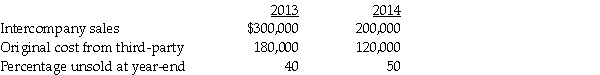 4.Staunch did not declare or pay dividends in 2013 and 2014.
Required:
1.Prepare adjusting/eliminating entries for the consolidation worksheet at December 31,2014.
2.Prepare a consolidated income statement for Pingair Corporation and Subsidiary for the year ended December 31,2014.
Additional information:
1.Pingair acquired its 90% interest in Staunch Inc.when the book values were equal to the fair values.
2.The gain on equipment relates to equipment with a book value of $120,000 and a 4-year remaining useful life that Pingair sold to Staunch for $200,000 on January 2,2014.The straight-line depreciation method is used.The equipment has no salvage value.
3.Pingair sold inventory to Staunch in 2013 and 2014 as shown in the table below.(The 2013 ending inventory is sold in 2014 . )
4.Staunch did not declare or pay dividends in 2013 and 2014.
Required:
1.Prepare adjusting/eliminating entries for the consolidation worksheet at December 31,2014.
2.Prepare a consolidated income statement for Pingair Corporation and Subsidiary for the year ended December 31,2014. (Essay)
4.8/5 (83)
(83) Pollek Corporation paid $16,200 for a 90% interest in Swamp Corporation on January 1,2013,when Swamp stockholders' equity consisted of $10,000 Capital Stock and $3,000 of Retained Earnings.The excess cost over book value was attributable to goodwill.
Additional information:
1.Pollek sells merchandise to Swamp at 120% of Pollek's cost.During 2013,Pollek's sales to Swamp were $4,800,of which half of the merchandise remained in Swamp's inventory at December 31,2013.(The 2013 ending inventory was sold in 2014 . )During 2014,Pollek's sales to Swamp were $6,000 of which 60% remained in Swamp's inventory at December 31,2014.At year-end 2014,Swamp owed Pollek $1,500 for the inventory purchased during 2014.
2.Pollek Corporation sold equipment with a book value of $2,000 and a remaining useful life of four years and no salvage value to Swamp Corporation on January 1,2014 for $2,800.Straight-line depreciation is used.
3.Separate company financial statements for Pollek Corporation and Subsidiary at December 31,2014 are summarized in the first two columns of the consolidation working papers.
4.The following information is available for 2013: 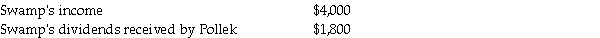 Required:
Complete the working papers to consolidate the financial statements of Pollek Corporation and subsidiary for the year ended December 31,2014.
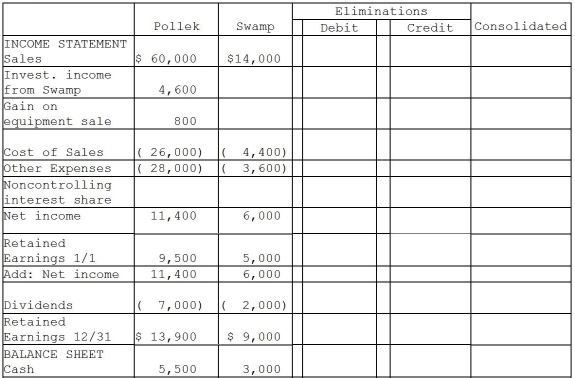
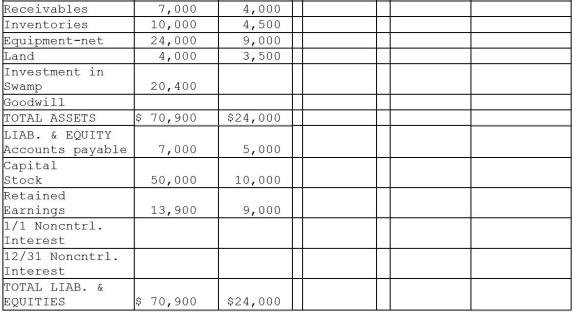
Required:
Complete the working papers to consolidate the financial statements of Pollek Corporation and subsidiary for the year ended December 31,2014.
(Essay)
4.8/5 (68)
(68) Petrol Company acquired an 90% interest in Seadig Corporation on January 1,2013.On January 1,2014,Seadig sold a building with a book value of $120,000 to Petrol for $150,000.The building had a remaining useful life of ten years and no salvage value.Straight-line depreciation is used.The separate balance sheets of Petrol and Seadig on December 31,2014 included the following balances: 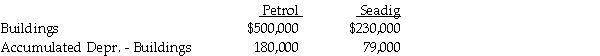 The consolidated amounts for Buildings and Accumulated Depreciation - Buildings that appeared,respectively,on the balance sheet at December 31,2014,were
 (Multiple Choice)
4.8/5 (98)
(98) On January 1,2014 Saffron Co.recorded a $40,000 profit on the upstream sale of some equipment that had a remaining four-year life under the straight-line depreciation method.The equipment has no salvage value.Saffron had separate income of $100,000 in 2014.The parent company,Pommel Incorporated,owns 90% of Saffron.Pommel would report investment income from Saffron in 2014 of
(Multiple Choice)
4.8/5 (71)
(71) Pigeon Company owns 80% of the outstanding stock of Spiniflex Corporation,which was purchased on January 1,2008,when Spiniflex's book values were equal to its fair values.The amount paid by Pigeon included $16,000 for goodwill.
On January 1,2009,Pigeon purchased a truck for $40,000 which had no salvage value with a useful life of 8 years,depreciated on a straight-line basis.On January 1,2014,Pigeon sold the truck to Spiniflex Corporation for $18,000.The truck was estimated to have a three-year remaining life on this date and no salvage value.All affiliates use the straight-line depreciation method.
Required:
Prepare all relevant entries with respect to the truck.
1.Record the journal entries on Pigeon's books for 2014.
2.Record the journal entries on Spiniflex's books for 2014.
3.Prepare the consolidation entries required for Pigeon and subsidiary for 2014 as a result of this transaction.
(Essay)
4.8/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)