



 Chat with AI
Exam 3: Accrual Accounting

Exam 1: Fundamentals of Financial Accounting Theory33 Questions
Exam 2: Conceptual Frameworks for Financial Reporting60 Questions
Exam 3: Accrual Accounting160 Questions
Exam 4: Revenue and Recognition105 Questions
Exam 5: Cash and Receivables119 Questions
Exam 6: Inventories157 Questions
Exam 7: Financial Assets137 Questions
Exam 8: Property, Plant and Equipment127 Questions
Exam 9: Intangible Assets, Goodwill, Mineral Resources, and Government Grants81 Questions
Exam 10: Applications of Fair Value to Non-Current Assets121 Questions
Select questions type


The following event occurred after the company's year-end but before the completion of the audit. For this subsequent event, determine whether the event:
•requires an adjustment to the year-end financial statements,
•requires note disclosure, or
•requires neither adjustment to recognized amounts nor disclosure.
A new competitor enters the marketplace, which will result in serious price competition and, likely, reduced income next year. (Justify your recommendation.)
(Essay)
4.8/5  (71)
(71) Which of the following is not an example of a "cash" cycle?
(Multiple Choice)
4.9/5 (86)
(86) Which statement is correct about the difference between IFRS and ASPE?
(Multiple Choice)
4.9/5 (84)
(84) Which of the following would be accounted for on a prospective basis? (More than one answer may be correct.)
A)A furniture maker decreases bad debts expense from 3% to 2% of credit sales.
B)A manufacturer determines that credit losses are becoming material due to deteriorating economic conditions. As a result, it decides to set up an allowance for doubtful accounts at 5% of amounts over 90 days.
C)A parking service estimates bad debts to be 10% of the value of parking violations issued. In the current year, it changes to estimating the allowance for bad debts to be equal to 20% of accounts 30 to 90 days and 50% of accounts over 90 days.
D)A shipbuilder changes its revenue recognition policy from the point of receipt by the customer to when the ship leaves the factory shipyard. This change results from a change in shipping policy from f.o.b. destination to f.o.b. shipping point. (Recall from introductory accounting that f.o.b. means "free on board," and it refers to the point at which ownership transfers from seller to buyer.)
E)An electronics retailer has never accrued for warranties or product guarantees. A new consumer protection law comes into effect, giving buyers of electronic products a guarantee against defects for 180 days after purchase and the ability to return defective products to the retailer.
F)A clothing company that has been operating for 20 years decides to obtain an external audit for the first time in order to meet the bank's demands. The audit firm recommends that management report inventories at the lower of cost and net realizable value, whereas the company has previously only tracked and reported inventory figures at cost.
(Short Answer)
4.9/5 (77)
(77) Prepare a multiple-step income statement using the following data for Bella Inc for the year ended December 31, 2021.
Sales revenue \ 300,000 Rental revenue 35,000 Loss on sale of short-term investments 19,000 Distribution expense 23,000 Cost of goods sold 150,000 General and administrative expense 25,000 Depreciation expense 20,000 Interest income 5,000 Income taxexpense ( 25\% rate on all items)
(Essay)
4.9/5 (79)
(79) Hatcher Limited, a private company, was started on January 1, 2020. For the first year, the chief accountant prepared the financial statements and a local accountant completed the necessary review of these statements. However, for the year ended December 31, 2021, an external auditor was appointed. For each situation below, explain the recommended treatment for each of these matters in terms of whether they are errors, changes in accounting policy, or changes in estimate. Explain your conclusion.
1)Long-term contracts: Hatcher used the completed contract method for revenue recognition in 2020. Management now believes that the percentage of completion method would be better. Income under the completed contract method for 2020 was $3,800,000 and for 2021 it was $3,600,000. If the percentage of completion method had been used, the income would have been $5,800,000 (2020)and $3,400,000 (2021).
2)Accounts receivable: The accounts receivable on December 31, 2020, included a $30,000 account which was not provided for but subsequently was written off during 2021 as the customer went bankrupt after the issuance of the financial statements. Hatcher would like to adjust 2020 for this oversight as it sees this as an error.
3)Machine depreciation: Hatcher has a machine that cost $500,000 and has been depreciated over an estimated useful life of 10 years. Upon reviewing the manufacturer's reports in 2021, management now firmly believes the machine will last a total of 15 years from date of purchase. They would like to change last year's depreciation charge based on this analysis. Depreciation expense of $50,000 has been recorded for 2021.
4)Building depreciation: The company's building (cost $5,000,000, estimated salvage value $0, useful life 20 years)was depreciated last year using the 10% declining-balance method. The company and auditor now agree that the straight-line method would be a more appropriate method to use. A depreciation provision of $450,000 has been made for 2021.
5)Inventories: The accountant last year failed to apply the lower of cost or net realizable value to ending inventory. Upon review, the inventory balance for last year should have been reduced by $250,000. The closing inventory allowance for this year-end should be $370,000. No entry has been made for this.
"6)Warranties: Hatcher does not accrue for warranties; rather it records the warranty expense when claims are paid. Hatcher provides a one-year warranty for defective goods. Payments to satisfy warranty claims in 2020 were $160,000, and $370,000 in 2021. Out of the $370,000 paid in 2021, $170,000 related to 2020 sales. A reasonable estimate of warranties payable at the end of 2021 is $270,000.
Recommended treatment Supporting explanation 1 2 3 4 5 6 "
(Essay)
4.9/5 (88)
(88) Explain why estimates are necessary in accrual accounting and why a "true" measure of income cannot be provided.
(Essay)
4.9/5 (80)
(80) Handy Corp. retired bonds payable with a carrying value of $980,000. What effect does this transaction have on total assets and shareholders' equity?
(Multiple Choice)
4.7/5 (66)
(66) Using the data provided below, determine whether the income statement will be formatted by "function of expense" or by "nature of expense." Briefly explain your response.
Distribution expense 65,000 Cost of goods sold 100,000 General and administrative expense 45,000 Warehousing expense 20,000 Interest expense 5,000
(Essay)
4.9/5 (87)
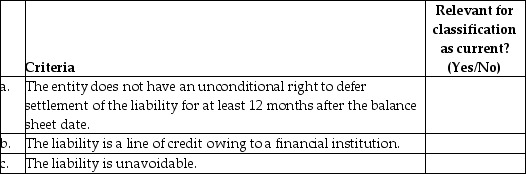
(87) IFRS identifies a number of criteria to determine whether a liability should be classified as current. A liability that satisfies any one of these criteria must be classified as current. For the following list of criteria, identify whether each one is relevant for the classification of a liability as current instead of non-current.
(Essay)
4.9/5 (83)
(83) What is the impact of overstating an accrued expense during the 2020 fiscal year?
(Multiple Choice)
4.9/5 (88)
(88) Lean Ltd. had a balance of $52,300 in the office supplies account at the start of the year. During the year, purchases of $141,700 were made and debited to the office supplies account. At the end of the year, a physical count of the office supplies indicated $41,800 on hand. What was the office supplies expense for the year?
(Multiple Choice)
4.9/5 (79)
(79) What is the effect of overstating 2021 depreciation expense?
(Multiple Choice)
4.9/5 (64)
(64) A company's reported earnings are $2,000 and cash flows are $1,600. Based on economic conditions during the year, the company booked allowances of $150. As a result of contractual incentives, the company booked a further $250 in accruals. What is the amount of unbiased earnings?
(Multiple Choice)
4.8/5 (80)
(80) Which of the following would be accounted for as a change in accounting policy? (More than one answer may be correct.)
A)A furniture maker decreases bad debts expense from 3% to 2% of credit sales.
B)A manufacturer determines that credit losses are becoming material due to deteriorating economic conditions. As a result, it decides to set up an allowance for doubtful accounts at 5% of amounts over 90 days.
C)A parking service estimates bad debts to be 10% of the value of parking violations issued. In the current year, it changes to estimating the allowance for bad debts to be equal to 20% of accounts 30 to 90 days and 50% of accounts over 90 days.
D)A shipbuilder changes its revenue recognition policy from the point of receipt by the customer to when the ship leaves the factory shipyard. This change results from a change in shipping policy from f.o.b. destination to f.o.b. shipping point. (Recall from introductory accounting that f.o.b. means "free on board," and it refers to the point at which ownership transfers from seller to buyer.)
E)An electronics retailer has never accrued for warranties or product guarantees. A new consumer protection law comes into effect, giving buyers of electronic products a guarantee against defects for 180 days after purchase and the ability to return defective products to the retailer.
F)A clothing company that has been operating for 20 years decides to obtain an external audit for the first time in order to meet the bank's demands. The audit firm recommends that management report inventories at the lower of cost and net realizable value, whereas the company has previously only tracked and reported inventory figures at cost.
(Short Answer)
4.8/5 (85)
(85) The following event occurred after the company's year-end but before the completion of the audit. For this subsequent event, determine whether the event:
•requires an adjustment to the year-end financial statements,
•requires note disclosure, or
•requires neither adjustment to recognized amounts nor disclosure.
The company experiences a major labour strike. Workers are still on strike when the audit is finished. Does your answer change if this strike might force the company into bankruptcy? (Justify your recommendation).
(Essay)
4.8/5 (59)
(59) Under the IFRS Conceptual Framework, what general information is useful for the decision making needs of lenders and investors?
(Multiple Choice)
4.9/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)