



 Chat with AI
Exam 3: Accrual Accounting

Exam 1: Fundamentals of Financial Accounting Theory33 Questions
Exam 2: Conceptual Frameworks for Financial Reporting60 Questions
Exam 3: Accrual Accounting160 Questions
Exam 4: Revenue and Recognition105 Questions
Exam 5: Cash and Receivables119 Questions
Exam 6: Inventories157 Questions
Exam 7: Financial Assets137 Questions
Exam 8: Property, Plant and Equipment127 Questions
Exam 9: Intangible Assets, Goodwill, Mineral Resources, and Government Grants81 Questions
Exam 10: Applications of Fair Value to Non-Current Assets121 Questions
Select questions type


Sing Songs Ltd. started operations on January 1, 2019. During its first year of operations, the company had a choice of accounting policies:
Accounting Option 1 Accounting Option 2 Inventory valuation FIFO Average cost Bad debt expense 7\% of sales Allowance: 20\% of losing (gross) accounts receivable Warranty expense 5\% of sales Allowance: an analysis of sales and repairs Assume that the company selected Accounting Option 2. Using the following information about activities for 2019-2021, derive the net income for each year:
2019 2020 2021 Sales (all on account) 10,500,000 13,500,000 14,100,000 Inventory purchases (paid immediately) 4,500,000 3,000,000 2,900,000 Ending inventory value: FIFO 1,800,000 2,000,000 2,150,000 Ending inventory value: Average cost 1,710,000 1,750,000 2,150,000 Collections 9,500,000 12,500,000 7,165,000 Amounts actually written off 100,000 250,000 750,000 Warranties actually paid 180,000 500,000 525,000 Estimated warranty payable ending balance based on ageing analysis of sales 385,000 525,000 700,000 Depreciation expense All other operating expenses (paid 2,500,000 2,800,000 3,000,000 mmediately)
(Essay)
4.8/5  (70)
(70) Assume that a company has a calendar year of January 1, 2021-December 31, 2021. March 15, 2022 was the end of the period for gathering information pertaining to the financial statements. The financial statements were authorized for issue on March 24, 2022. What is the cut off point for the "recognition" of transactions and events in a reporting period?
(Multiple Choice)
4.8/5 (71)
(71) McMillan Industries Ltd. reports the following transactions and events for fiscal 2020 and 2021.
a. On January 11, 2021, there was a fire and the company had insufficient fire insurance. As such a material loss will result and operations will be curtailed for the next six months.
b. The allowance for doubtful accounts (ADA)was increased in 2020 due to deteriorating economic conditions. Using the old estimate, ADA would have been $171,000. The new estimate is $184,000.
c. On December 30, 2020, there was a significant decrease of $15,000 in the market price of some inventory due to new technology. The market price is $15,000 lower than the carrying values used in fiscal 2020 statements. This occurred after the company's year-end but before the completion of the audit and issuance of the financial statements.
d. A new competitor entered the marketplace in March 2021; this will likely reduce 2021 revenues and net income.
e. In January 2021, the accountant recorded $17,000 for sales made on credit on December 28, 2020.
f. The revenue recognition policy was changed in 2020. The result is a decrease in 2019 revenue by $40,200 and a decrease in 2020 revenue by $60,300 relative to the amounts under the old policy.
g. New technology made some equipment obsolete on January 26, 2021; the fair market and salvage value have decreased by 50%. This occurred after the company's year-end but before the completion of the audit and issuance of the financial statements.
h. A major client unexpectedly went bankrupt on January 20, 2021. The company received 10% of the value of the accounts receivable as full and final settlement on February 20, 2021. This occurred after the company's year-end but before the completion of the audit and issuance of the financial statements.
i. The company has not previously needed to accrue for warranties. A new consumer protection law comes into effect in June 2021, giving buyers a guarantee against defects for 180 days after purchase and the ability to return defective products to the retailer.
Required:
For each event, determine whether it requires note disclosure or an adjustment to the 2020 financial statements. Ignore income taxes. Use the following table for your response. Justify your recommendations.
Effects in 2020, if any, (increase/decrease/no effect) Accounting requirement/explanation Assets or liabilities Equity Income
(Essay)
4.9/5 (65)
(65) Which statement is correct about the statement of comprehensive income?
(Multiple Choice)
4.8/5 (65)
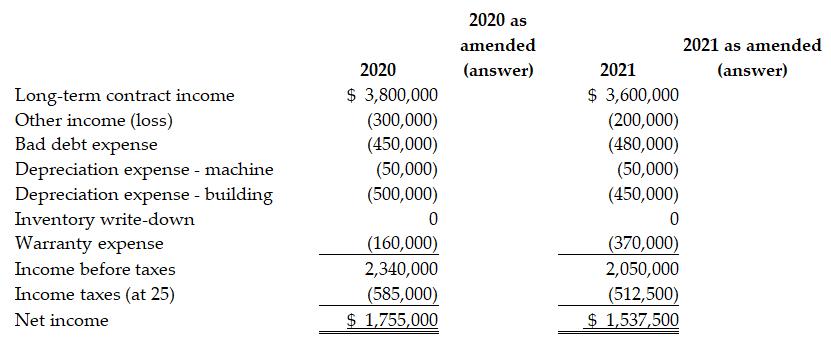
(65) Hatcher Limited, a private company, was started on January 1, 2020. For the first year, the chief accountant prepared the financial statements and a local accountant completed the necessary review of these statements. However, for the year ended December 31, 2021, an external auditor was appointed. For each situation outlined below, determine the correct accounting treatment and prepare the corrected statements of comprehensive income for 2020 and 2021.
1)Long-term contracts: Hatcher used the completed contract method for revenue recognition in 2020. Management now believes that the percentage of completion method would be better. Income under the completed contract method for 2020 was $3,800,000 and for 2021 it was $3,600,000. If the percentage of completion method had been used, the income would have been $5,800,000 (2020)and $3,400,000 (2021).
2)Accounts receivable: The accounts receivable on December 31, 2020, included a $30,000 account which was not provided for but subsequently was written off during 2021 as the customer went bankrupt after the issuance of the financial statements. Hatcher would like to adjust 2020 for this oversight as it sees this as an error.
3)Machine depreciation: Hatcher has a machine that cost $500,000 and has been depreciated over an estimated useful life of 10 years. Upon reviewing the manufacturer's reports in 2021, management now firmly believes the machine will last a total of 15 years from date of purchase. They would like to change last year's depreciation charge based on this analysis. Depreciation expense of $50,000 has been recorded for 2021.
4)Building depreciation: The company's building (cost $5,000,000, estimated salvage value $0, useful life 20 years)was depreciated last year using the 10% declining-balance method. The company and auditor now agree that the straight-line method would be a more appropriate method to use. A depreciation provision of $450,000 has been made for 2021.
5)Inventories: The accountant last year failed to apply the lower of cost or net realizable value to ending inventory. Upon review, the inventory balance for last year should have been reduced by $250,000. The closing inventory allowance for this year-end should be $370,000. No entry has been made for this.
"6)Warranties: Hatcher does not accrue for warranties; rather it records the warranty expense when amounts are paid. Hatcher provides a one-year warranty for defective goods. Payments to satisfy warranty claims in 2020 were $160,000, and $370,000 in 2021. Out of the $370,000 paid in 2021, $170,000 related to 2020 sales. A reasonable estimate of warranties payable at the end of 2021 is $270,000.
 "
" (Essay)
4.9/5 (97)
(97) 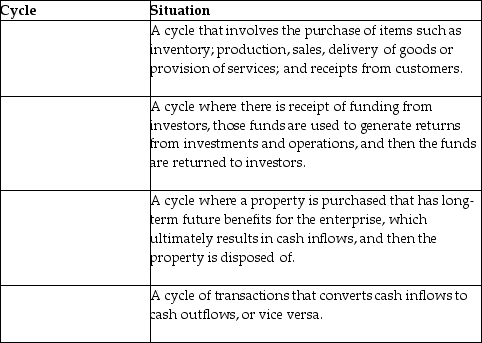
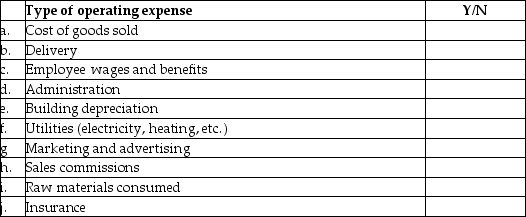
Identify whether each of the following items of operating expense is described according to its nature.
(Essay)
4.8/5 (78)
(78) The method of depreciation was changed from the double-declining-balance method to the straight-line method in fiscal 2022. A machine was purchased on January 1, 2020 at a cost of $150,000. The machine has an estimated useful life of 10 years and a residual value of $9,000. What should have been booked as depreciation expense in fiscal 2021?
(Multiple Choice)
4.9/5 (86)
(86) Which of the following would result in an overstatement in reported net income?
(Multiple Choice)
4.8/5 (81)
(81) What is the difference between accrual accounting and cash accounting?
(Essay)
4.9/5 (83)
(83) JP Corporation had net income of $1,000,000 for 2020. After issuing its financial statements, it realized that it had failed to include inventory from one of its small warehouses for several years. Specifically, it forgot to include $20,000 on December 31, 2019, and $30,000 on December 31, 2020. Which of the following is TRUE regarding JPs 2020 net income?
(Multiple Choice)
4.9/5 (81)
(81) Which statement correctly explains the relationship between cash flows, accruals and reported earnings?
(Multiple Choice)
4.9/5 (76)
(76) The method of depreciation was changed from the double-declining-balance method to the straight-line method in fiscal 2022. A machine was purchased on January 1, 2020, at a cost of $150,000. The machine has an estimated useful life of 10 years and a residual value of $9,000. What adjustment is needed for fiscal 2021?
(Multiple Choice)
4.7/5 (91)
(91) The following entry was recorded by Hollow Inc.: Cash 70,000 Accumulated depreciation 30,000 Gain on disposal of property, plant and equipment (PPE) 10,000 PPE 90,000 What is the effect on Hollow's financial statements?
(Multiple Choice)
4.9/5 (69)
(69) Identify at least one estimate that would be required in measuring the following financial statement items.
Work in process inventories Intangible assets Building Vacation pay Revenue from a 5-year construction contract
(Essay)
4.8/5 (78)
(78) Sing Songs Ltd. started operations on January 1, 2019. During its first year of operations, the company had a choice of accounting policies:
Accounting Option 1 Accounting Option 2 Inventory valuation FIFO Average cost Bad debt expense 7\% of sales Allowance: 20\% of losing (gross) accounts receivable Warranty expense 5\% of sales Allowance: an analysis of sales and repairs Assume that the company selected Accounting Option 1. Using the following information about activities for 2019-2021, derive the net income for each year:
2019 2020 2021 Sales (all on account) 10,500,000 13,500,000 14,100,000 Inventory purchases (paid 4,500,000 3,000,000 2,900,000 immediately) Ending inventory value: FIFO 1,800,000 2,000,000 2,150,000 Ending inventory value: Average cost 1,710,000 1,750,000 2,150,000 Collections 9,500,000 12,500,000 7,165,000 Amounts actually written off 100,000 250,000 750,000 Warranties actually paid 180,000 500,000 525,000 Estimated warranty payable ending balance based on ageing analysis of sales 385,000 525,000 700,000 Depreciation expense All other operating expenses (paid immediately) 2,500,000 2,800,000 3,000,000
(Essay)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)