



 Chat with AI
Exam 16: Income Taxes

Exam 1: Financial Reporting89 Questions
Exam 2: A Review of the Accounting Cycle100 Questions
Exam 3: The Balance Sheet and Notes to the Financial Statements74 Questions
Exam 4: The Income Statement86 Questions
Exam 5: Statement of Cash Flows and Articulation83 Questions
Exam 6: Earnings Management47 Questions
Exam 7: The Revenuereceivablescash Cycle87 Questions
Exam 8: Revenue Recognition89 Questions
Exam 9: Inventory and Cost of Goods Sold134 Questions
Exam 10: Investments in Noncurrent Operating Assets-Acquisition88 Questions
Exam 11: Investments in Noncurrent Operating Assets-Utilization and Retirement84 Questions
Exam 12: Debt Financing111 Questions
Exam 13: Equity Financing97 Questions
Exam 14: Investments in Debt and Equity Securities88 Questions
Exam 15: Leases83 Questions
Exam 16: Income Taxes87 Questions
Exam 17: Employee Compensation-Payroll,pensions, Other Compissues83 Questions
Exam 18: Earnings Per Share86 Questions
Exam 19: Derivatives, contingencies, business Segments, and Interim Reports82 Questions
Exam 20: Accounting Changes and Error Corrections86 Questions
Exam 21: Statement of Cash Flows Revisited68 Questions
Exam 22: Accounting in a Global Market62 Questions
Exam 23: Analysis of Financial Statements65 Questions
Select questions type


An item that would create a permanent difference in pretax financial and taxable incomes would be
(Multiple Choice)
4.9/5  (70)
(70) SFAS No 109 takes a decidedly different approach to the treatment of operating loss carryforwards.Under APB Opinion No.11,the presumption was that operating losses would not be realizable.As a result,the entity experiencing the loss would not provide for the effects of carryforwards in its financial statements until the benefits were in fact later realized for tax purposes.SFAS No.96 was even more stringent in its approach in that net deferred tax debits were prohibited to the extent they exceeded amounts which would be recoverable through operating loss carrybacks as of the date of the balance sheet.SFAS No.109 treats net operating loss carryforwards in the same manner as the tax effects of other deductible temporary differences and allow both to be recognized as deferred tax assets.The approach of SFAS No.109 has been criticized by some,however.
Required:
Identify what you perceive to be the weaknesses in the approach promulgated by SFAS No.109.
(Essay)
4.9/5 (85)
(85) Analysis of the assets and liabilities of Baxter Corp.on December 31,2014,disclosed assets with a tax basis of $1,000,000 and a book basis of $1,300,000.There was no difference in the liability basis.The difference in asset basis arose from temporary differences that would reverse in the following years:
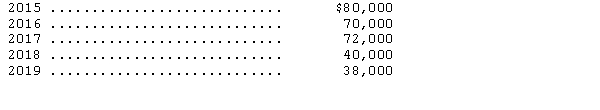 The enacted tax rates are 30 percent for the years 2014-2017 and 35 percent for 2018-2019.The total deferred tax liability on December 31,2014,should be
 (Multiple Choice)
4.9/5 (74)
(74) The Morris Corporation reported a $59,000 operating loss in 2014.In the preceding three years,Morris reported the following income before taxes and paid the indicated income taxes:
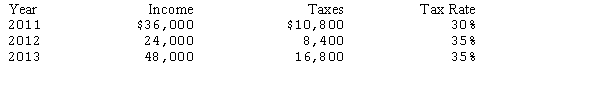 The amount of tax benefit to be reported in 2014 arising from the tax carryback provisions of the current tax code would be
 (Multiple Choice)
4.7/5 (72)
(72) Eastwood Manufacturing planned to claim a $10,000 credit for increasing research activities (an R & D credit)on its 2014 income tax return.Although some portion of the credit is at risk,management believes that it is "more likely than not" that the reporting entity will qualify for all or a portion of the R & D credit.As a result,recognition will be limited to only a portion of the amount claimed on the Company's income tax return.
Given that the credit meets the more-likely-than-not threshold,management must measure
the amount to be recognized.Accordingly,management has estimated the range of possible outcomes regarding the amount of the credit to be allowed,and the related likelihoods,as follows:
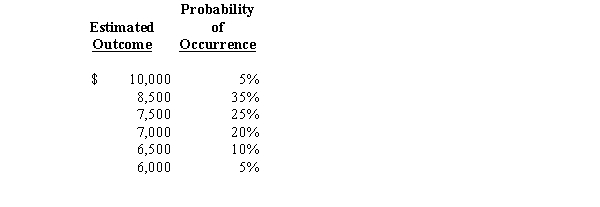 Required:
1.Determine the amount of the tax position that would be recognized in Eastwood Manufacturing's financial statements.
2.Determine the amount of the liability for unrecognized income tax benefits that would appear on Eastwood Manufacturing's balance sheet.
Required:
1.Determine the amount of the tax position that would be recognized in Eastwood Manufacturing's financial statements.
2.Determine the amount of the liability for unrecognized income tax benefits that would appear on Eastwood Manufacturing's balance sheet. (Essay)
4.9/5 (75)
(75) Smart Services computed pretax financial income of $220,000 for its first year of operations ended December 31,2014.In preparing the income tax return for the year,the tax accountant determined the following differences between 2014 financial income and taxable income:
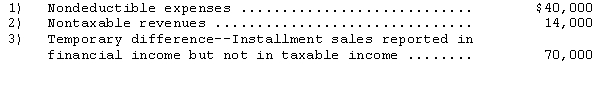 The temporary difference is expected to reverse in the following pattern:
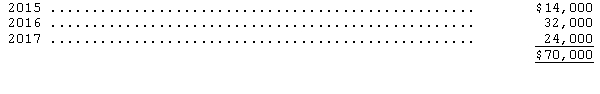 The enacted tax rates for this year and the next three years are as follows:
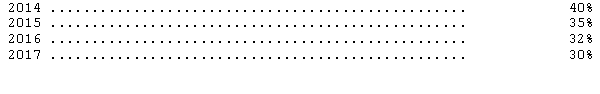 Use the provisions of FASB Statement No.109.
(1)Prepare a schedule showing the reversal of the temporary differences and the computation of income taxes payable and deferred tax assets or liabilities as of December 31,2014.
(2)Prepare journal entries to record income taxes payable and deferred income taxes.
(3)Prepare the income statement for Smart Services beginning with "Income from continuing operations before income taxes" for the year ended December 31,2014.
The temporary difference is expected to reverse in the following pattern:
The enacted tax rates for this year and the next three years are as follows:
Use the provisions of FASB Statement No.109.
(1)Prepare a schedule showing the reversal of the temporary differences and the computation of income taxes payable and deferred tax assets or liabilities as of December 31,2014.
(2)Prepare journal entries to record income taxes payable and deferred income taxes.
(3)Prepare the income statement for Smart Services beginning with "Income from continuing operations before income taxes" for the year ended December 31,2014. (Essay)
4.9/5 (92)
(92) When enacted tax rates change,the asset and liability method of interperiod tax allocation recognizes the rate change as
(Multiple Choice)
4.8/5 (82)
(82) Which of the following could never be subject to interperiod tax allocation?
(Multiple Choice)
4.7/5 (80)
(80) Which of the following items results in a temporary difference deductible amount for a given year?
(Multiple Choice)
4.9/5 (82)
(82) Bailey Company has a deferred tax asset of $1,000,000 at December 31,2014.This amount arises from the recording of the company's liability for postretirement benefits other than pensions.The company's CPA has asked management whether a valuation allowance should be recorded to reduce the deferred tax asset to zero
Required:
1.Why would Bailey not want to report a valuation allowance?
2.What evidence might the company offer to argue against recording a valuation allowance?
3.Assume that the company determines that a valuation allowance of $400,000 is required.How would the company have arrived at this determination,and what effect will it have on net income for fiscal 2014?
(Essay)
4.8/5 (91)
(91) The following differences between financial and taxable income were reported by Angostura Corporation for the current year:
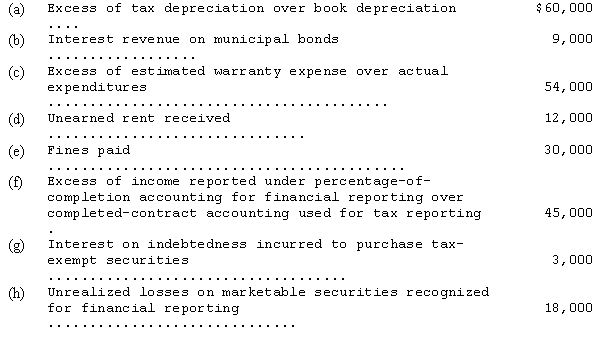 Assume that Angostura Corporation had pretax accounting income [before considering items (a)through (h)] of $900,000 for the current year.Compute the taxable income for the current year.
 (Essay)
4.9/5 (86)
(86) Concourse Corporation paid $20,000 in January of 2014 for premiums on a two- year life insurance policy which names the company as the beneficiary.Additionally,Concourse Corporation's financial statements for the year ended December 31,2014,revealed the company paid $105,000 in taxes during the year and also accrued estimated litigation losses of $200,000.Assuming the lawsuit was resolved in February of 2015 (at which time a $200,000 loss was recognized for tax purposes)and that Concourse's tax rate is 30 percent for both 2014 and 2015,what amount should Concourse report as asset for net deferred income taxes on its 2014 balance sheet?
(Multiple Choice)
4.8/5 (82)
(82) Which of the following is the most likely item to result in a deferred tax asset?
(Multiple Choice)
4.7/5 (78)
(78) The notes to the 2014 financial statements of Halvoline Oil Company provide the following disclosure regarding the deferred tax asset and liability accounts at December 31,2014 (amounts in millions of dollars):
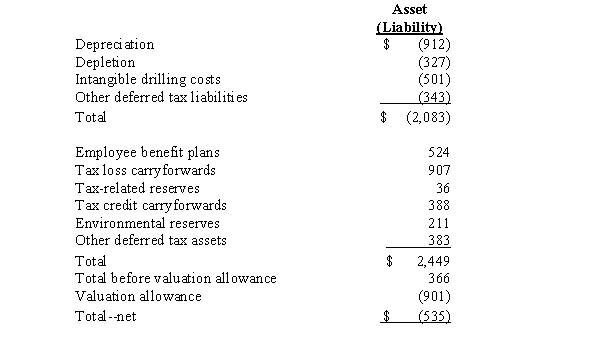 Required:
1.What is the total amount of deferred liability at December 31,2014? What is the total amount of deferred tax asset? What is the net amount of the deferred tax asset or liability?
2.Assuming a federal tax rate of 35 percent,estimate the temporary difference arising from depreciation that exists for Halvoline at December 31,2014.
3.On December 31,2014,Halvoline shows a noncurrent liability on its balance sheet,captioned "deferred income taxes",in the amount of $634 million.What other deferred tax account,if any is included in the balance sheet? What is the amount of this other deferred tax account?
Required:
1.What is the total amount of deferred liability at December 31,2014? What is the total amount of deferred tax asset? What is the net amount of the deferred tax asset or liability?
2.Assuming a federal tax rate of 35 percent,estimate the temporary difference arising from depreciation that exists for Halvoline at December 31,2014.
3.On December 31,2014,Halvoline shows a noncurrent liability on its balance sheet,captioned "deferred income taxes",in the amount of $634 million.What other deferred tax account,if any is included in the balance sheet? What is the amount of this other deferred tax account? (Essay)
4.7/5 (72)
(72) Amengual Corporation began operations in 2011 and had operating losses of $400,000 in 2012 and $300,000 in 2013.For the year ended December 31,2014,Amengual had a pretax financial income of $600,000.For 2012 and 2013,assume an enacted tax rate of 30 percent,and for 2014 a 35 percent tax rate.There were no temporary differences in any of the years.In Amengual's 2014 income statement,how much should be reported as income tax expense?
(Multiple Choice)
4.9/5 (80)
(80) SFAS No.109 uses the term "tax-planning strategy".The meaning of this term in the pronouncement is somewhat different from its usage in ordinary business conversation.Typically,one would expect the term tax-planning strategy to connote the actions management takes to minimize the enterprise's long-run tax obligation.An enterprise may,for example,structure its credit sales activities such that these sales would qualify for treatment as installment sales for tax purposes.Such an approach would allow the deferral of taxable revenue until cash is actually received.The use of the term tax-planning strategy in SFAS No.109 differs from the traditional use,however.
Required:
Explain the meaning of the term "tax-planning strategy" as the term is used in SFAS No.109.
(Essay)
5.0/5 (75)
(75) Allsgood Appliances computed a pretax financial loss of $60,000 for the first year of its operations ended December 31,2014.Analysis of the tax and book basis of its liabilities disclosed $80,000 in accrued warranty expenses on the books that had not been deductible from taxable income in 2014,but would be deductible in future years when the warranty expenses were paid.
The future warranty payments are expected to occur in the following pattern:
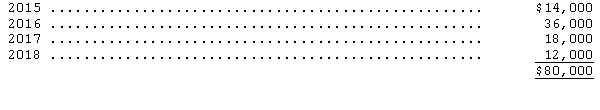 The enacted tax rates for this year and the next four years are as follows:
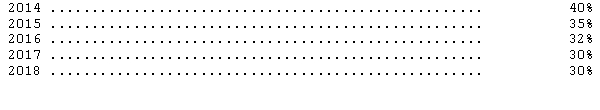 Use the provisions of FASB Statement No.109.
(1)Prepare a schedule showing the reversal of the temporary difference and the computation of income taxes payable and deferred tax assets or liabilities as of December 31,2014.
(2)Prepare journal entries to record income taxes payable and deferred income taxes.
(3)Prepare the income statement for Allsgood beginning with "Income from continuing operations before income taxes" for the year ended December 31,2014.
The enacted tax rates for this year and the next four years are as follows:
Use the provisions of FASB Statement No.109.
(1)Prepare a schedule showing the reversal of the temporary difference and the computation of income taxes payable and deferred tax assets or liabilities as of December 31,2014.
(2)Prepare journal entries to record income taxes payable and deferred income taxes.
(3)Prepare the income statement for Allsgood beginning with "Income from continuing operations before income taxes" for the year ended December 31,2014. (Essay)
4.8/5 (80)
(80) Alpha had taxable income of $1,500 during 2014.Alpha used accelerated depreciation for tax purposes ($2,000)and straight-line depreciation for financial reporting purposes ($800).On December 30,2014,Alpha collected the January 2015 rent of $600 on a lot it rents on a month-by-month basis to Zenith.Alpha's pretax accounting income for 2014 would be
(Multiple Choice)
4.9/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)