



 Chat with AI
Exam 16: Income Taxes

Exam 1: Financial Reporting89 Questions
Exam 2: A Review of the Accounting Cycle100 Questions
Exam 3: The Balance Sheet and Notes to the Financial Statements74 Questions
Exam 4: The Income Statement86 Questions
Exam 5: Statement of Cash Flows and Articulation83 Questions
Exam 6: Earnings Management47 Questions
Exam 7: The Revenuereceivablescash Cycle87 Questions
Exam 8: Revenue Recognition89 Questions
Exam 9: Inventory and Cost of Goods Sold134 Questions
Exam 10: Investments in Noncurrent Operating Assets-Acquisition88 Questions
Exam 11: Investments in Noncurrent Operating Assets-Utilization and Retirement84 Questions
Exam 12: Debt Financing111 Questions
Exam 13: Equity Financing97 Questions
Exam 14: Investments in Debt and Equity Securities88 Questions
Exam 15: Leases83 Questions
Exam 16: Income Taxes87 Questions
Exam 17: Employee Compensation-Payroll,pensions, Other Compissues83 Questions
Exam 18: Earnings Per Share86 Questions
Exam 19: Derivatives, contingencies, business Segments, and Interim Reports82 Questions
Exam 20: Accounting Changes and Error Corrections86 Questions
Exam 21: Statement of Cash Flows Revisited68 Questions
Exam 22: Accounting in a Global Market62 Questions
Exam 23: Analysis of Financial Statements65 Questions
Select questions type


The Internal Revenue Code allows a corporation to carry back or carry forward an operating loss occurring in a given year.
Required:
1.Explain the nature of an operating loss carryback and a carryforward and the effect of each of these actions.
2.Summarize the current generally accepted accounting principles for the financial reporting of operating loss carrybacks and for reporting operating loss carryforwards.
3.Explain why an entity might forgo the opportunity to obtain a tax refund with a carryback,choosing instead to utilize the carryforward-only option.
(Essay)
4.9/5  (74)
(74) A company would most likely choose the carryforward option for a net operating loss if the company expected
(Multiple Choice)
4.7/5 (85)
(85) A major conceptual issue associated with interperiod tax allocation is the issue of discounting the deferred tax amount on the balance sheet to reflect its present value.Current generally accepted accounting principles do not allow the discounting of deferred taxes.Some in the profession have suggested,however,that the FASB should reconsider its position on discounting in light of the Board's current project on present value-based measurements in accounting.
Provide arguments for and against the discounting of deferred income taxes.
(Essay)
4.9/5 (75)
(75) For the current year,Southern Cross Company reported income tax expense of $45,000.Income taxes payable at the end of the prior year were $20,000 and at the end of the current year were $27,000.The deferred tax liability classified as noncurrent that resulted from the use of MACRS for tax purposes and straight-line depreciation for financial reporting purposes increased from $18,000 at the beginning of the current year to $23,000 at the end of the current year.How much cash was paid for income taxes during the year?
(Multiple Choice)
4.9/5 (77)
(77) If all temporary differences entering into the determination of pretax accounting income are considered in the computation of deferred taxes and income tax expense,then the
(Multiple Choice)
4.7/5 (75)
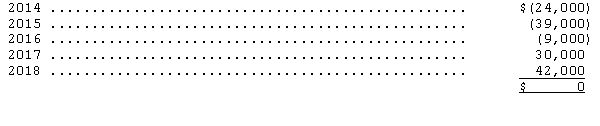
(75) Oriole Industries computed a pretax financial income of $118,500 for the first year of its operations ended December 31,2014.Oriole uses an accelerated cost recovery method on its tax return,and straight-line depreciation on its books.
The difference between the tax and book deduction for depreciation over the five-year life of the assets acquired in 2014 are as follows:
 The enacted tax rates for this year and the next four years are as follows:
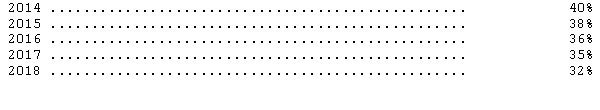 Use the provisions of FASB Statement No.109 and assume that it is more likely than not that income will be sufficient in all future years to realize any deductible amounts.
(1)Prepare a schedule showing the pattern of depreciation differences,the computation of income taxes payable,and deferred tax assets or liabilities as of December 31,2014.
(2)Prepare journal entries to record income taxes payable and deferred income taxes.
(3)Prepare the income statement for Oriole Industries beginning with "Income from continuing operations before income taxes" for the year ended December 31,2014.
The enacted tax rates for this year and the next four years are as follows:
Use the provisions of FASB Statement No.109 and assume that it is more likely than not that income will be sufficient in all future years to realize any deductible amounts.
(1)Prepare a schedule showing the pattern of depreciation differences,the computation of income taxes payable,and deferred tax assets or liabilities as of December 31,2014.
(2)Prepare journal entries to record income taxes payable and deferred income taxes.
(3)Prepare the income statement for Oriole Industries beginning with "Income from continuing operations before income taxes" for the year ended December 31,2014. (Essay)
4.8/5 (81)
(81) SFAS No.109 allows the recognition of deferred tax assets for both operating loss carryforwards and temporary differences arising from normal operations.This provision of SFAS No.109 represents a significant change from the requirements of SFAS No.96 and APB Opinion No.11 in which stringent limits were placed on the recognition of deferred tax assets.SFAS No.109 does require some recognition of the uncertainty associated with deferred tax assets,however.
Required:
Explain how SFAS No.109 addresses uncertainty associated with deferred tax assets and how the approach in SFAS No.109 compares with the approach adopted in SFAS No.5 regarding contingencies.
(Essay)
5.0/5 (62)
(62) Which of the following is NOT a source of support for the realization of a deferred tax asset?
(Multiple Choice)
4.8/5 (77)
(77) During a year,Awesome Company reported income tax expense of $300,000.The amount of taxes currently payable remained unchanged from the beginning to the end of the year.The deferred tax liability classified as noncurrent that resulted from the use of MACRS for tax purposes and straight-line depreciation for financial reporting purposes,increased from $40,000 at the beginning of the year to $44,000 at the end of the year.How much cash was paid for income taxes during for the year?
(Multiple Choice)
4.8/5 (83)
(83) Which of the following items results in a temporary difference taxable amount for a given year?
(Multiple Choice)
5.0/5 (85)
(85) The statutory federal tax rate of Yolanda Company has been 35 percent for a number of years.Late in the third quarter of 2014,a new rate of 40 percent was approved as the new statutory tax rate,effective as of January 1,2014.The CEO of the Yolanda is concerned about what effect,if any,the new tax rate will have on 2014 earnings.
At the beginning of the year,Yolanda had a deferred tax asset of $10 million and a deferred tax liability of $6 million.A valuation allowance was not needed and it is not expected that a valuation allowance will be needed this year.Pretax accounting income is estimated to be approximately $5 million for 2014 and taxable income will be about $7 million.Yolanda is a publicly traded company with 500,000 shares outstanding throughout the entire year.
Required:
1.Explain the effect of the tax rate increase on the balance sheet and income statement of the company for 2014,with particular attention to the effect the change will have on earnings per share.
2.If the effect is expected to be negative,provide recommendations regarding actions the company might consider during the last few days of 2014 to minimize the impact.
3.Explain the effect the tax rate change might have on the company's stock price.
(Essay)
4.8/5 (84)
(84) Recognizing tax benefits in a loss year due to a loss carryforward requires
(Multiple Choice)
4.9/5 (83)
(83) On the statement of cash flows using the indirect method,an increase in the deferred tax liability would be shown as
(Multiple Choice)
4.8/5 (85)
(85) The following information was taken from Caribbean Corporation's 2014 income statement:
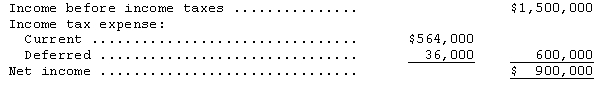 Caribbeans' first year of operations was 2014.The company has a 30 percent tax rate.Management decided to use accelerated depreciation for tax purpose and the straight-line method of depreciation for financial reporting purposes.The amount charged to depreciation expense in 2014 was $600,000.Assuming no other differences existed between book income and taxable income,what amount did Caribbean deduct for depreciation on its tax return for 2014?
 (Multiple Choice)
4.9/5 (76)
(76) In 2014,The Xavier Company,reported pretax financial income of $400,000.Included in that pretax financial income was $90,000 of nontaxable life insurance proceeds received as a result of the death of an officer; $120,000 of warranty expenses accrued but unpaid as of December 31,2014; and $30,000 of life insurance premiums for a policy for an officer.Assuming that no income taxes were previously paid during the year and assuming an income tax rate of 40 percent,the amount of income taxes payable on December 31,2014,would be
(Multiple Choice)
4.7/5 (74)
(74) During 2014,Epsilon Company had pretax accounting income of $620.Epsilon's only temporary difference for 2014 was the collection of a receivable that resulted in $220 of income under the installment sales method of revenue recognition that Epsilon uses for tax purposes.The sale was originally made in 2012 and recognized for accounting purposes at that time.Epsilon's taxable income for 2014 would be
(Multiple Choice)
4.8/5 (78)
(78) Which of the following is an example of a temporary difference that would result in a deferred tax liability?
(Multiple Choice)
4.8/5 (72)
(72) For the current year,Phoenix Company reported income tax expense of $195,000.Income taxes payable at the end of the prior year were $125,000 and at the end of the current year were $130,000.The deferred tax liability classified as noncurrent that resulted from the use of MACRS for tax purposes and straight-line depreciation for financial reporting purposes increased from $120,000 at the beginning of the current year to $123,000 at the end of the current year.How much cash was paid for income taxes during the year?
(Multiple Choice)
4.8/5 (85)
(85) A major conceptual issue regarding the accounting for income taxes is the recognition of income taxes as expenses.Some would argue that income taxes are not directly related to revenues or revenue-seeking functions and should not be considered as expenses.Some view income taxes as a distribution of income similar to dividends.This view would hold that income taxes,like dividends,are paid only if income is earned.Wages and supplies,on the other hand,are paid for whether the entity earns a profit or incurs a loss.
Identify arguments that can be made for recognizing income tax as an expense on the income statement.
(Essay)
4.9/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)