



 Chat with AI
Exam 14: Exempt Entities

Exam 1: Understanding and Working With the Federal Tax Law72 Questions
Exam 2: Corporations: Introduction and Operating Rules103 Questions
Exam 3: Corporations: Special Situations76 Questions
Exam 4: Corporations: Organization and Capital Structure91 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions82 Questions
Exam 6: Corporations: Redemptions and Liquidations107 Questions
Exam 7: Corporations: Reorganizations138 Questions
Exam 8: Consolidated Tax Returns143 Questions
Exam 9: Taxation of International Transactions142 Questions
Exam 10: Partnerships: Formation, operation, and Basis71 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations84 Questions
Exam 12: S Corporations161 Questions
Exam 13: Comparative Forms of Doing Business139 Questions
Exam 14: Exempt Entities159 Questions
Exam 15: Multistate Corporate Taxation169 Questions
Exam 16: Tax Practice and Ethics147 Questions
Exam 17: The Federal Gift and Estate Taxes199 Questions
Exam 18: Family Tax Planning168 Questions
Exam 19: Income Taxation of Trusts and Estates155 Questions
Select questions type


For an activity to be considered as regularly carried on for purposes of the unrelated business income tax,the activity must be conducted during the work week (i.e.,activities performed on the weekend are not considered in determining if the activity is regularly carried on).
(True/False)
4.8/5  (87)
(87) The due date for both Form 990 (Return of Organization Exempt from Income Tax)and Form 990-PF (Return of Private Foundation)is the fifteenth day of the fifth month after the end of the taxable year.
(True/False)
5.0/5 (82)
(82) Personal property rental income is subject to and real property rental income is not subject to the unrelated business income tax.
(True/False)
4.9/5 (84)
(84) Match the following statements.
a.Carries on a trade or business for the benefit of an exempt organization, remits its profits to the exempt organization, and is not exempt from Federal income tax.
b.May be subject to some Federal income taxation and classification may adversely affect amount of charitable contributions received.
c.Tax imposed for engaging in transactions with disqualified persons.
d.Enables certain exempt organizations to engage in lobbying activities on a limited basis.
e.Tax imposed on investments that enable a private foundation to control unrelated businesses.
-Private foundation
(Short Answer)
4.9/5 (86)
(86) How can an exempt organization,otherwise classified as a private foundation,avoid private foundation status?
(Essay)
4.7/5 (69)
(69) The excise taxes such as the tax on self-dealing and the tax on excess business holdings are imposed only on exempt organizations classified as private foundations.
(True/False)
4.7/5 (77)
(77) Discuss any negative tax consequences that result from an exempt organization being classified as a private foundation.
(Essay)
4.9/5 (82)
(82) The Dispensary is a pharmacy that is part of a § 501(c)(3)hospital.Its primary mission is to dispense medicines for hospital patients.In addition,the pharmacy dispenses medicines to former hospital patients for a period of up to 30 days after discharge from the hospital.It does this for the dual purpose of convenience to the former patients (i.e.,the closest pharmacy is 6 miles away),and to ensure that the former patients receive the medicines that have been prescribed for them.
The Dispensary carefully carries out the policy of the hospital board that no more than 25% of its gross revenues come from former-patient medicine sales.If necessary,in December of each year,sales to former patients are curtailed to assure compliance with this policy.Sales revenue from each of the two sources is as follows for 2008.
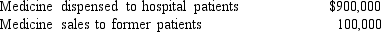 Calculate the amount of The Dispensary's unrelated business gross income.
 (Essay)
4.7/5 (102)
(102) For each of the following taxes which are imposed on private foundations, match the appropriate initial tax or additional tax.
a.5% initial tax and 25% additional tax on private foundation.
b.15% initial tax and 100% additional tax on private foundation.
c.100% additional tax on private foundation and 50% additional tax on foundation manager.
d.5% initial tax and 200% additional tax on private foundation.
e.5% initial tax and 200% additional tax on the disqualified person.
-Tax on excess business holdings
(Short Answer)
4.7/5 (76)
(76) A feeder organization is exempt from Federal income taxation because it carries on a trade or business for the benefit of an exempt organization and remits its profits to the exempt entity.
(True/False)
4.9/5 (72)
(72) A profit-related activity of an exempt organization avoids the unrelated business income tax if at least 80% of the merchandise sold had been received as a contribution.
(True/False)
4.9/5 (80)
(80) Match the following statements.
a.Exempt from tax on unrelated business.
b.Inappropriate definition.
c.Exempt organization may be subject to the tax on unrelated business income.
d.Annual information return of an exempt organization which is not a private foundation.
e.Appropriate definition.
f.Annual information return of a private foundation.
-Unrelated business income is generally that derived from the unrelated trade or business,reduced by the deductions directly connected with the conduct of the unrelated trade or business.
(Short Answer)
4.7/5 (91)
(91) An exempt organization is located in the state of Nevada.Gambling in Nevada is legal.Therefore,bingo games are conducted by both taxable and tax-exempt organizations.If the net earnings from the bingo games are less than $25,000,the exempt organization is not subject to the unrelated business income tax (UBIT).
(True/False)
4.9/5 (83)
(83) Hope,Inc.,an exempt organization,owns a factory building that it leases to a taxable corporation for $100,000 per year.Related expenses for Hope are $30,000.Hope's average acquisition indebtedness on the building is $400,000 and the average adjusted basis is $600,000.Calculate Hope's unrelated debt-financed income and expenses.Then indicate the effect of these items on unrelated business taxable income.
(Essay)
4.8/5 (73)
(73) Which of the following are consequences of tax-exempt status?
(Multiple Choice)
4.8/5 (74)
(74) An exempt organization which is subject to any of the excise taxes imposed on private foundations must file Form 4720 (Return of Certain Excise Taxes on Charities and Other Persons).
(True/False)
4.9/5 (87)
(87) Help,Inc.,a tax-exempt organization,incurs lobbying expenses of $275,000 during the tax year.Help is eligible for and makes the § 501(h)lobbying expenditure election.During the year,Help spends $1,200,000 carrying out its exempt mission.
a.Will the lobbying expense result in Help losing its exempt status?
b.Calculate the amount of any tax that Help must pay associated with its lobbying expenses.
(Essay)
4.8/5 (84)
(84) Is there a materiality exception associated with the unrelated business income tax?
(Essay)
4.8/5 (87)
(87) Match the following statements.
a.Carries on a trade or business for the benefit of an exempt organization, remits its profits to the exempt organization, and is not exempt from Federal income tax.
b.May be subject to some Federal income taxation and classification may adversely affect amount of charitable contributions received.
c.Tax imposed for engaging in transactions with disqualified persons.
d.Enables certain exempt organizations to engage in lobbying activities on a limited basis.
e.Tax imposed on investments that enable a private foundation to control unrelated businesses.
-§ 501(h)election
(Short Answer)
4.7/5 (70)
(70) Faith Church,a § 501(c)(3)organization,operates a bingo game two times each week to raise money to support the youth activities of the church.For the current year,net proceeds from the bingo game are $900,000.
a.Determine the tax consequences for Faith Church if the bingo game is conducted in a state where for-profit bingo games are illegal, and where the bingo game is legal for exempt entities.
b.Determine the tax consequences for Faith Church if the bingo game is conducted in a state and locality where bingo games are legal for both for-profit and exempt entities.
(Essay)
5.0/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)