



 Chat with AI
Exam 12: S Corporations

Exam 1: Understanding and Working With the Federal Tax Law72 Questions
Exam 2: Corporations: Introduction and Operating Rules103 Questions
Exam 3: Corporations: Special Situations76 Questions
Exam 4: Corporations: Organization and Capital Structure91 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions82 Questions
Exam 6: Corporations: Redemptions and Liquidations107 Questions
Exam 7: Corporations: Reorganizations138 Questions
Exam 8: Consolidated Tax Returns143 Questions
Exam 9: Taxation of International Transactions142 Questions
Exam 10: Partnerships: Formation, operation, and Basis71 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations84 Questions
Exam 12: S Corporations161 Questions
Exam 13: Comparative Forms of Doing Business139 Questions
Exam 14: Exempt Entities159 Questions
Exam 15: Multistate Corporate Taxation169 Questions
Exam 16: Tax Practice and Ethics147 Questions
Exam 17: The Federal Gift and Estate Taxes199 Questions
Exam 18: Family Tax Planning168 Questions
Exam 19: Income Taxation of Trusts and Estates155 Questions
Select questions type


Any distribution of cash or property by a corporation with respect to the stock during a post-termination transition period of approximately one year is applied against and reduces the adjusted basis of the stock.
(True/False)
4.8/5  (89)
(89) On distribution of loss property,an S corporation receives a step-down in basis.
(True/False)
4.8/5 (82)
(82) The carryover period for the NOLs of a C corporation continues to run during S corporation years.
(True/False)
4.8/5 (84)
(84) Chris,the sole shareholder of Taylor,Inc.,elects during 2008 to terminate the S election,effective January 1,2009.As of the end of 2008,Taylor,Inc.,has AAA of $120,000 and OAA of $13,000.Chris receives a cash dividend of $130,000 on January 15,2009.If his stock basis is $220,000 before the distribution,calculate Chris' taxable amount and his ending stock basis.
(Essay)
4.7/5 (86)
(86) An S election made before becoming a corporation is valid the next 12-month tax year.
(True/False)
4.9/5 (84)
(84) You are given the following facts about a 50% owner of an S corporation,and you are asked to prepare his ending stock basis.
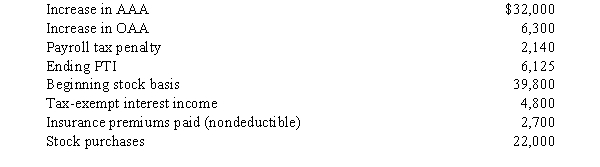
(Multiple Choice)
4.9/5 (95)
(95) An S corporation does not recognize a loss when distributing assets that are worth less than their basis.
(True/False)
4.8/5 (80)
(80) For a new corporation,a premature S election may not be effective.
(True/False)
4.9/5 (82)
(82) Which of the following items are increases on Schedule M-3 on the Form 1120S,for an S corporation with $230,000 in ordinary income?
(Multiple Choice)
4.8/5 (73)
(73) Match the term with the proper response. There may be more than one responses for each term.
a.Includes gross receipts derived from royalties, passive rents, dividends, interest, etc.
b.Penalty tax to stop an S corporation from avoiding the corporate tax on disposition of appreciated property.
c.Cumulative total of undistributed non-separately stated items.
d.Tax-free distribution.
e.Generated under old S corporation rules (pre-1983).
f.Items that affect basis but not AAA go here.
g.Taxed as a dividend.
-PTI
(Short Answer)
4.9/5 (71)
(71) Life insurance proceeds received and insurance premiums paid are traced through ____________________.
(Short Answer)
4.7/5 (85)
(85) The debt basis always is adjusted back to the original amount before any increase is made in the stock basis.
(True/False)
4.8/5 (87)
(87) The pro rata method assigns an equal amount of each of the S corporation items (e.g.,LTCG)to each day of the year.
(True/False)
4.8/5 (80)
(80) AAA is the _________________________ total of undistributed non-separately and separately stated items for S corporation taxable years beginning after 1982.
(Short Answer)
4.8/5 (87)
(87) Post-termination distributions that are charged against OAA get tax-free treatment.
(True/False)
4.8/5 (80)
(80) Dawn Adams owns 60% of a calendar year S corporation during 2008.Her stock basis on December 31,2007 is $17,000,and her debt basis is $2,000.If the S corporation incurs a $48,000 loss for 2008,what amount may Ms.Adams deduct on her individual tax return?
(Essay)
4.9/5 (82)
(82) An S shareholder's basis includes a ratable share of any S corporation liabilities.
(True/False)
4.9/5 (67)
(67) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)