



 Chat with AI
Exam 4: Corporations: Organization and Capital Structure

Exam 1: Understanding and Working With the Federal Tax Law72 Questions
Exam 2: Corporations: Introduction and Operating Rules103 Questions
Exam 3: Corporations: Special Situations76 Questions
Exam 4: Corporations: Organization and Capital Structure91 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions82 Questions
Exam 6: Corporations: Redemptions and Liquidations107 Questions
Exam 7: Corporations: Reorganizations138 Questions
Exam 8: Consolidated Tax Returns143 Questions
Exam 9: Taxation of International Transactions142 Questions
Exam 10: Partnerships: Formation, operation, and Basis71 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations84 Questions
Exam 12: S Corporations161 Questions
Exam 13: Comparative Forms of Doing Business139 Questions
Exam 14: Exempt Entities159 Questions
Exam 15: Multistate Corporate Taxation169 Questions
Exam 16: Tax Practice and Ethics147 Questions
Exam 17: The Federal Gift and Estate Taxes199 Questions
Exam 18: Family Tax Planning168 Questions
Exam 19: Income Taxation of Trusts and Estates155 Questions
Select questions type


Three individuals form Skylark Corporation with the following contributions: Cliff,cash of $50,000 for 50 shares; Brad,land worth $20,000 (basis of $11,000)for 20 shares; and Ron,cattle worth $9,000 (basis of $6,000)for 9 shares and services worth $21,000 for 21 shares.
(Multiple Choice)
4.8/5  (80)
(80) In structuring the capitalization of a corporation,the tax law is neutral for the investor as to debt versus equity financings.
(True/False)
4.8/5 (83)
(83) Carl transfers land to Cardinal Corporation for 90% of the stock in Cardinal Corporation worth $20,000 plus a note payable to Carl in the amount of $40,000 and the assumption by Cardinal Corporation of a mortgage on the land in the amount of $100,000.The land,which has a basis to Carl of $70,000,is worth $160,000.
(Multiple Choice)
4.8/5 (85)
(85) When a taxpayer transfers property subject to a mortgage to a controlled corporation in an exchange qualifying under § 351,the transferor shareholder's basis in stock received in the transferee corporation is increased by the amount of the mortgage on the property.
(True/False)
4.9/5 (78)
(78) In determining whether § 357(c)applies,assess whether the liabilities involved exceed the bases of all assets a shareholder transfers to the corporation.
(True/False)
4.9/5 (68)
(68) Dawn,a sole proprietor,was engaged in a service business and reported her income on a cash basis.Later,she incorporates her business and transfers the assets of the business to the corporation in return for all the stock in the corporation plus the corporation's assumption of the liabilities of her proprietorship.All the receivables and the unpaid trade payables are transferred to the newly formed corporation.The assets of the proprietorship had a basis of $105,000 and fair market value of $300,000.The trade accounts payable totaled $25,000.There was a note payable to the bank in the amount of $95,000 that the corporation assumes.The note was issued for the purchase of computers and other business equipment.
(Multiple Choice)
4.9/5 (71)
(71) Paul,a cash basis taxpayer,incorporates his sole proprietorship.He transfers the following items to newly created Wren Corporation.
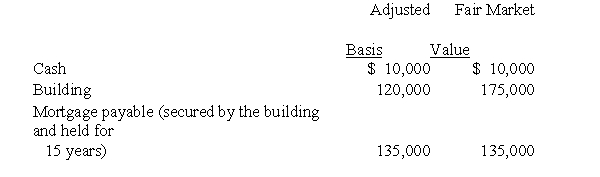 With respect to this transaction:
 (Multiple Choice)
4.9/5 (68)
(68) Sarah and Tony (mother and son)form Dove Corporation with the following investments: cash by Sarah of $55,000; land by Tony (basis of $35,000 and fair market value of $45,000).Dove Corporation issues 200 shares of stock,100 each to Sarah and Tony.Thus,each receives stock in Dove worth $50,000.
(Multiple Choice)
4.9/5 (79)
(79) In order to retain the services of Eve,a key employee in Ted's sole proprietorship,Ted contracts with Eve to make her a 30% owner.Ted incorporates the business receiving in return 100% of the stock.Three days later,Ted transfers 30% of the stock to Eve.Under these circumstances,§ 351 will not apply to the incorporation of Ted's business.
(True/False)
4.9/5 (84)
(84) Rosa,the sole shareholder of Robin Corporation,contributes land (basis of $40,000 and fair market value of $100,000)to the corporation but does not receive additional stock. Neither Rosa nor Robin Corporation will have to recognize gain as a result of this transfer.
(True/False)
4.9/5 (79)
(79) The receipt of nonqualified preferred stock in exchange for the transfer of appreciated property to a controlled corporation results in recognition of gain to the transferor.
(True/False)
4.8/5 (70)
(70) Gabriella and Juanita form Luster Corporation. Gabriella transfers cash of $50,000 for 50 shares of stock,while Juanita transfers a secret process (basis of zero; fair market value of $50,000)for 50 shares of stock. Neither Gabriella nor Juanita will recognize gain on the transfer.
(True/False)
4.9/5 (88)
(88) Issues relating to basis arise when a taxpayer is involved in a § 351 transaction.Describe the underlying basis rules,and the purpose they serve.
(Essay)
4.8/5 (75)
(75) Barry and Irv form Swift Corporation. Barry transfers cash of $100,000 and equipment (basis of $300,000 and fair market value of $400,000)for 50% of Swift's stock. Irv transfers land and building (basis of $510,000 and fair market value of $450,000)and agrees to manage the business for one year for the other 50% of Swift's stock. The value of Irv's services for one year is $50,000.
a.What is Barry's recognized gain? Basis in the Swift Corporation stock?
b.What are the tax consequences to Irv?
c.What are the tax consequences to Swift Corporation?
(Essay)
4.8/5 (85)
(85) Similar to like-kind exchanges,the receipt of "boot" under § 351 can cause gain to be recognized.
(True/False)
4.8/5 (81)
(81) Amy owns 20% of the stock of Wren Corporation,which she acquired several years ago at a cost of $10,000.Amy is Vice-President of Wren and earns a salary of $80,000 annually.Last year,Wren Corporation was experiencing financial problems,and Amy loaned the corporation $25,000.In the current year,Wren becomes bankrupt,and both her stock investment and the loan become worthless.Amy has a nonbusiness bad debt deduction this year of $25,000.
(True/False)
4.7/5 (86)
(86) A transferor who receives stock for both property and services cannot be included in the control group in determining whether an exchange meets the requirements of § 351.
(True/False)
4.8/5 (76)
(76) Isabella and Marta form Pine Corporation. Isabella transfers land (basis of $40,000 and fair market value of $180,000)for 50 shares plus $20,000 cash,while Marta transfers $160,000 cash for the other 50 shares in Pine Corporation. Pine Corporation has a basis of $40,000 in the land it receives from Isabella.
(True/False)
4.8/5 (90)
(90) Shawn transfers property (basis of $40,000 and fair market value of $35,000)to Condor Corporation in exchange for § 1244 stock. The transfer qualifies as a nontaxable exchange under § 351; therefore,Shawn's basis in the Condor stock is $40,000. Five years later,Shawn sells the Condor stock for $25,000. With respect to the sale,Shawn has:
(Multiple Choice)
4.8/5 (81)
(81) Rita forms Finch Corporation by transferring land (basis of $125,000; fair market value of $750,000)which is subject to a mortgage of $375,000. Two weeks prior to incorporating Finch,Rita borrows $125,000 for personal purposes and gives the lender a second mortgage on the land. Finch Corporation issues stock worth $250,000 to Rita and assumes the two mortgages on the land. What are the tax consequences to Rita and to Finch Corporation?
(Essay)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)