



 Chat with AI
Exam 13: Investor Behavior and Capital Market Efficiency

Exam 1: The Corporation38 Questions
Exam 2: Introduction to Financial Statement Analysis103 Questions
Exam 3: Financial Decision Making and the Law of One Price89 Questions
Exam 4: The Time Value of Money91 Questions
Exam 5: Interest Rates68 Questions
Exam 6: Valuing Bonds115 Questions
Exam 7: Investment Decision Rules86 Questions
Exam 8: Fundamentals of Capital Budgeting95 Questions
Exam 9: Valuing Stocks96 Questions
Exam 10: Capital Markets and the Pricing of Risk103 Questions
Exam 11: Optimal Portfolio Choice and the Capital Asset Pricing Model134 Questions
Exam 12: Estimating the Cost of Capital104 Questions
Exam 13: Investor Behavior and Capital Market Efficiency77 Questions
Exam 14: Capital Structure in a Perfect Market99 Questions
Exam 15: Debt and Taxes95 Questions
Exam 16: Financial Distress,managerial Incentives,and Information111 Questions
Exam 17: Payout Policy96 Questions
Exam 18: Capital Budgeting and Valuation With Leverage99 Questions
Exam 19: Valuation and Financial Modeling: a Case Study49 Questions
Exam 20: Financial Options57 Questions
Exam 21: Option Valuation43 Questions
Exam 22: Real Options64 Questions
Exam 23: Raising Equity Capital52 Questions
Exam 24: Debt Financing54 Questions
Exam 25: Leasing46 Questions
Exam 26: Working Capital Management48 Questions
Exam 27: Short-Term Financial Planning47 Questions
Exam 28: Mergers and Acquisitions59 Questions
Exam 29: Corporate Governance46 Questions
Exam 30: Risk Management53 Questions
Exam 31: International Corporate Finance45 Questions
Select questions type


Use the following information to answer the question(s)below.
Assume that the CAPM is a good description of stock price returns.The market expected return is 8% with 12% volatility and the risk-free rate is 3%.New news arrives that does not change any of these numbers,but it does change the expected returns of the following stocks: 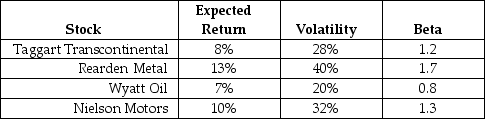 -The expected alpha for Taggart Transcontinental is closest to:
 (Multiple Choice)
4.9/5  (94)
(94) Use the figure for the question(s)below.
Consider the following graph of the security market line:  -Portfolio "C":
 (Multiple Choice)
4.8/5 (88)
(88)  Is a(n):
A group of portfolios from which we can form an efficient portfolio are called:
(Multiple Choice)
4.9/5 (75)
(75) Use the following information to answer the question(s)below.  All amounts are in millions.
-The correlation between the expected return and the market capitalization of these stocks is:
All amounts are in millions.
-The correlation between the expected return and the market capitalization of these stocks is: (Multiple Choice)
4.8/5 (88)
(88) Use the equation for the question(s)below.
Consider the following regression model:
Rs - rf = as +  (RF1 - rf)+
 (RF2 - rf)+ e
-The term as is a(n):
(RF1 - rf)+ (RF2 - rf)+ e
-The term as is a(n): (Multiple Choice)
4.9/5 (85)
(85) When investors imitate each other's actions,this is known as ________ behavior.
(Multiple Choice)
4.8/5 (75)
(75) Use the following information to answer the question(s)below.
Assume that the economy has three types of people.20% are fad followers,75% are passive investors,and 5% are informed traders.The portfolio consisting of all informed traders has a beta of 1.4 and an expected return of 16%.The market has an expected return of 10% and the risk-free rate is 4%.
-The alpha for the informed investors is closest to:
(Multiple Choice)
4.9/5 (73)
(73) Which of the following is NOT true regarding individual investor behavior?
(Multiple Choice)
4.8/5 (65)
(65) Use the table for the question(s)below.
Consider the following information regarding the Fama French Carhart four factor model:  -According to study by Berk and van Binsbergen,which risk model determines mutual fund flows?
 (Multiple Choice)
5.0/5 (75)
(75) Assume that you are an investor with the disposition effect and you bought each of these stocks in January.Suppose that it is currently the end of June,which stocks are you most inclined to hold?
1.Taggart Transcontinental
2.Rearden Metal
3.Wyatt Oil
4.Nielson Motors
(Multiple Choice)
4.9/5 (75)
(75) Use the equation for the question(s)below.
Consider the following factor model:
E[Rs] - rf =  (E[RMkt] - rf)+
 E[RSMB] +
 E[RHML] +
 E[RPR1 YR]
-The term
 Measures the sensitivity of the securities returns to:
(E[RMkt] - rf)+ E[RSMB] + E[RHML] + E[RPR1 YR]
-The term
Measures the sensitivity of the securities returns to: (Multiple Choice)
4.7/5 (74)
(74) If investors have relative wealth concerns,they care most about:
(Multiple Choice)
5.0/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)