



 Chat with AI
Exam 21: Option Valuation


Using the binomial pricing model,calculate the price of a two-year put option on Kinston stock with a strike price of $9.

 (87)
 Verified
This problem requires a two period binomial tree.The solution will start by solving the value of the call option for the up and down branches as of year 1 and then solve for the final value of the option at year 0. 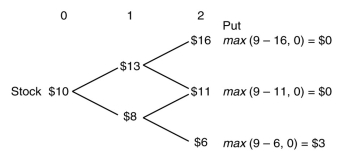
Up branch
D = 
= 
= 0
B = 
= 
= 0
C = SD + B = $13(0)+ (0)= $0
Down Branch
D = 
= 
= -0.6
B = 
= 
= 6.285714
C = SD + B = $8(-0.6)+ (6.285714)= $1.49
Value at year 0
D = 
= 
= -0.298
B = 
= 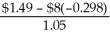
= 3.874
C = SD + B = $10(-0.298)+ 3.874 = $0.89
The Black-Scholes value of a one-year call option on Taggart stock with a strike price of $50 is closest to:
(79) VerifiedA
Use the information for the question(s)below.
The current price of Kinston Corporation stock is $10.In each of the next two years,this stock price can either go up by $3.00 or go down by $2.00.Kinston stock pays no dividends.The one year risk-free interest rate is 5% and will remain constant.
-Using the binomial pricing model,calculate the price of a two-year call option on Kinston stock with a strike price of $9.
(80) VerifiedThis problem requires a two period binomial tree.The solution will start by solving the value of the call option for the up and down branches as of year 1 and then solve for the final value of the option at year 0. 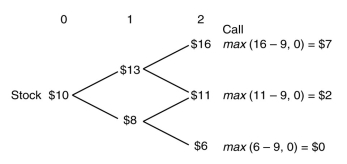
Up branch
D = 
= 
= 1
B = 
= 
= -8.571429
C = SD + B = $13(1)+ (-8.571429)= $4.43
Down Branch
D = 
= 
= .4
B = 
= 
= -2.285714
C = SD + B = $8(.4)+ (-2.285714)= $0.91
Value at year 0
D = 
= 
= .7040
B = 
= 
= -4.497143
C = SD + B = $10(.704)+ (-4.497143)= $2.54
The Black-Scholes value of a one-year,at-the-money put option on Taggart stock is closest to:
(77) Using the binomial pricing model,the calculated price of a one-year put option on KD stock with a strike price of $20 is closest to:
(86) Using risk neutral probabilities,the calculated price of a one-year put option on KD stock with a strike price of $20 is closest to:
(79) Consider the following equation:
B =  In this equation,the term B,represents:
 (84) The Black-Scholes Δ of a one-year,at-the-money put option on Taggart stock is closest to:
(80) Consider the following equation:
C = S × N  - PV(K)× N
 In this equation,the term σ represents:
- PV(K)× N
In this equation,the term σ represents: (83) Which of the following is a corporate application of option pricing?
(80) Consider the following equation:
D =  In this equation,the term D,represents:
 (89) Use the information for the question(s)below.
The current price of KD Industries stock is $20.In the next year the stock price will either go up by 20% or go down by 20%.KD pays no dividends.The one year risk-free rate is 5% and will remain constant.
-Using the binomial pricing model,the calculated price of a one-year call option on KD stock with a strike price of $20 is closest to:
(75) Use the information for the question(s)below.
The current price of Kinston Corporation stock is $10.In each of the next two years,this stock price can either go up by $3.00 or go down by $2.00.Kinston stock pays no dividends.The one year risk-free interest rate is 5% and will remain constant.
-Using risk neutral probabilities,calculate the price of a two-year call option on Kinston stock with a strike price of $9.
(78) Use the information for the question(s)below.
The current price of KD Industries stock is $20.In the next year the stock price will either go up by 20% or go down by 20%.KD pays no dividends.The one year risk-free rate is 5% and will remain constant.
-Assuming the Beta on KD stock is 1.1,the calculated beta for a one-year call option on KD stock with a strike price of $20 is closest to:
(81) Using risk neutral probabilities,calculate the price of a two-year put option on Kinston stock with a strike price of $9.
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)