



 Chat with AI
Exam 6: Valuing Bonds

Exam 1: The Corporation38 Questions
Exam 2: Introduction to Financial Statement Analysis103 Questions
Exam 3: Financial Decision Making and the Law of One Price89 Questions
Exam 4: The Time Value of Money91 Questions
Exam 5: Interest Rates68 Questions
Exam 6: Valuing Bonds115 Questions
Exam 7: Investment Decision Rules86 Questions
Exam 8: Fundamentals of Capital Budgeting95 Questions
Exam 9: Valuing Stocks96 Questions
Exam 10: Capital Markets and the Pricing of Risk103 Questions
Exam 11: Optimal Portfolio Choice and the Capital Asset Pricing Model134 Questions
Exam 12: Estimating the Cost of Capital104 Questions
Exam 13: Investor Behavior and Capital Market Efficiency77 Questions
Exam 14: Capital Structure in a Perfect Market99 Questions
Exam 15: Debt and Taxes95 Questions
Exam 16: Financial Distress,managerial Incentives,and Information111 Questions
Exam 17: Payout Policy96 Questions
Exam 18: Capital Budgeting and Valuation With Leverage99 Questions
Exam 19: Valuation and Financial Modeling: a Case Study49 Questions
Exam 20: Financial Options57 Questions
Exam 21: Option Valuation43 Questions
Exam 22: Real Options64 Questions
Exam 23: Raising Equity Capital52 Questions
Exam 24: Debt Financing54 Questions
Exam 25: Leasing46 Questions
Exam 26: Working Capital Management48 Questions
Exam 27: Short-Term Financial Planning47 Questions
Exam 28: Mergers and Acquisitions59 Questions
Exam 29: Corporate Governance46 Questions
Exam 30: Risk Management53 Questions
Exam 31: International Corporate Finance45 Questions
Select questions type


If the YTM of these bonds decreases to 7%,which bond's price would be most sensitive to this change in YTM?
(Multiple Choice)
4.8/5  (84)
(84) The yield to maturity for the three year zero-coupon bond is closest to:
(Multiple Choice)
4.8/5 (67)
(67) Consider a zero coupon bond with 20 years to maturity.The amount that the price of the bond will change if its yield to maturity decreases from 7% to 5% is closest to:
(Multiple Choice)
4.7/5 (82)
(82) Use the table for the question(s)below.
Consider the following yields to maturity on various one-year zero-coupon securities: 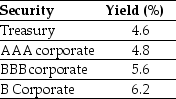 -The price (expressed as a percentage of the face value)of a one-year,zero-coupon corporate bond with a BBB rating is closest to:
 (Multiple Choice)
4.8/5 (75)
(75) An exception to the key difference between sovereign default and corporate bonds is:
(Multiple Choice)
4.8/5 (78)
(78) Use the information for the question(s)below.
The Sisyphean Company has a bond outstanding with a face value of $1000 that reaches maturity in 15 years.The bond certificate indicates that the stated coupon rate for this bond is 8% and that the coupon payments are to be made semiannually.
-Assuming the appropriate YTM on the Sisyphean bond is 7.5%,then the price that this bond trades for will be closest to:
(Multiple Choice)
4.8/5 (59)
(59) A key difference between sovereign default and corporate bonds is:
(Multiple Choice)
4.8/5 (88)
(88) A three-month treasury bill sold for a price of $99.311998 per $100 face value.The yield to maturity of this bond expressed as an EAR is closest to:
(Multiple Choice)
4.8/5 (80)
(80) Consider a zero coupon bond with 20 years to maturity.The percentage change in the price of the bond if its yield to maturity decreases from 7% to 5% is closest to:
(Multiple Choice)
4.9/5 (80)
(80) The price today of a 4 year default free security with a face value of $1000 and an annual coupon rate of 5.25% is closest to:
(Multiple Choice)
4.9/5 (79)
(79) Wyatt Oil is contemplating issuing a 20-year bond with semiannual coupons,a coupon rate of 5%,and a face value of $1000.Wyatt Oil believes it can get a AAA rating from Standard and Poor's for this bond issue.What is the difference in the price the company will receive if the rating is BBB instead of AAA?
(Multiple Choice)
4.8/5 (84)
(84) The forward rate for year 4 (the forward rate quoted today for an investment that begins in three years and matures in four years)is closest to:
(Multiple Choice)
4.9/5 (76)
(76) Consider a corporate bond with a $1000 face value,10% coupon with semiannual coupon payments,5 years until maturity,currently selling for a cash price of $1113.80.The next coupon payment will be made in 63 days and there are 182 days in the current coupon period.The clean price for this bond is closest to:
(Multiple Choice)
5.0/5 (86)
(86) The price per $100 face value of a four-year,zero-coupon,risk-free bond is closest to:
(Multiple Choice)
4.8/5 (79)
(79) Consider a corporate bond with a $1000 face value,8% coupon with semiannual coupon payments,7 years until maturity,and a YTM of 9%.It has been 57 days since the last coupon payment was made and there are 182 days in the current coupon period.The dirty (cash)price for this bond is closest to:
(Multiple Choice)
4.9/5 (73)
(73) Use the table for the question(s)below.
Consider the following four bonds that pay annual coupons:  -The percentage change in the price of the bond "A" if its yield to maturity increases from 5% to 6% is closest to:
 (Multiple Choice)
4.8/5 (75)
(75) Use the information for the question(s)below.
The Sisyphean Company has a bond outstanding with a face value of $1000 that reaches maturity in 15 years.The bond certificate indicates that the stated coupon rate for this bond is 8% and that the coupon payments are to be made semiannually.
-How much are each of the semiannual coupon payments? Assuming the appropriate YTM on the Sisyphean bond is 8.8%,then at what price should this bond trade for?
(Essay)
4.8/5 (101)
(101) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)