



 Chat with AI
Exam 4: Legal Liability of CPAS

Exam 1: The Role of the Public Accountant in the American Economy45 Questions
Exam 2: Professional Standards62 Questions
Exam 3: Professional Ethics62 Questions
Exam 4: Legal Liability of CPAS56 Questions
Exam 5: Audit Evidence and Documentation81 Questions
Exam 6: Audit Planning, understanding the Client, assessing Risks, and Responding78 Questions
Exam 7: Internal Control92 Questions
Exam 8: Consideration of Internal Control in an Information Technology Environment63 Questions
Exam 9: Audit Sampling83 Questions
Exam 10: Cash and Financial Investments63 Questions
Exam 11: Accounts Receivable, Notes Receivable, and Revenue65 Questions
Exam 12: Inventories and Cost of Goods Sold59 Questions
Exam 13: Property Plant and Equipment: Depreciation and Depletion39 Questions
Exam 14: Accounts Payable and Other Liabilities50 Questions
Exam 15: Debt and Equity Capital41 Questions
Exam 16: Auditing Operations and Completing the Audit69 Questions
Exam 17: Auditors Report63 Questions
Exam 18: Integrated Audits of Public Companies43 Questions
Exam 19: Additional Assurance Services: Historical Financial Information59 Questions
Exam 20: Additional Assurance Services: Other Information48 Questions
Exam 21: Internal, Operational, and Compliance Auditing46 Questions
Exam 22: Probability-Proportion-To-Size Sampling24 Questions
Select questions type


Assume that $500,000 in damages are awarded to a plaintiff,and the CPA's percentage of responsibility established at 10%,while others are responsible for the other 90%.Assume the others have no financial resources.As a result the CPA has been required to pay the entire $500,000.The auditor's liability is most likely based upon which approach to assessing liability?
(Multiple Choice)
4.8/5  (81)
(81) Which common law approach leads to increased CPA liability to "foreseeable" third parties for ordinary negligence?
(Multiple Choice)
4.9/5 (78)
(78) The Securities Act of 1934 includes provisions for criminal charges against persons violating the Act.
(True/False)
4.9/5 (75)
(75) Under common law,which of the following statements most accurately reflects the liability of a CPA who fraudulently gives an opinion on an audit of a client's financial statements?
(Multiple Choice)
4.9/5 (75)
(75) Which of the following is accurate with respect to litigation involving CPAs?
(Multiple Choice)
4.8/5 (96)
(96) In which of the following court cases was a precedent set increasing liability to third parties arising from audits under common law?
(Multiple Choice)
5.0/5 (86)
(86) An auditor knew that the purpose of her audit was to render reasonable assurance on financial statements that were to be used for the application for a loan; the auditor did not know the identity of the bank that would eventually give the loan.Under the foreseeable third party approach the auditor is generally liable to the bank which subsequently grants the loan for:
(Multiple Choice)
4.9/5 (65)
(65) Most charges made against auditors under common law are criminal.
(True/False)
4.9/5 (79)
(79) The precedent set by the Hochfelder v.Ernst case is generally believed to have increased auditors' legal liability.
(True/False)
4.7/5 (86)
(86) Under Section 10 of the 1934 Securities Exchange Act auditors are liable to security purchasers for:
(Multiple Choice)
4.8/5 (63)
(63) An auditor knew that the purpose of her audit was to render reasonable assurance on financial statements that were to be used for the application for a loan; the auditor did not know the identity of the bank that would eventually give the loan.Under the Restatement of Torts approach to liability the auditor is generally liable to the bank which subsequently grants the loan for:
(Multiple Choice)
4.7/5 (95)
(95) The auditors can be held liable for negligence in audits of financial statements,but not in reviews of financial statements.
(True/False)
4.8/5 (86)
(86) Quincy bought Teal Corp.common stock in an offering registered under the Securities Act of 1933.Worth & Co.,CPAs,gave an unqualified opinion on Teal's financial statements that were included in the registration statement filed with the SEC.Quincy sued Worth under the provisions of the 1933 Act that deal with omission of facts required to be in the registration statement.Quincy must prove that:
(Multiple Choice)
4.9/5 (82)
(82) The Private Securities Litigation Reform Act of 1995 imposes proportionate liability on the CPA who:
(Multiple Choice)
4.9/5 (81)
(81) A principle that may reduce or entirely eliminate auditor liability to a client is:
(Multiple Choice)
4.8/5 (78)
(78) Which of the following is the best defense that a CPA can assert against common law litigation by a stockholder claiming fraud based on an unqualified opinion on materially misstated financial statements?
(Multiple Choice)
4.8/5 (82)
(82) Under the Securities Act of 1933 the burden of proof that the plaintiff sustained a loss must be proven by the:
(Multiple Choice)
4.7/5 (84)
(84) Jones,CPA,is in court defending himself against a lawsuit filed under the 1933 Securities Act.The charges have been filed by purchasers of securities covered under that act.If the purchasers prove their required elements,in general Jones will have to prove that:
(Multiple Choice)
4.9/5 (90)
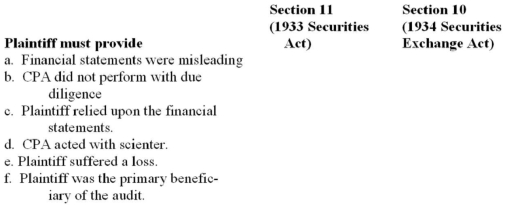
(90) Section 11 of the Securities Act of 1933,and Section 10 of the Securities Exchange Act of 1934 make a CPA potentially liable to a purchaser of registered securities.For items a through f,place a checkmark (Ö)under the column if the plaintiff must prove its existence:
(Essay)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)