



 Chat with AI
Exam 22: Probability-Proportion-To-Size Sampling

Exam 1: The Role of the Public Accountant in the American Economy45 Questions
Exam 2: Professional Standards62 Questions
Exam 3: Professional Ethics62 Questions
Exam 4: Legal Liability of CPAS56 Questions
Exam 5: Audit Evidence and Documentation81 Questions
Exam 6: Audit Planning, understanding the Client, assessing Risks, and Responding78 Questions
Exam 7: Internal Control92 Questions
Exam 8: Consideration of Internal Control in an Information Technology Environment63 Questions
Exam 9: Audit Sampling83 Questions
Exam 10: Cash and Financial Investments63 Questions
Exam 11: Accounts Receivable, Notes Receivable, and Revenue65 Questions
Exam 12: Inventories and Cost of Goods Sold59 Questions
Exam 13: Property Plant and Equipment: Depreciation and Depletion39 Questions
Exam 14: Accounts Payable and Other Liabilities50 Questions
Exam 15: Debt and Equity Capital41 Questions
Exam 16: Auditing Operations and Completing the Audit69 Questions
Exam 17: Auditors Report63 Questions
Exam 18: Integrated Audits of Public Companies43 Questions
Exam 19: Additional Assurance Services: Historical Financial Information59 Questions
Exam 20: Additional Assurance Services: Other Information48 Questions
Exam 21: Internal, Operational, and Compliance Auditing46 Questions
Exam 22: Probability-Proportion-To-Size Sampling24 Questions
Select questions type


For which of the following populations would probability-proportional-to-size sampling be most likely to be the most efficient technique in confirming accounts receivable?

Free
(Multiple Choice)
4.9/5  (79)
(79) Correct Answer: Verified
A
Williams,CPA intends to use probability-proportional-to-size sampling.He has properly selected and audited a sample of 100 accounts receivable from his client's population of 3000 accounts.He calculated a sampling interval of $5,000 and the tolerable misstatement for the account is $40,000.He has the following table available:  Williams also recalls that "basic precision" is equal to the appropriate reliability factor multiplied times the sampling interval.He wishes to accept a risk of incorrect acceptance of 10 percent.
He found that 97 of the 100 accounts in the sample were properly calculated.However,the following three errors existed: Book Value Audited Value \ 50 \ 49 400 300 8,000 6,000 a.Calculate the projected misstatement.
b.Calculate the basic precision.
c.Calculate the incremental allowance.
d.Calculate the upper limit on misstatement.
e.Explain how the auditors would consider the results calculated above.
Williams also recalls that "basic precision" is equal to the appropriate reliability factor multiplied times the sampling interval.He wishes to accept a risk of incorrect acceptance of 10 percent.
He found that 97 of the 100 accounts in the sample were properly calculated.However,the following three errors existed: Book Value Audited Value \ 50 \ 49 400 300 8,000 6,000 a.Calculate the projected misstatement.
b.Calculate the basic precision.
c.Calculate the incremental allowance.
d.Calculate the upper limit on misstatement.
e.Explain how the auditors would consider the results calculated above. Free
(Essay)
4.9/5 (91)
(91) Correct Answer:Verified
Verified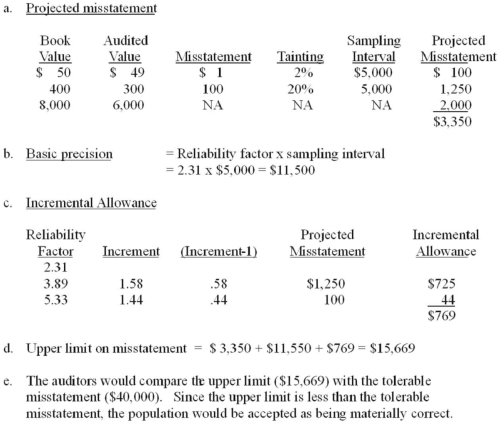
Which statement is most proper for evaluating the results of this PPS sample?
Free
(Multiple Choice)
4.8/5 (81)
(81) Correct Answer:Verified
VerifiedC
The upper limit on misstatement in a probability-proportional-to-size sample plan consists of the total of the projected misstatement and the tolerable misstatement.
(True/False)
4.8/5 (84)
(84) When no misstatements are identified in a PPS sample,the upper limit on misstatement equals.
(Multiple Choice)
4.9/5 (67)
(67) Which of the following statements is correct concerning probability-proportional-to-size sampling?
(Multiple Choice)
4.8/5 (74)
(74) In a PPS sample,the most likely misstatement in the population is equal to the:
(Multiple Choice)
4.8/5 (67)
(67) When using probability-proportional-to-size sampling,the actual total misstatement in a population is most likely to be closest to the:
(Multiple Choice)
4.8/5 (79)
(79) Increasing the expected misstatement for a probability-proportional-to-size sample increases the required sample size.
(True/False)
4.9/5 (79)
(79) In a probability-proportional-to-size sample with a sampling interval of $10,000,an auditor discovered that a selected account receivable with a recorded amount of $5000 had an audited amount of $4,000.If this were the only misstatement discovered by the auditor,the projected misstatement of this sample would be:
(Multiple Choice)
4.8/5 (66)
(66) Assume the following relating to a PPS sample:
• Projected Misstatement = $20,000.
• Basic Precision = $16,000.
• Incremental Allowance = $4,500.
• Tolerable Misstatement = $34,000.
The allowance for sampling risk is equal to:
(Multiple Choice)
4.9/5 (73)
(73) A normally distributed sample is assumed when using probability-proportional-to-size sampling.
(True/False)
4.8/5 (62)
(62) The auditors of Smith Electronics wish to limit the audit risk of material misstatement in the test of accounts receivable to 5 percent.They believe that inherent risk is 100%,there is a 40 percent risk that material misstatement could have bypassed the client's system of internal control,and a 50 percent risk that any existing material misstatement would not have been brought to light by the auditors' analytical procedures.What is the maximum risk of incorrect acceptance the auditors should specify in their substantive tests of details of accounts receivable?
(Multiple Choice)
4.8/5 (73)
(73) Assume the following relating to a PPS sample:
• Projected Misstatement = $20,000.
• Basic Precision = $16,000.
• Incremental Allowance = $4,500.
• Tolerable Misstatement = $34,000.
The most likely amount of misstatement in the population is equal to:
(Multiple Choice)
4.9/5 (73)
(73) An increase in the scope of analytical procedures may result in a lower allowable risk of incorrect acceptance for a substantive test of details.
(True/False)
4.9/5 (78)
(78) Which statement is correct with respect to the probability-proportional-to-size technique?
(Multiple Choice)
4.9/5 (81)
(81) When using probability-proportional-to-size sampling,the allowance for sampling risk is the combination of basic precision and the:
(Multiple Choice)
5.0/5 (84)
(84) The use of probability-proportional-to-size sampling would be least likely to be efficient if:
(Multiple Choice)
4.7/5 (90)
(90) Assume the following relating to a PPS sample:
• Projected Misstatement = $20,000.
• Basic Precision = $16,000.
• Incremental Allowance = $4,500.
• Tolerable Misstatement = $34,000.
The upper limit on misstatement equals.
(Multiple Choice)
4.8/5 (71)
(71) In a probability-proportional-to-size sample with a sampling interval of $10,000,an auditor discovered that as selected account receivable with a recorded amount of $12,000 had an audited amount of $9,000.If this were the only misstatement discovered by the auditor,the projected misstatement of this sample would be:
(Multiple Choice)
4.9/5 (93)
(93) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)