



 Chat with AI
Exam 13: Jurisdictional Issues in Business Taxation

Exam 1: Taxes and Taxing Jurisdictions87 Questions
Exam 2: Policy Standards for a Good Tax85 Questions
Exam 3: Taxes As Transaction Costs82 Questions
Exam 4: Maxims of Income Tax Planning92 Questions
Exam 5: Tax Research82 Questions
Exam 6: Taxable Income From Business Operations116 Questions
Exam 7: Property Acquisitions and Cost Recovery Deductions116 Questions
Exam 8: Property Dispositions122 Questions
Exam 9: Nontaxable Exchanges107 Questions
Exam 10: Sole Proprietorships, Partnerships, llcs, and S Corporations97 Questions
Exam 11: The Corporate Taxpayer103 Questions
Exam 12: The Choice of Business Entity102 Questions
Exam 13: Jurisdictional Issues in Business Taxation107 Questions
Exam 14: The Individual Tax Formula113 Questions
Exam 15: Compensation and Retirement Planning107 Questions
Exam 16: Investment and Personal Financial Planning109 Questions
Exam 17: Tax Consequences of Personal Activities93 Questions
Exam 18: The Tax Compliance Process86 Questions
Select questions type


Wilmington,Inc.,a Pennsylvania corporation,manufactures computer components that it sells to Seine Corporation,a French company,for assembly into finished products.Wilmington owns 90% of Seine's stock.Wilmington's cost per component is $5,its selling price per component is $16,and it sold 110,000 components to Seine this year.Wilmington's taxable income as reported on its Form 1120 was $2,400,000,and Seine's taxable income as reported on its French corporate income tax return was $1,750,000.Determine the effect on the taxable incomes of both corporations if the IRS determines that an arm's length transfer price per component is $23.
(Multiple Choice)
4.7/5  (79)
(79) Which of the following statements regarding controlled foreign corporations is true?
(Multiple Choice)
4.8/5 (63)
(63) Chester,Inc.,a U.S.multinational,earns income in three foreign countries.Country A has a 25% income tax,Country B has a 35% income tax,and Country C has a 45% income tax.In which of these countries could Chester lower its world-wide tax liability by operating through a foreign subsidiary rather than a domestic subsidiary? Assume the foreign subsidiary will reinvest all after-tax earnings rather than paying dividends.
(Multiple Choice)
4.8/5 (81)
(81) A controlled foreign corporation is a foreign corporation in which U.S.shareholders own more than 50% of the voting power or stock value.
(True/False)
4.7/5 (74)
(74) Which of the following activities create state income tax nexus?
(Multiple Choice)
4.7/5 (78)
(78) Tri-State's,Inc.operates in Arkansas,Oklahoma,and Kansas.Assume that each state has adopted the UDITPA formula.During the corporation's tax year ended December 31,the apportionment data indicated: 
 Tri-State's income for the current year is $250,000.Approximately how much income will be taxed by Oklahoma?
 (Multiple Choice)
4.9/5 (87)
(87) World Sales,Inc.,a U.S.multinational,had pretax U.S.source income and foreign source income as follows.Corporate tax rate schedule. 
 World Sales paid $50,000 income taxes to Country O.What is World Sale's U.S.tax liability if it deducts the foreign taxes paid?
 (Multiple Choice)
5.0/5 (92)
(92) Harris Corporation's before-tax income was $400,000.It does business entirely in Pennsylvania,which has a 6% corporate income tax.Compute Harris' federal income tax.
(Multiple Choice)
4.9/5 (77)
(77) Supplies,Inc.does business in Georgia (6% tax rate)and Alabama (5% tax rate).All other factors being equal,the company will reduce state taxes if it increases the compensation paid to its employees in Alabama.
(True/False)
4.9/5 (81)
(81) Albany,Inc.does business in states C and D.State C uses an apportionment formula that double-weights the sales factor; state D apportions income using an equally-weighted three-factor formula.Albany's before tax income is $3,000,000,and its sales,payroll,and property factors are as follows. 
 Calculate Albany's income taxable in each state.
 (Multiple Choice)
4.9/5 (61)
(61) Which of the following statements about the Uniform Division of Income for Tax Purposes Act (UDITPA)is false?
(Multiple Choice)
4.8/5 (85)
(85) Logan,an Indiana corporation,conducts its international business through 100% controlled foreign subsidiaries.This year,Logan's U.S.source taxable income was $5,431,000,and it received $12,250,000 dividends from its foreign subsidiaries.Logan paid no foreign income tax itself,but its subsidiaries paid foreign income tax at a 30% rate.Logan's U.S.income tax (35% rate)is:
(Multiple Choice)
4.9/5 (90)
(90) Origami does business in states X and Y.State X uses an equally-weighted three-factor apportionment formula and has a 4 percent state tax rate.State Y uses an apportionment formula that double-weights the sales factor and has a 6 percent tax rate.Cromwell's taxable income,before apportionment,is $3 million.Its sales,payroll,and property information are as follows. 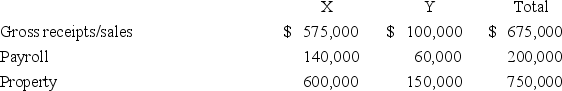 a.Calculate Origami's apportionment factors,income apportioned to each state,and state tax liability.
b.State Y is considering changing its apportionment formula to a single sales factor.Given its current level of activity,would such a change increase or decrease Origami's state income tax burden? Provide calculations to support your conclusion.
a.Calculate Origami's apportionment factors,income apportioned to each state,and state tax liability.
b.State Y is considering changing its apportionment formula to a single sales factor.Given its current level of activity,would such a change increase or decrease Origami's state income tax burden? Provide calculations to support your conclusion. (Essay)
4.9/5 (85)
(85) In which of the following cases are the U.S.shareholders in a controlled foreign corporation (CFC)deferring U.S.tax on the CFC's income?
(Multiple Choice)
4.9/5 (88)
(88) A corporation is usually subject to tax by any state in which it engages in any business transactions.
(True/False)
4.9/5 (68)
(68) Excess foreign tax credits can only be carried to future tax years.
(True/False)
4.8/5 (94)
(94) Under most tax treaties,income attributable to a permanent establishment through which a foreign taxpayer conducts business can be taxed only by the taxpayer's country of residence.
(True/False)
4.8/5 (84)
(84) In determining the portion of a firm's total income subject to a state's income tax,most states use an apportionment formula modeled after the Uniform Division of Income for Tax Purposes Act (UDITPA).
(True/False)
4.8/5 (78)
(78) The UDITPA formula for state income tax apportionment consists of three factors: sales,payroll,and profit.
(True/False)
4.9/5 (95)
(95) Non-resident firms selling tangible goods to in-state residents can use P.L.86-272 to avoid having income tax nexus in a state.
(True/False)
4.9/5 (57)
(57) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)