



 Chat with AI
Exam 6: Revenue Recognition

Exam 1: The Framework for Financial Reporting69 Questions
Exam 2: Accounting Judgements77 Questions
Exam 3: Statements of Income and Comprehensive Income168 Questions
Exam 4: Statements of Financial Position and Changes in Equity; Disclosure Notes127 Questions
Exam 5: The Statement of Cash Flows116 Questions
Exam 6: Revenue Recognition98 Questions
Exam 7: Financial Assets: Cash and Receivables227 Questions
Exam 8: Cost-Based Inventories and Cost of Sales93 Questions
Exam 9: Long-Lived Assets134 Questions
Exam 10: Depreciation, Amortization, and Impairment154 Questions
Exam 11: Financial Instruments: Investments in Bonds and Equity Securities162 Questions
Select questions type


CCA is an optional deduction and may be adjusted downwards in order to create taxable income.
(True/False)
4.8/5  (80)
(80) KER Corp.incurred a loss in 20x15 after several years of taxable income.After the carry back,KER still had unused losses the amount of $357,000.The applicable tax rate was 40%.In 20x16,the tax rate goes up to 45%.Assuming that losses have not been used but it is still probable that they will be used,prepare the journal entry to set up the deferred benefit in 20x15 and any other entries applicable to the deferred benefit.
(Essay)
4.9/5 (82)
(82) JMR Corporation suffered a loss in 2013.As a result,the Corporation has an $87,000 accumulated tax loss carry forward.The current tax rate is 40%.The benefit was recorded in the accounts,as JMR believed it was more likely than not to be realized.In 2014 the tax rate goes down to 38% and JMR has not yet used the benefit.Which of the following statements is true?
(Multiple Choice)
4.9/5 (71)
(71) JG Ltd.has been in business for five years and incurs a loss of $520,000 in 20x15.The company has no temporary differences.The history of the company's earnings since they began operations is as follows: 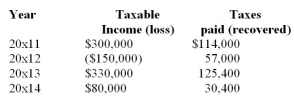 The tax rate has been constant at 38%.
Required:
Prepare journal entries to record the recovery of taxes and any journal entries necessary for any loss carry forwards.Assume probability of recovery is greater than 50%
The tax rate has been constant at 38%.
Required:
Prepare journal entries to record the recovery of taxes and any journal entries necessary for any loss carry forwards.Assume probability of recovery is greater than 50% (Essay)
4.8/5 (79)
(79) The maximum number of years a tax loss can be carried forward is:
(Multiple Choice)
4.9/5 (82)
(82) If a corporation incurs a taxable loss,they are entitled to carry the loss back for three years or forward for twenty years.
(True/False)
4.9/5 (80)
(80) Taxes are recovered at the tax rate in effect during the year of the loss.
(True/False)
4.7/5 (81)
(81) Carry back and carry forward procedures for temporary differences are always applied,even when there are no temporary differences for deductible items,and there are no current income taxes payable.
(True/False)
4.9/5 (81)
(81) VB Ltd.provided you with the following information:  There are no temporary differences.The deferred income tax benefit of the loss carry forward was set up in 2015 as the probability of realization was greater than 50%.In 2016 it was determined that the probability of realization was less than 50%.What would be the carrying amount of the deferred income tax benefit-loss carry forward on the balance sheet at the end of 2016?
 (Multiple Choice)
4.9/5 (88)
(88) What factor would most likely cause a firm to choose the carry forward only option for a net operating loss?
(Multiple Choice)
4.8/5 (82)
(82) If a potential benefit of a loss carry forward that was previously determined to meet the more likely than not criteria has now been determined not to meet the criteria,it should be reversed.
(True/False)
4.8/5 (76)
(76) What options are open to a company that did not previously set up a deferred income tax benefit of a tax loss carry forward but has now determined that the probability of realization is greater than 50%?
(Essay)
4.8/5 (81)
(81) Once a deferred benefit of a tax loss carry forward has been recorded,does it have to remain on the balance sheet until realized? Explain.
(Essay)
4.9/5 (94)
(94) In order to help companies and their auditors determine whether the criteria "more likely than not" has been realized,IAS 12 has set out some guidelines for unfavourable evidence.List two of these.
(Essay)
4.8/5 (79)
(79) The following information for LAS Corporation is available:  LAS applies its tax losses sequentially,that is,tax losses are carried back as far as possible.The taxes recovered for the year ended 2014 amounted to:
 (Multiple Choice)
4.9/5 (77)
(77) Once it is deemed that a potential benefit of a loss carry forward does not meet the more likely than not criteria,the benefit may not be recognized.
(True/False)
4.7/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)