



 Chat with AI
Exam 6: Revenue Recognition

Exam 1: The Framework for Financial Reporting69 Questions
Exam 2: Accounting Judgements77 Questions
Exam 3: Statements of Income and Comprehensive Income168 Questions
Exam 4: Statements of Financial Position and Changes in Equity; Disclosure Notes127 Questions
Exam 5: The Statement of Cash Flows116 Questions
Exam 6: Revenue Recognition98 Questions
Exam 7: Financial Assets: Cash and Receivables227 Questions
Exam 8: Cost-Based Inventories and Cost of Sales93 Questions
Exam 9: Long-Lived Assets134 Questions
Exam 10: Depreciation, Amortization, and Impairment154 Questions
Exam 11: Financial Instruments: Investments in Bonds and Equity Securities162 Questions
Select questions type


Existing sufficient taxable temporary differences,which will result in taxable income,is one piece of evidence to support a more likely than not criteria.

Free
(True/False)
4.7/5  (88)
(88) Correct Answer: Verified
True
VB Corporation incurred a tax loss of $86,000.Based on a tax rate of 45% what is the potential tax benefit?
Free
(Multiple Choice)
4.9/5 (78)
(78) Correct Answer:Verified
VerifiedB
JR Ltd.provided you with the following information:  There are no temporary differences.What will be the amount of the tax refund received in 2015 assuming that tax losses are carried back as far as possible (sequentially)?
Free
(Multiple Choice)
4.8/5 (83)
(83) Correct Answer:Verified
VerifiedB
JMR's taxable income for the first five years was as follows:  Calculate the tax recovery in 20x15.
 (Essay)
4.7/5 (81)
(81) The use of a valuation allowance account is mandatory under IFRS.
(True/False)
4.7/5 (78)
(78) Under income tax laws and regulations a corporation that sustains a net operating loss for the current year may elect to carry back and/or carry forward the loss for income tax purposes.
(True/False)
4.7/5 (89)
(89) Reducing CCA is one tax strategy that a company may employ.All of the following are true except:
(Multiple Choice)
4.9/5 (77)
(77) Under current law,at the end of the year of loss or anytime during the next 15 years,a company may select to either carry back or carry forward-only the loss.
(True/False)
4.9/5 (79)
(79) The following data represents the complete taxable income history for a firm:  What is the tax liability for 2016?
 (Multiple Choice)
4.8/5 (79)
(79) Geisler Corp.provided you with the following information for the year ending December 31,2017: Net Income before taxes: $150,000
Depreciation (included in above)$90,000
CCA$250,000
The net book value of the capital assets was $1,100,000,and their UCC was $900,000 on January 1,2017.
A temporary difference of $200,000 is reflected in an accumulated deferred income tax liability (DTL)balance of $90,000 at January 1,2017.
There were no permanent differences.
Taxable income in the three-year carry back period was $400,000.Tax losses are carried back as far as allowable by law.
A tax rate of 45% applies to the current and previous years.
Geisler's 2017 journal entry to record its Deferred Tax amounts would include:
(Multiple Choice)
4.8/5 (74)
(74) The following information pertains to ABC Inc.:  Assume that ABC Inc.meets the more likely than not criteria for tax loss carry forward recognition.The tax rate for 2015 and beyond is expected to be 20%,and this rate was not known when the 2014 tax return was filed.This information would result in:
 (Multiple Choice)
4.8/5 (91)
(91) The following information for KAR Corporation is available:  KAR carries applies its tax losses sequentially,that is,tax losses are carried back as far as possible.The taxes recovered for the year ended 2014 amounted to:
 (Multiple Choice)
4.7/5 (79)
(79) Which of the following statements with respect to the required disclosures relating to tax loss carry forwards and carry backs is/are correct?
(Multiple Choice)
4.8/5 (62)
(62) How does the existence of a loss in the year impact the accounting of temporary differences?
(Essay)
4.8/5 (75)
(75) KAR's taxable income for the first five years was as follows: 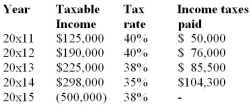 Calculate the tax recovery in 20x15.
 (Essay)
4.8/5 (79)
(79) A company will show the same income tax expense/benefit regardless of whether or not a valuation allowance account is used.
(True/False)
4.9/5 (74)
(74) Reducing CCA is one tax strategy that a company may employ.All of the following are true except:
(Multiple Choice)
4.8/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)