



 Chat with AI
Exam 7: Financial Assets: Cash and Receivables

Exam 1: The Framework for Financial Reporting69 Questions
Exam 2: Accounting Judgements77 Questions
Exam 3: Statements of Income and Comprehensive Income168 Questions
Exam 4: Statements of Financial Position and Changes in Equity; Disclosure Notes127 Questions
Exam 5: The Statement of Cash Flows116 Questions
Exam 6: Revenue Recognition98 Questions
Exam 7: Financial Assets: Cash and Receivables227 Questions
Exam 8: Cost-Based Inventories and Cost of Sales93 Questions
Exam 9: Long-Lived Assets134 Questions
Exam 10: Depreciation, Amortization, and Impairment154 Questions
Exam 11: Financial Instruments: Investments in Bonds and Equity Securities162 Questions
Select questions type


On January 1,2014,LOR Company rented a machine (3-year life,no residual value,straight-line)to LEE Company for a cash rental payable each December 31,20 *11,* 12,and x13.The rental is based on the regular sales price: cost,$35,665; sale price,$45,665.The agreed interest rate was 15% and the lessee retains the machine at the end of the lease term at no additional cost.
(a)The annual rental is $_____________________.
(b)Complete the following lease amortization schedule: 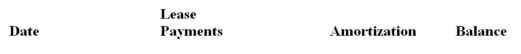
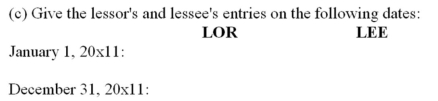
(Essay)
4.8/5  (89)
(89) Assume the following facts relating to a lease: Leased asset,new at inception of lease term.
Estimated useful life,14 years.
Lease term,8 years; asset returns to lessor.
Interest rate implicit in the lease,10 percent (known by lessee).
Lessee's marginal borrowing rate,12 percent.
Amount of each lease payment,$2,000.
Lessor's cost of the leased asset,$15,164.
Market value of leased asset at inception of the lease term,$15,164
Lease payments are due at the end of each period.
From the perspective of the lessee,this lease should be classified as a(n):
(Multiple Choice)
4.8/5 (63)
(63) LAC has negotiated a lease agreement with LEC effective January 1,2014.LAC will provide LEC with a special-purpose building for ten (10)years.The lease is non-cancellable; requires LEC to provide maintenance,insurance,taxes,etc.; and stipulates that the building reverts back to LAC's control at the end of the lease.The building cost LAC $200,000 and is expected to have no residual value at the end of the lease.LAC expects a 15% return on investments and the lease qualifies as a direct financing lease.Rents are paid each December 31 starting in 2014.
(a)How much annual rent will the lessee pay (rounded to the nearest dollar)? $______________________________.
(b)Complete the following schedule of lease amortization for the lessee for the first two years: 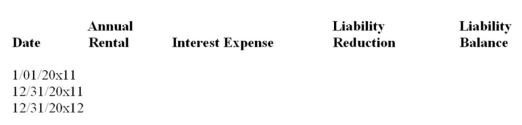 (c)Complete the following entries for the lessee: January 1,2014,inception of lease.
December 31,2014,first rental payment and lessee's year-end entries (end of the accounting period).
December 31,2014,accrual by lessee of $4,000 taxes on the building and payment of $800 for repairs on the building.
(c)Complete the following entries for the lessee: January 1,2014,inception of lease.
December 31,2014,first rental payment and lessee's year-end entries (end of the accounting period).
December 31,2014,accrual by lessee of $4,000 taxes on the building and payment of $800 for repairs on the building. (Essay)
4.7/5 (77)
(77) When a lessee measures the present value of future rentals to be capitalized under a finance lease,identifiable payments expected to be paid by the lessee to cover taxes,insurance,and maintenance should be:
(Multiple Choice)
4.9/5 (74)
(74) If the title to a leased asset does not transfer to the lessee at the end of the lease term,but a third party guarantees the residual,what is the period and residual value used by the lessor to depreciate the leased asset? 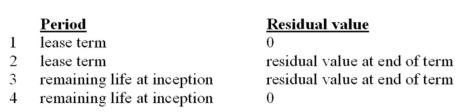
(Multiple Choice)
4.8/5 (84)
(84) Under a sales-type lease,the difference between the cost of the leased asset and the lease receivable is accounted for by the lessor and lessee as follows: 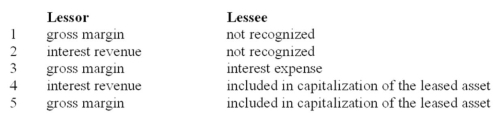
(Multiple Choice)
4.9/5 (78)
(78) Ryan Corp.is a manufacturer of high tech golf carts.On December 31,1999,Ryan Corp.leases 100 golf carts to a local golf course for five years at $95,000 per year payable at the beginning of the lease term.The normal cash sales price of the carts is $4,000 each.The carts cost Ryan Corp.$2,000 each to manufacture.The lease meets all the conditions necessary to be a sales-type lease from the lessor's point of view.Provide the journal entry(ies)on December 31 to account for the lease.
(Essay)
4.8/5 (82)
(82) LAS owns a building in North Bay.LAS enters into an agreement with BH as follows: LAS sells the building to BH on 1/1/2014 for $1,900,000 (the building's fair value on that date was $1,800,000)and immediately leases it back for $500,000 per year for 10 years.The remaining life of the building is estimated at 20 years.The historical cost of the building was $9,000,000 and accumulated amortization amounted to $7,000,000.Assuming that ASPE applies,and that the lease qualifies as a finance lease,the net effect of this transaction on the statement of comprehensive income in the year of sale would be:
(Multiple Choice)
4.9/5 (82)
(82) While only certain leases are currently accounted for as a sale or purchase,there is theoretical justification for considering all leases to be sales or purchases.The principle reason that supports this idea is that:
(Multiple Choice)
4.8/5 (80)
(80) ML leased a computer to LH on January 1,2014.The lease was a five year fixed,non-cancellable agreement.The payments were finalized at $2,380 per year with the first payment on January 1,2014 and ML paid $9,500 for the computer.Carrying value is equal to fair value.The lease is deemed a finance lease.Based on the above information,what type of lease is this for the lessor.Prepare the journal entries for at the inception of the lease using the gross method.
(Essay)
4.8/5 (74)
(74) Lessee ABC INC.leased from Lessor QRS a machine that cost $35,000,which was properly classified as a finance lease by both parties.Assume the lessor used a 12 percent implicit interest rate and that the lessee was informed of that rate.The lease did not include a bargain purchase option and the estimated residual value at termination of the lease was zero.Equal semi-annual lease payments are to be made at the start of each such period,including one on the date the lease was signed.The amount of each semi-annual payment,assuming a five-year lease term,would be:
(Multiple Choice)
4.8/5 (81)
(81) JMR Company leases an asset from KAR Company.The rate implicit in the lease is 12% and JMR's incremental borrowing rate is 11%.JMR is aware of the implicit rate.Assuming that both rates would provide an MLP amount well below the fair value of the leased asset,the rate that JMR should use for discounting the net lease payment is:
(Multiple Choice)
4.9/5 (82)
(82) When the lessee guarantees the residual value at the end of the lease term,the:
(Multiple Choice)
4.8/5 (85)
(85) LMN made the following journal entry relating to a finance lease: 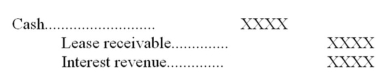 Therefore,LMN must be the:
 (Multiple Choice)
4.8/5 (86)
(86) RST entered into a direct financing lease agreement,which required rentals of $9,600,each year-end.The lease term was for ten years and a 14 percent rate of return is expected by RST.The cost of the machine for RST was (rounded to the nearest dollar):
(Multiple Choice)
4.7/5 (83)
(83) XYZ leased a tract of land for a 20-year term.The lease agreement did not contain a bargain purchase option,and consequently,the land will revert back to the lessor at the end of the lease term.At the inception of the lease,XYZ initiated construction on a small building on the land.The building was completed at the end of the third year of the lease,at a cost of $60,000.The building was a permanent structure on the land.Its estimated life was 20 years and was expected to have no residual value.XYZ should record annual depreciation (straight-line)on the building of:
(Multiple Choice)
4.9/5 (77)
(77) If a lessee does not exercise a bargain purchase option prior to its lapse date,the:
(Multiple Choice)
5.0/5 (89)
(89) On December 10,2014,LMN purchased a special machine for leasing purposes; it cost $10,000.On January 1,2015,the machine was leased to ABC INC.under the following terms (it is a direct financing lease): a.lease term 4 years; interest rate 10 percent; rentals payable at year-end.b.LMN retains the residual value of $1,000 .There is no guarantee on the residual value. On January 1,2015,when the lease term starts,the following accounting amounts should be used: 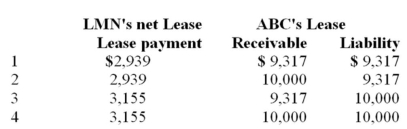
(Multiple Choice)
4.9/5 (69)
(69) Which of the following is not a possible advantage of long-term leases?
(Multiple Choice)
4.9/5 (95)
(95) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)