



 Chat with AI
Exam 9: Accounting Quality

Exam 1: Overview of Financial Reporting, Financial Statement Analysis, and Valuation99 Questions
Exam 2: Asset and Liability Valuation and Income Measurement80 Questions
Exam 3: Income Flows Versus Cash Flows: Understanding the Statement of Cash Flows88 Questions
Exam 4: Profitability Analysis97 Questions
Exam 5: Risk Analysis81 Questions
Exam 6: Financing Activities62 Questions
Exam 7: Investing Activities98 Questions
Exam 8: Operating Activities92 Questions
Exam 9: Accounting Quality64 Questions
Exam 10: Forecasting Financial Statements59 Questions
Exam 11: Risk-Adjusted Expected Rates of Return and the Dividends Valuation Approach52 Questions
Exam 12: Valuation: Cash-Flow-Based Approaches62 Questions
Exam 13: Valuation: Earnings-Based Approaches67 Questions
Exam 14: Valuation: Market-Based Approaches64 Questions
Select questions type


A company may try to paint a favorable picture of itself by accelerating the timing of revenues or estimating the collectible amounts too aggressively.In these cases the quality of accounting information declines because it does not represent the company's true economic condition and may not be sustainable.List four conditions which might suggest that a company is recognizing revenues too early?

Free
(Essay)
5.0/5  (71)
(71) Correct Answer: Verified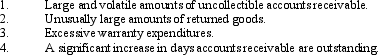
Which of the following is not a characteristic of an extraordinary item?
Free
(Multiple Choice)
4.8/5 (91)
(91) Correct Answer:Verified
VerifiedD
During July 2012 Ralston Company decides to dispose of one of its subsidiaries which qualifies for accounting as a discontinued operation.At the July 2012 measurement date Ralston Company estimates that it will report net losses of $1,500,000 dollars from the measurement date until the disposal date which is expected to be in April 2013.In addition,Ralston estimates that it will lose $300,000 on the sale of the segment.How much gain or loss on discontinued operations will Ralston report in its 2012 income statement (net of income taxes)?
Free
(Multiple Choice)
4.8/5 (89)
(89) Correct Answer:Verified
VerifiedC
A ______________________________ is accounted for by spreading the effect of the prior year's misstatement over the current and future periods.
(Short Answer)
4.8/5 (85)
(85) All of the following are true regarding a high quality balance sheet except:
(Multiple Choice)
4.7/5 (72)
(72) Many users of financial statements believe that the quality of accounting information for intangible assets is low because firms seldom report intangible asset resources on the balance sheet.However,from the perspective of accounting quality what are arguments in favor of expensing most intangibles and not recording them on the balance sheet?
(Essay)
5.0/5 (76)
(76) Quality accounting information seeks to maximize relevance and economic faithfulness,subject to the constraints of the ____________________ of the measurements.
(Short Answer)
4.9/5 (88)
(88) A ____________________ of operations differs from a discontinuation of operations because the firm continues to operate in the business segment.
(Short Answer)
4.9/5 (80)
(80) Firms' choices and estimates within U.S.GAAP or IFRS should be determined by all of the following except:
(Multiple Choice)
4.9/5 (82)
(82) When evaluating the quality of accounting information,an analyst should consider all of the following except:
(Multiple Choice)
4.8/5 (80)
(80) Healy and Wahlen state that one type of earnings management occurs when managers use judgement in financial reporting to alter financial reports in order to mislead some stakeholder about the economic performance of the company.Earnings management is a consequence of a judgement by management which results in lower economic information content of the financial reports.
Discuss five motives that encourage managers to practice earnings management.
(Essay)
4.7/5 (78)
(78) In a restructuring it is possible that managers may use the opportunity to write down assets that do not even relate directly to the restructuring action.Why might a manager decide to write down an asset that is not included in the restructuring action?
(Multiple Choice)
4.9/5 (83)
(83) Some firms attempt to maximize the amount of restructuring charge in a particular year,analysts refer to this as the _________________________ approach.
(Short Answer)
4.8/5 (71)
(71) An extraordinary gain or loss is unusual in nature,_____________________________________________,and material in amount.
(Short Answer)
4.9/5 (76)
(76) ____________________ represents the concept of being able to compare financial statement data across years for any particular firm.
(Short Answer)
4.8/5 (76)
(76) Firm's choices and estimates within U.S.GAAP should be determined by
(Multiple Choice)
4.8/5 (83)
(83) Gains and losses differ from revenues and expenses in that they are produced by ____________________ activities.
(Short Answer)
5.0/5 (85)
(85) Examples of poor earnings quality that hinder the forecasting of expected future earnings include all of the following except:
(Multiple Choice)
4.8/5 (92)
(92) Users of financial statements should consider which of the following when evaluating the quality of accounting information?
(Multiple Choice)
4.8/5 (86)
(86) Achieving comparability in financial reporting is important to the analysis of multinational firm.However,the data from the reconciliation of foreign firms financial statement to U.S.GAAP must be carefully interpreted.What types of things complicate the analysis of multinational firms?
(Essay)
4.7/5 (67)
(67) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)