



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: The Role and Method of Economics198 Questions
Exam 2: Economics: Eight Powerful Ideas197 Questions
Exam 3: Scarcity, Trade-Offs, and Production Possibilities189 Questions
Exam 4: Demand, Supply, and Market Equilibrium240 Questions
Exam 5: Markets in Motion and Price Controls228 Questions
Exam 6: Elasticities206 Questions
Exam 7: Market Efficiency and Welfare136 Questions
Exam 8: Market Failure215 Questions
Exam 9: Public Finance and Public Choice64 Questions
Exam 10: Consumer Choice Theory149 Questions
Exam 11: The Firm: Production and Costs198 Questions
Exam 12: Firms in Perfectly Competitive Markets207 Questions
Exam 13: Monopoly and Antitrust189 Questions
Exam 14: Monopolistic Competition and Product Differentiation159 Questions
Exam 15: Oligopoly and Strategic Behavior146 Questions
Exam 16: The Markets for Labor, Capital, and Land177 Questions
Exam 17: Income, Poverty, and Health Care138 Questions
Exam 18: Introduction to Macroeconomics: Unemployment, Inflation, and Economic Fluctuations171 Questions
Exam 19: Measuring Economic Performance147 Questions
Exam 20: Economic Growth in the Global Economy127 Questions
Exam 21: Financial Markets, Saving, and Investment65 Questions
Exam 22: Aggregate Demand and Aggregate Supply163 Questions
Exam 23: The Aggregate Expenditure Model69 Questions
Exam 25: Monetary Institutions182 Questions
Exam 26: The Federal Reserve System and Monetary Policy147 Questions
Exam 27: Issues in Macroeconomic Theory and Policy130 Questions
Exam 28: International Trade182 Questions
Exam 29: International Finance138 Questions
Select questions type


Exhibit 12-1 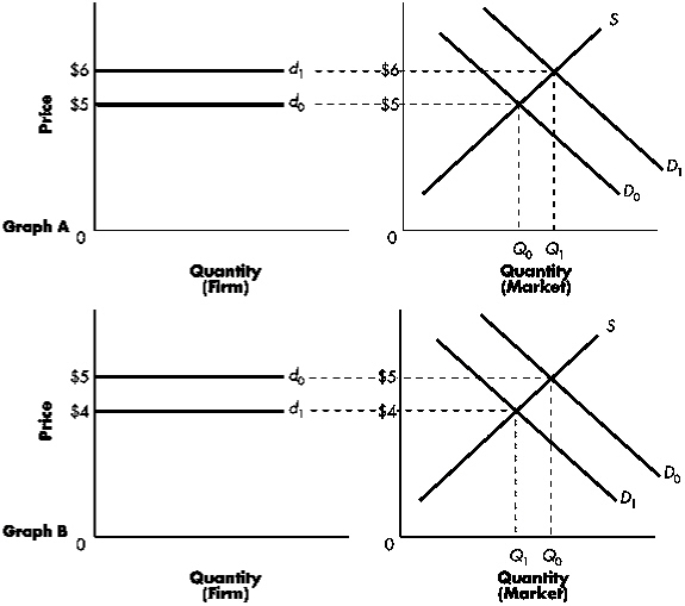 Refer to Exhibit 12-1.In Graph B,the market demand has decreased from d0 to d1,and as a result:
 (Multiple Choice)
4.8/5  (77)
(77) If the typical firm in a perfectly competitive market was depicted in the graph below,what would be most likely to occur? 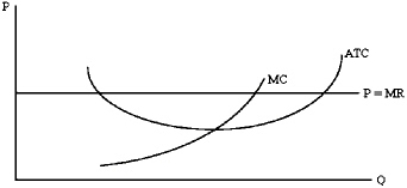
(Multiple Choice)
4.9/5 (86)
(86) Which of the following is a characteristic of a perfectly competitive market?
(Multiple Choice)
4.8/5 (66)
(66) In short-run equilibrium in a perfectly competitive market,firms always make zero economic profit.
(True/False)
4.7/5 (79)
(79) Which one of the following is not a characteristic of a perfectly competitive market?
(Multiple Choice)
4.7/5 (81)
(81) At the level of output where marginal revenue equals marginal cost,price is less than average total cost but greater than average variable cost.In this instance,a profit-maximizing firm should:
(Multiple Choice)
4.8/5 (73)
(73) Which of the following is false of perfectly competitive firms?
(Multiple Choice)
4.7/5 (78)
(78) A profit-maximizing,price-taking firm should cease production whenever:
(Multiple Choice)
4.8/5 (81)
(81) Exhibit 12-5 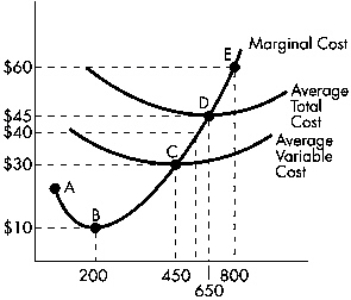 Refer to Exhibit 12-5.In the short run,if the market price falls to $40 per unit,the firm should:
 (Multiple Choice)
4.9/5 (66)
(66) Darlene runs a fruit and vegetable stand in a medium-sized community where there are many such stands.Her weekly total revenue equals $2,000.Her weekly total cost of running the stand equals $3,500,consisting of $2,500 of variable costs and $1,000 of fixed costs.An economist would likely advise Darlene to:
(Multiple Choice)
4.8/5 (78)
(78) The horizontal demand curve facing an individual firm in a perfectly competitive market:
(Multiple Choice)
4.9/5 (82)
(82) Exhibit 12-1 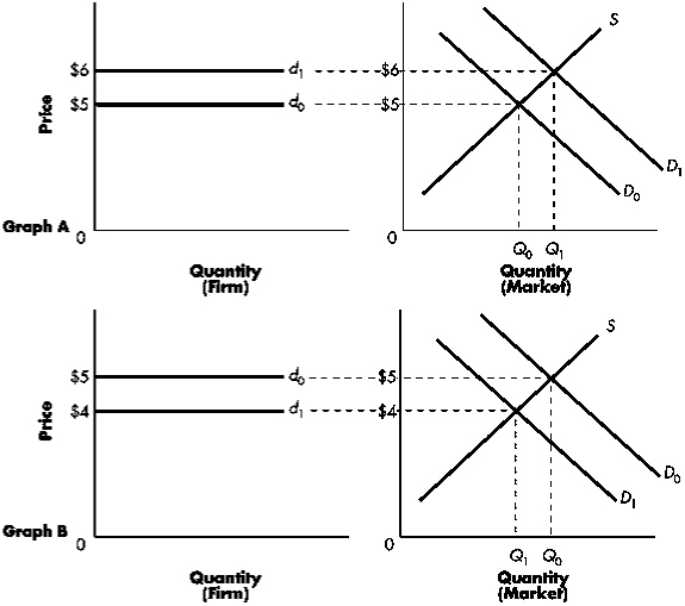 Refer to Exhibit 12-1.Graphs A and B together demonstrate the effect that a change in market demand has on the demand curve faced by a firm that is:
 (Multiple Choice)
4.9/5 (80)
(80) Economic profits in a perfectly competitive industry will encourage entry of new firms,which will shift the market supply curve to the right.
(True/False)
4.8/5 (87)
(87) Which of the following is characteristic of a perfectly competitive market?
(Multiple Choice)
4.9/5 (74)
(74) What would be the long-run equilibrium result of output expansion in a decreasing-cost industry?
(Essay)
4.7/5 (83)
(83) Exhibit 12-9 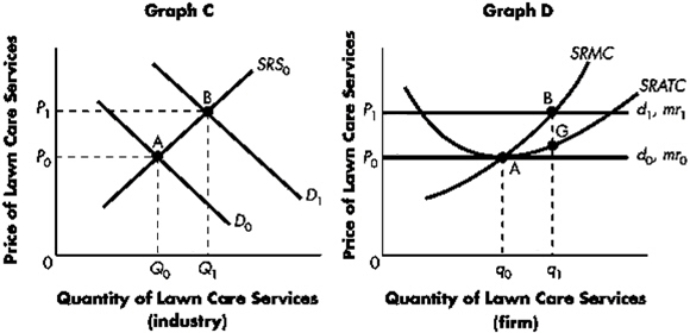 Refer to Exhibit 12-9.The firm is now able to sell more of its lawn care services at a higher price and as a result will be able to earn economic profits:
 (Multiple Choice)
4.9/5 (70)
(70) Beginning from a long run equilibrium in an increasing cost industry,if there is a substantial,permanent fall in demand for industry output:
(Multiple Choice)
4.7/5 (79)
(79) A profit maximizing perfectly competitive firm would never operate at an output level where
(Multiple Choice)
4.7/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)