



 Chat with AI
Exam 4: Job Costing

Exam 1: Cost Management and Strategy79 Questions
Exam 2: Implementing Strategy: The Value Chain, the Balanced Scorecard, and the Strategy Map70 Questions
Exam 3: Basic Cost Management Concepts98 Questions
Exam 4: Job Costing118 Questions
Exam 5: Activity-Based Costing and Customer Profitability Analysis149 Questions
Exam 6: Process Costing106 Questions
Exam 7: Cost Allocation: Departments, Joint Products, and By-Products96 Questions
Exam 8: Cost Estimation120 Questions
Exam 9: Short-Term Profit Planning: Cost-Volume-Profit CVP Analysis105 Questions
Exam 10: Strategy and the Master Budget146 Questions
Exam 11: Decision Making With a Strategic Emphasis137 Questions
Exam 12: Strategy and the Analysis of Capital Investments167 Questions
Exam 13: Cost Planning for the Product Life Cycle: Target Costing, Theory of Constraints, and Strategic Pricing94 Questions
Exam 14: Operational Performance Measurement: Sales, Direct-Cost Variances, and the Role of Nonfinancial Performance Measures178 Questions
Exam 15: Operational Performance Measurement: Indirect-Cost Variances and Resource-Capacity Management167 Questions
Exam 16: Operational Performance Measurement: Further Analysis of Productivity and Sales134 Questions
Exam 17: The Management and Control of Quality146 Questions
Exam 18: Strategic Performance Measurement: Cost Centers, Profit Centers, and the Balanced Scorecard130 Questions
Exam 19: Strategic Performance Measurement: Investment Centers and Transfer Pricing151 Questions
Exam 20: Management Compensation, Business Analysis, and Business Valuation108 Questions
Select questions type


Which of the following is not a method the management accountant must address regarding the costing system?
(Multiple Choice)
4.8/5  (86)
(86) Which method of accumulating product costs, job costing or process costing, would be more appropriate in each of the following situations:
1.A physicians' clinic
2.A manufacturer of ready-mix cement
3.A custom equipment manufacturing
4.A print shop
5.A chemical manufacturer
6.An automobile repair shop
7.A professional services firm
8.A food processing company
9.A consulting firm
10.An oil refinery
(Essay)
4.8/5 (70)
(70) An good example of a software system(s) that can be used to prepare job cost reports is:
(Multiple Choice)
4.8/5 (76)
(76) Randall Company manufactures products to customer specifications. A job costing system is used to accumulate production costs. Factory overhead cost was applied at 125% of direct labor cost. Selected data concerning the past year's operation of the company are presented below. January 1 December 31 Direct materials \ 77,000 \ 40,000 Work in process 66,000 42,000 Finished goods 115,000 100,000 Other information Direct materials purchases \ 324,000 Cost of goods available for sale 950,000 Actual factory overhead costs 260,000 The cost of goods sold (before adjustment for under or overapplied overhead) is:
(Multiple Choice)
4.9/5 (77)
(77) Maple Mount Fishery is a canning company in Astoria. The company uses a normal costing system in which factory overhead is applied on the basis of direct labor costs. Budgeted factory overhead for the year was $680,400, and management budgeted $324,000 of direct labor costs. During the year, the company incurred the following actual costs. Direct materials used \ 384,000 Direct labor 306,000 Factory overhead 658,000
Materials-all direct \ 70,000 Work-in-process 41,000 Finished goods 26,000 The December 31 balances of these inventory accounts were ten percent lower than the balances at the beginning of the year.
The adjusted cost of goods sold, after under or overapplied overhead, is: (Round your "predetermined overhead rate" to 1 decimal place.)
(Multiple Choice)
4.9/5 (74)
(74) Harrison allocates factory overhead on the basis of direct labor cost. The overhead rates for the year are 50% for Department A and 100% for Department B. Harrison started and completed job M15 during May. The costs of job M15 are summarized below. Department A Department B Direct materials ? \ 150,000 Direct labor \ 500,000 ? Factory overhead ? \ 200,000 The total manufacturing costs assigned to job M15 during May were $1,400,000.
Required:
Calculate the missing (?) costs (Department A direct materials and factory overhead and Department B direct labor).
(Essay)
4.9/5 (80)
(80) Beckner Inc. is a job-order manufacturer. The company uses a predetermined overhead rate based on direct labor hours to apply overhead to individual jobs. For the current year, estimated direct labor hours are 133,000 and estimated factory overhead is $784,700. The following information is for September. Job X was completed during September, while Job Y was started but not finished. September 1, inventories: Materials \2 4,000 Work-in-process (All Job X) 53,400 Finished goods 105,600 Materials purchases \1 57,000 Direct materials requisitioned: Job X \5 74,000 Job Y 68,000 Direct labor hours: Job X 7,000 Job Y 5,500 Labor costs incurred: Direct labor ( \ 6.00 per hour) \7 5,000 Indirect labor 24,200 Factory supervisory salaries 11,100 Rental costs: Factory \9 ,300 Administrative offices 3,200 Total equipment depreciation costs: Factory \ 10,400 Administrative offices 2,800 Indirect materials used \ 17,800 The total ending work-in-process for September is:
(Multiple Choice)
4.8/5 (79)
(79) Many firms use which one of the following terms to indicate the use of job costing in service industries?
(Multiple Choice)
4.9/5 (74)
(74) The total cost of direct materials, direct labor, and factory overhead transferred from the Work-in-Process Inventory account to the Finished Goods Inventory account during an accounting period is:
(Multiple Choice)
4.9/5 (85)
(85) ABC Company uses a Materials Inventory account to record both direct and indirect materials. ABC charges direct materials to WIP, while indirect materials are charged to the Factory Overhead account. During the month of April, the company has the following cost Total materials (direct and indirect) purchased \ 90,000 Indirect materials issued to production 30,000 Total materials issued to production 110,000 Beginning materials inventory 50,000 The amount of direct materials issued is:
(Multiple Choice)
4.8/5 (69)
(69) Maple Mount Fishery is a canning company in Astoria. The company uses a normal costing system in which factory overhead is applied on the basis of direct labor costs. Budgeted factory overhead for the year was $680,400, and management budgeted $324,000 of direct labor costs. During the year, the company incurred the following actual costs. Direct materials used \ 384,000 Direct labor 306,000 Factory overhead 658,000
Materials-all direct \ 70,000 Work-in-process 41,000 Finished goods 26,000 The December 31 balances of these inventory accounts were ten percent lower than the balances at the beginning of the year.
The amount of direct materials purchased during the year is:
(Multiple Choice)
4.9/5 (73)
(73) Orange, Inc. has identified the following cost drivers for its expected overhead costs for the year: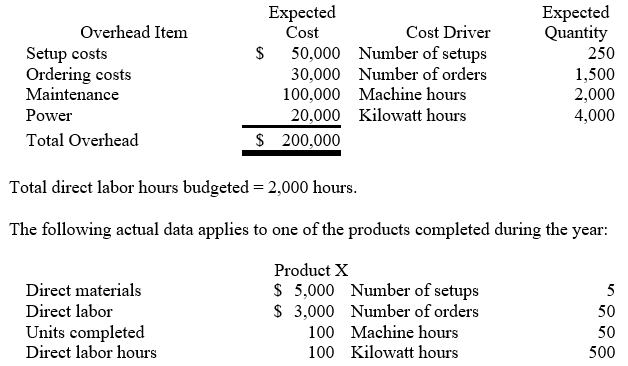 f Orange, Inc.uses machine hours to allocate overhead cost, the unit product cost of Product X will be:
 (Multiple Choice)
4.8/5 (78)
(78) At the end of a fiscal year, overapplied factory overhead should be:
(Multiple Choice)
4.8/5 (80)
(80) ABC Company listed the following data for the current year: Budgeted factory overhead \ 1,044,000 Budgeted direct labor hours 69,600 Budgeted machine hours 24,000 Actual factory overhead 1,037,400 Actual labor hours 72,600 Actual machine hours 23,600 If overhead is applied based on direct labor hours, the overapplied/underapplied overhead is:
(Multiple Choice)
4.9/5 (85)
(85) Boston Manufacturing Company had the following cost information for May. Summary of Direct Materials Requisitions: Department Number Job Number Quantity Cost per Unit 1 88 6,650 \ 8.31 1 88 2,130 2.52 1 88 1,818 9.16 1 88 921 4.18 1 88 63 3.23 Summary of Direct Labor Time Tickets: Department Number Job Number Hours 1 88 554 2 88 321 2 88 618 1 88 25 1 88 613 The labor rate in Department 1 is $10.50 and in Department 2 is $9.50.The overhead rate in Department 1 is based on direct labor-hours, at $4.50 per hour; in Department 2 the rate is 125 percent of direct labor cost.Boston had no beginning work-in-process inventory for May.
Required: Calculate the direct materials, direct labor, factory overhead, and total costs for each job.
(Essay)
4.8/5 (92)
(92) The key distinction between job costing and process costing is:
(Multiple Choice)
4.9/5 (72)
(72) Rivera Company manufactured two products, A and B, during April.For purposes of product costing, an overhead rate of $2.00 per direct-labor hour was used, based on budgeted annual factory overhead of $500,000 and 250,000 budgeted annual direct-labor hours, as follows: Budgeted Budgeted Overhead Hours Department 1 \ 300,000 200,000 Department 2 200,000 50,000 \5 00,000 250,000 The number of labor hours required to manufacture each of these products was: Product A Product B In Department 1 3 1 In Department 2 1 3 Total 3 4 During April, production units for products A and B were 1,000 and 3,000, respectively.
Required:
(1) Using a plantwide overhead rate, what are total overhead costs assigned to products A and B, respectively?
(2) Using departmental overhead rates, what are total overhead costs assigned to products A and B, respectively?
(3) Assume that materials and labor costs per unit of Product B are $10 and that the selling price is established by adding 40% of total costs to cover profit and selling and administrative expenses.What difference in selling price would result from the use of departmental overhead rates?
(Essay)
4.9/5 (88)
(88) Which of the following journal entries is correct if scrap is being incurred and sold for all jobs in common in the amount of $600?
(Multiple Choice)
4.7/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)