



 Chat with AI
Exam 6: Understanding Financial Markets and Institutions

Exam 1: Introduction to Financial Management65 Questions
Exam 2: Reviewing Financial Statements115 Questions
Exam 3: Analyzing Financial Statements131 Questions
Exam 4: Time Value of Money 1: Analyzing Single Cash Flows143 Questions
Exam 5: Time Value of Money 2: Analyzing Annuity Cash Flows148 Questions
Exam 6: Understanding Financial Markets and Institutions104 Questions
Exam 7: Valuing Bonds131 Questions
Exam 8: Valuing Stocks118 Questions
Exam 9: Characterizing Risk and Return113 Questions
Exam 10: Estimating Risk and Return106 Questions
Exam 11: Calculating the Cost of Capital124 Questions
Exam 12: Estimating Cash Flows on Capital Budgeting Projects116 Questions
Exam 13: Weighing Net Present Value and Other Capital Budgeting Criteria121 Questions
Exam 14: Working Capital Management and Policies129 Questions
Exam 15: Financial Planning and Forecasting90 Questions
Exam 16: Assessing Long-Term Debt, Equity, and Capital Structure115 Questions
Exam 17: Sharing Firm Wealth: Dividends, Share Repurchases, and Other Payouts111 Questions
Exam 18: Issuing Capital and the Investment Banking Process119 Questions
Exam 19: International Corporate Finance122 Questions
Exam 20: Mergers and Acquisitions and Financial Distress109 Questions
Select questions type


The Wall Street Journal reports that the rate on 3-year Treasury securities is 7.25% and the rate on 4-year Treasury securities is 8.50%. The one-year interest rate expected in three years is E(4r1), 4.10%. According to the liquidity premium hypotheses, what is the liquidity premium on the 4-year Treasury security, L4?
(Multiple Choice)
4.8/5  (80)
(80) Unbiased Expectations Theory Suppose we observe the following rates: 1R1 = 6%, 1R2 = 7.5%. If the unbiased expectations theory of the term structure of interest rates holds, what is the one-year interest rate expected one year from now, E(2r1)?
(Multiple Choice)
4.9/5 (71)
(71) These money market instruments are short-term funds transferred between financial institutions, usually for no more than one day.
(Multiple Choice)
5.0/5 (81)
(81) Forecasting Interest Rates You note the following yield curve in The Wall Street Journal. According to the unbiased expectations hypothesis, what is the one-year forward rate for the period beginning one year from today, 2f1? 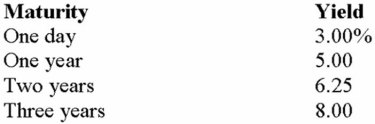
(Multiple Choice)
4.7/5 (74)
(74) All of the following are common shapes for the yield curve except ____________.
(Multiple Choice)
4.8/5 (82)
(82) Suppose we observe the three-year Treasury security rate (1R3) to be 11%, the expected one-year rate next year E(2r1) to be 4%, and the expected one-year rate the following year E(3r1) to be 5%. If the unbiased expectations theory of the term structure of interest rates holds, what is the one-year Treasury security rate, 1R1?
(Multiple Choice)
4.8/5 (82)
(82) Nikki G's Corporation's 10-year bonds are currently yielding a return of 9.25%. The expected inflation premium is 2.0% annually and the real interest rate is expected to be 3.10% annually over the next 10 years. The liquidity risk premium on Nikki G's bonds is 0.1%. The maturity risk premium is 0.10% on 2-year securities and increases by 0.05% for each additional year to maturity. Calculate the default risk premium on Nikki G's 10-year bonds.
(Multiple Choice)
4.8/5 (74)
(74) These provide a forum in which demanders of funds raise funds by issuing new financial instruments, such as stocks and bonds.
(Multiple Choice)
4.9/5 (84)
(84) On May 23, 20XX, the existing or current (spot) one-year, two-year, three-year, and four-year zero-coupon Treasury security rates were as follows: 1R1 = 4.55%, 1R2 = 4.75%, 1R3 = 5.25%, 1R4 = 5.95%
Using the unbiased expectations theory, calculate the one-year forward rates on zero-coupon Treasury bonds for years two, three, and four as of May 23, 20XX.
(Multiple Choice)
4.9/5 (77)
(77) This is the expected or "implied" rate on a short-term security that will originate at some point in the future.
(Multiple Choice)
4.9/5 (88)
(88) Suppose that the current one-year rate (one-year spot rate) and expected one-year T-bill rates over the following three years (i.e., years 2, 3, and 4, respectively) are as follows: 1R1 = 5%, E(2r1) = 6%, E(3r1) = 7.5% E(4r1) = 6.85%
Using the unbiased expectations theory, calculate the current (long-term) rates for one-, two-, three-, and four-year-maturity Treasury securities.
(Multiple Choice)
4.8/5 (89)
(89) Liquidity Premium Hypothesis Based on economists' forecasts and analysis, one-year Treasury bill rates and liquidity premiums for the next four years are expected to be as follows: 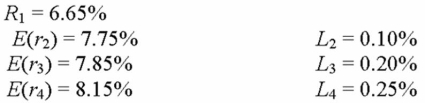 Using the liquidity premium hypothesis, what is the current rate on a four-year Treasury security?
 (Multiple Choice)
4.9/5 (63)
(63) All of the following special provisions benefit security holders except ____________.
(Multiple Choice)
4.9/5 (100)
(100) Interest rates The Wall Street Journal reports that the current rate on 5-year Treasury bonds is 6.50 percent and on 10-year Treasury bonds is 6.75 percent. Assume that the maturity risk premium is zero. Calculate the expected rate on a 5-year Treasury bond purchased five years from today, E(5r1).
(Multiple Choice)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)