



 Chat with AI
Exam 9: Considering Materiality and Audit Risk

Exam 1: The Assurance Services Market47 Questions
Exam 2: The Audit Standards Setting Process67 Questions
Exam 3: Audit Reports139 Questions
Exam 4: Legal Liability Considerations for Auditors115 Questions
Exam 5: Ethics and the Audit Profession116 Questions
Exam 6: Audit Responsibilities and Objectives132 Questions
Exam 7: Nature and Type of Audit Evidence105 Questions
Exam 8: Audit Planning102 Questions
Exam 9: Considering Materiality and Audit Risk113 Questions
Exam 10: Considering Internal Control116 Questions
Exam 11: Considering the Risk of Fraud93 Questions
Exam 12: Implications of Information Technology for the Audit Process106 Questions
Exam 13: Developing the Overall Audit Plan and Audit Program94 Questions
Exam 14: Audit of the Sales and Collection Cycle: Tests of Controls and Substantive Tests of Transactions109 Questions
Exam 15: Audit Sampling for Tests of Controls and Substantive Tests of Transactions119 Questions
Exam 16: Completing the Tests in the Sales and Collection Cycle: Accounts Receivable101 Questions
Exam 17: Audit Sampling for Tests of Details of Balances114 Questions
Exam 18: Audit of the Acquisition and Payment Cycle: Tests of Controls, Substantive Tests of Transactions, and Accounts Payable116 Questions
Exam 19: Completing the Tests in the Acquisition and Payment Cycle: Verification of Selected Accounts101 Questions
Exam 20: Audit of the Inventory and Warehousing Cycle116 Questions
Exam 21: Audit of the Payroll and Personnel Cycle113 Questions
Exam 22: Audit of the Capital Acquisition and Repayment Cycle91 Questions
Exam 23: Audit of Cash and Financial Instruments121 Questions
Exam 24: Audit Completion120 Questions
Exam 25: Other Assurance Services104 Questions
Exam 26: Internal and Governmental Financial Auditing and Operational Auditing72 Questions
Select questions type


Harker,CPA is in the audit planning phase of Dracule Industries.An understanding needs to be established regarding the responsibilities of Harker and Dracule's Management.For each of the task items listed below indicate the responsible party from the list of choices given.Each choice may be used once,more than once or not at all. 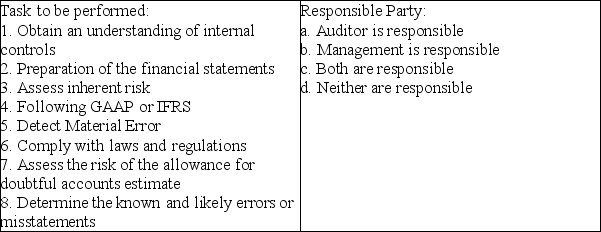
(Short Answer)
4.9/5  (92)
(92) Which of the following is not a primary consideration when assessing inherent risk?
(Multiple Choice)
4.8/5 (96)
(96) When the auditor is attempting to determine the extent to which external users rely on a client's financial statements,they may consider several factors except for:
(Multiple Choice)
5.0/5 (76)
(76) Audit standards require the auditor to consider the combined amount of misstatement early in the audit.This is known as preliminary materiality judgment.List and discuss the three main factors that affect an auditor's preliminary judgment about materiality.
(Essay)
4.7/5 (84)
(84) If acceptable audit risk is low,and inherent risk and control risk are both low,then planned detection risk should be high.
(True/False)
4.9/5 (73)
(73) Due to qualitative factors,certain types of misstatements are likely to be more important to users than others,even if the dollar amounts are the same.Identify two qualitative factors that might significantly affect an auditor's materiality judgment,and give an example of each.
(Essay)
4.7/5 (80)
(80) Which of the following is a correct statement regarding performance materiality?
(Multiple Choice)
4.8/5 (62)
(62) Net assets are the most often used base for deciding materiality.
(True/False)
4.9/5 (79)
(79) Auditors respond to risk primarily by:
I.changing the extent of testing.
II.changing the types of audit procedures.
(Multiple Choice)
4.9/5 (74)
(74) For a private company client,auditors are required to test any internal controls they believe have not been operating effectively during the period under audit.
(True/False)
4.8/5 (84)
(84) Audit standards require the auditor to consider materiality early in the audit.Which statement(s)regarding preliminary materiality are true?
I.Preliminary materiality may change during the engagement.
II.Preliminary materiality is the maximum amount by which the auditor believes the financials could be misstated and still not affect the decisions of reasonable users.
(Multiple Choice)
4.8/5 (78)
(78) If an auditor establishes a relatively high level for materiality,then the auditor will:
(Multiple Choice)
4.7/5 (80)
(80) Total estimated misstatements include known misstatements and projected misstatements plus a sampling error.
(True/False)
4.8/5 (75)
(75) If an auditor assigns a tolerable misstatement of $1,000 to accounts payable,he or she would need to obtain more audit evidence for that account than if $100,000 had been assigned.
(True/False)
4.9/5 (87)
(87) If it is probable that the judgment of a reasonable person will be changed or influenced by the omission or misstatement of information,then that information is,by definition of FASB Statement No.2:
(Multiple Choice)
5.0/5 (78)
(78) An acceptable audit risk assessment of low indicates a risky client requiring more extensive evidence,assignment of more experienced personnel,and/or a more extensive review of audit files.
(True/False)
4.9/5 (81)
(81) When management has an adequate level of integrity for the auditor to accept the engagement but cannot be regarded as completely honest in all dealings,auditors normally:
(Multiple Choice)
4.8/5 (73)
(73) Auditors are responsible for determining whether financial statements are materially misstated,so upon discovering a material misstatement they must bring it to the attention of:
(Multiple Choice)
4.9/5 (92)
(92) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)