



 Chat with AI
Exam 9: Considering Materiality and Audit Risk

Exam 1: The Assurance Services Market47 Questions
Exam 2: The Audit Standards Setting Process67 Questions
Exam 3: Audit Reports139 Questions
Exam 4: Legal Liability Considerations for Auditors115 Questions
Exam 5: Ethics and the Audit Profession116 Questions
Exam 6: Audit Responsibilities and Objectives132 Questions
Exam 7: Nature and Type of Audit Evidence105 Questions
Exam 8: Audit Planning102 Questions
Exam 9: Considering Materiality and Audit Risk113 Questions
Exam 10: Considering Internal Control116 Questions
Exam 11: Considering the Risk of Fraud93 Questions
Exam 12: Implications of Information Technology for the Audit Process106 Questions
Exam 13: Developing the Overall Audit Plan and Audit Program94 Questions
Exam 14: Audit of the Sales and Collection Cycle: Tests of Controls and Substantive Tests of Transactions109 Questions
Exam 15: Audit Sampling for Tests of Controls and Substantive Tests of Transactions119 Questions
Exam 16: Completing the Tests in the Sales and Collection Cycle: Accounts Receivable101 Questions
Exam 17: Audit Sampling for Tests of Details of Balances114 Questions
Exam 18: Audit of the Acquisition and Payment Cycle: Tests of Controls, Substantive Tests of Transactions, and Accounts Payable116 Questions
Exam 19: Completing the Tests in the Acquisition and Payment Cycle: Verification of Selected Accounts101 Questions
Exam 20: Audit of the Inventory and Warehousing Cycle116 Questions
Exam 21: Audit of the Payroll and Personnel Cycle113 Questions
Exam 22: Audit of the Capital Acquisition and Repayment Cycle91 Questions
Exam 23: Audit of Cash and Financial Instruments121 Questions
Exam 24: Audit Completion120 Questions
Exam 25: Other Assurance Services104 Questions
Exam 26: Internal and Governmental Financial Auditing and Operational Auditing72 Questions
Select questions type


The five steps in applying materiality are listed below in random order. 1.Estimate the combined misstatement.
2)Estimate the total misstatement in the segment.
3)Set materiality for the financial statements as a whole.
4)Determine performance materiality.
5)Compare combined estimate with preliminary judgment about materiality.
The first three steps in correct sequence would be:
(Multiple Choice)
4.8/5  (84)
(84) Explain why it is necessary to allocate the preliminary judgment about materiality to individual accounts (segments)in the financial statements.Also explain why allocating to balance sheet accounts is more common than allocating to income statement accounts.
(Essay)
4.8/5 (66)
(66) When evaluating the audit findings,the auditor should be satisfied that the:
(Multiple Choice)
4.9/5 (90)
(90) An auditor who audits a business cycle that has low inherent risk should:
(Multiple Choice)
4.7/5 (68)
(68) Discuss each of the five steps in applying materiality in an audit,and identify the audit phase(s)in which each step is performed.List these steps in the order in which they occur.
(Essay)
4.9/5 (69)
(69) If the audit assurance rate is 95%,then the level of acceptable audit risk is 5%.
(True/False)
4.9/5 (71)
(71) If the total misstatement of an account is known,a sampling error still needs to be determined.
(True/False)
4.8/5 (87)
(87) Acceptable audit risk and the amount of substantive evidence required are inversely related.
(True/False)
4.7/5 (77)
(77) Auditors generally allocate the preliminary judgment about materiality to the:
(Multiple Choice)
4.8/5 (73)
(73) As control risk increases,the amount of substantive evidence the auditor plans to accumulate should increase.
(True/False)
4.9/5 (92)
(92) If an auditor believes the client will have financial difficulties after the audit report is issued,and external users will be relying heavily on the financial statements,the auditor will probably set acceptable audit risk as low.
(True/False)
4.8/5 (83)
(83) Using your knowledge of the relationships among acceptable audit risk,inherent risk,control risk,planned detection risk,performance materiality,and planned evidence,state the effect on planned evidence (increase or decrease)of changing each of the following factors,while the other factors remain unchanged.
1.An increase in acceptable audit risk.________.
2.An increase in inherent risk.________.
3.A decrease in control risk.________.
4.An increase in planned detection risk.________.
5.An increase in performance materiality.________.
(Essay)
4.9/5 (90)
(90) As the acceptable level of detection risk increases,an auditor may change the:
(Multiple Choice)
4.9/5 (92)
(92) The scope paragraph of the standard unqualified auditor's report states that "… the standards require that we plan and perform the audit to obtain ________ assurance about whether the financial statements are free of material misstatement." What type of assurance is given?
(Multiple Choice)
4.8/5 (71)
(71) Based on audit evidence gathered and evaluated,an auditor decides to increase the assessed level of control risk from that originally planned.To achieve an overall audit risk level that is substantially the same as the planned audit risk level,the auditor would:
(Multiple Choice)
4.9/5 (83)
(83) There are several factors that affect an audit firm's business risk and,therefore,acceptable audit risk.Discuss three of these factors.
(Essay)
4.9/5 (88)
(88) In practice,auditors rarely assign numerical probabilities to inherent risk,control risk,or acceptable audit risk.It is more common to assess these risks as high,medium,or low.For each of the four situations below,fill in the blanks for planned detection risk and the amount of evidence you would plan to gather ("planned evidence")using the terms high,medium,or low. 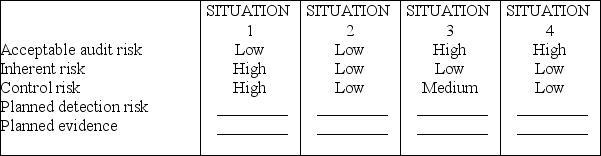
(Essay)
4.9/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)