



 Chat with AI
Exam 8: Competitive Firms and Markets

Exam 1: Introduction50 Questions
Exam 2: Supply and Demand141 Questions
Exam 3: Applying the Supply and Demand Model114 Questions
Exam 4: Consumer Choice115 Questions
Exam 5: Applying Consumer Theory108 Questions
Exam 6: Firms and Production117 Questions
Exam 7: Costs114 Questions
Exam 8: Competitive Firms and Markets117 Questions
Exam 9: Applying the Competitive Model146 Questions
Exam 10: General Equilibrium and Economic Welfare112 Questions
Exam 11: Monopoly138 Questions
Exam 12: Pricing and Advertising125 Questions
Exam 13: Oligopoly and Monopolistic Competition118 Questions
Exam 14: Game Theory99 Questions
Exam 15: Factor Markets93 Questions
Exam 16: Interest Rates, Investments, and Capital Markets110 Questions
Exam 17: Uncertainty112 Questions
Exam 18: Externalities, Open-Access, and Public Goods113 Questions
Exam 19: Asymmetric Information109 Questions
Exam 20: Contracts and Moral Hazards97 Questions
Select questions type


If a competitive firm cannot earn profit at any level of output during a given short-run period,then which of the following is LEAST likely to occur?
(Multiple Choice)
4.8/5  (78)
(78) Suppose a firm has the following total cost function: TC = 100 + 4q2.What is the minimum price necessary for the firm to earn profit? Below what price will the firm shut down in the short run?
(Essay)
4.9/5 (90)
(90) 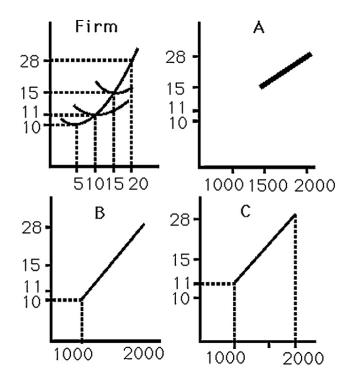 -The above figure shows the cost curves for a typical firm in a market and three possible market supply curves.If there are 100 identical firms,the market supply curve is best represented by
 (Multiple Choice)
5.0/5 (71)
(71) The perfectly competitive model makes a lot of fairly unrealistic assumptions.Why do economics text books still talk a lot about this model?
(Multiple Choice)
4.9/5 (75)
(75) If a competitive firm maximizes short-run profits by producing some quantity of output,which of the following must be true at that level of output?
(Multiple Choice)
4.9/5 (80)
(80) Suppose that for each firm in the competitive market for potatoes,long-run average cost is minimized at $0.20 per pound when 500 pounds are grown.If the long-run supply curve is horizontal,then
(Multiple Choice)
5.0/5 (89)
(89) If a firm operates in a perfectly competitive market,then it will most likely
(Multiple Choice)
4.9/5 (75)
(75) Explain why individual firms in competitive markets face more elastic demand curves than the market as a whole.
(Essay)
4.8/5 (92)
(92) If a profit-maximizing firm finds that,at its current level of production,MR < MC,it will
(Multiple Choice)
4.9/5 (76)
(76) Suppose there are 1000 identical wheat farmers.For each,TC = 10 + q2.Market demand is
Q = 600,000 - 100p.Derive the short-run equilibrium Q,q,and p.Does the typical firm earn a short-run profit?
(Essay)
4.8/5 (89)
(89) If a firm is currently in short-run equilibrium earning a profit,what impact will a lump-sum tax have on its production decision?
(Multiple Choice)
5.0/5 (86)
(86) A competitive firm's supply curve is identical to its marginal cost curve.
(True/False)
4.8/5 (72)
(72) If marginal revenue equals marginal cost,the firm is maximizing profits as long as
(Multiple Choice)
4.9/5 (83)
(83) Suppose all firms in a competitive market are currently in both short-run and long-run equilibrium.What impact will a lump sum tax have on each firm in the short run? in the long run?
(Essay)
4.7/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)