



 Chat with AI
Exam 25: Derivatives and Hedging Risk

Exam 1: Introduction to Corporate Finance67 Questions
Exam 2: Financial Statements and Cash Flow94 Questions
Exam 3: Financial Statements Analysis and Financial Models120 Questions
Exam 4: Discounted Cash Flow Valuation134 Questions
Exam 5: Net Present Value and Other Investment Rules105 Questions
Exam 6: Making Capital Investment Decisions101 Questions
Exam 7: Risk Analysis, Real Options, and Capital Budgeting99 Questions
Exam 8: Interest Rates and Bond Valuation69 Questions
Exam 9: Stock Valuation77 Questions
Exam 10: Risk and Return: Lessons From Market History84 Questions
Exam 11: Return and Risk: the Capital Asset Pricing Model Capm136 Questions
Exam 12: An Alternative View of Risk and Return: The Arbitrage Pricing Theory51 Questions
Exam 13: Risk, Cost of Capital, and Valuation59 Questions
Exam 14: Efficient Capital Markets and Behavioral Challenges65 Questions
Exam 15: Long-Term Financing46 Questions
Exam 16: Capital Structure: Basic Concepts91 Questions
Exam 17: Capital Structure: Limits to the Use of Debt74 Questions
Exam 18: Valuation and Capital Budgeting for the Levered Firm57 Questions
Exam 19: Dividends and Other Payouts90 Questions
Exam 20: Raising Capital73 Questions
Exam 21: Leasing55 Questions
Exam 22: Options and Corporate Finance95 Questions
Exam 23: Options and Corporate Finance: Extensions and Applications46 Questions
Exam 24: Warrants and Convertibles58 Questions
Exam 25: Derivatives and Hedging Risk66 Questions
Exam 26: Short-Term Finance and Planning124 Questions
Exam 27: Cash Management59 Questions
Exam 28: Credit and Inventory Management61 Questions
Exam 29: Mergers, Acquisitions, and Divestitures83 Questions
Exam 30: Financial Distress52 Questions
Exam 31: International Corporate Finance95 Questions
Select questions type


You hold a forward contract to take delivery of U.S. Treasury bonds in 9 months. If the entire term structure of interest rates shifts down over the 9-month period,the value of the forward contract will have _____ on the date of delivery.
(Multiple Choice)
4.9/5  (68)
(68) Interest rate and currency swaps allow one party to exchange a:
(Multiple Choice)
4.8/5 (87)
(87) Duration is defined as the weighted average time to maturity of a financial instrument. Explain how this knowledge can help protect against interest rate risk.
(Essay)
4.7/5 (80)
(80) In percentage terms,higher coupon bonds experience a _______ price change compared with lower coupon bonds of the same maturity given a change in yield to maturity.
(Multiple Choice)
4.8/5 (84)
(84) If the producer of a product has entered into a fixed price sale agreement for that output,the producer faces:
(Multiple Choice)
4.9/5 (80)
(80) There are always ___ counterparties in a credit default swap:
(Multiple Choice)
4.8/5 (84)
(84) 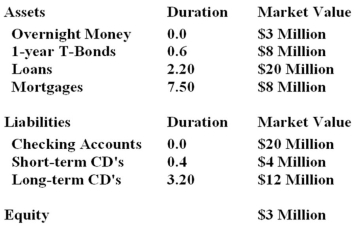 Calculate the duration of Tiger State Bank's assets and liabilities.
Futures market transactions are used to reduce risk. Risk may not be totally offset if:
(Multiple Choice)
4.8/5 (77)
(77) Suppose you agree to purchase one ounce of gold for $984 any time over the next month. The current price of gold is $970. The spot price of gold then falls to $960 the next day. If the agreement is represented by a futures contract marking to market on a daily basis as the price changes,what is your cash flow at the end of the next business day?
(Multiple Choice)
4.9/5 (75)
(75) A farmer with wheat in the fields and who uses the futures market to protect a profit is an example of:
(Multiple Choice)
4.9/5 (90)
(90) Calculate the duration of a 4-year $1,000 face value bond,which pays 8% coupons annually throughout maturity and has a yield to maturity of 9%.
(Multiple Choice)
4.8/5 (61)
(61) You have taken a short position in a futures contract on corn at $2.60 per bushel. Over the next 5 days the contract settled at 2.52,2.57,2.62,2.68,and 2.70. You then decide to reverse your position in the futures market on the fifth day at close. What is the net amount you receive at the end of 5 days?
(Multiple Choice)
4.9/5 (82)
(82) Which of the following terms is not part of a forward contract?
(Multiple Choice)
4.8/5 (86)
(86) Suppose you agree to purchase one ounce of gold for $382 any time over the next month. The current price of gold is $380. The spot price of gold then falls to $377 the next day. If the agreement is represented by a futures contract marking to market on a daily basis as the price changes,what is your cash flow at the end of the next business day?
(Multiple Choice)
4.8/5 (75)
(75) A bank has a $80 million mortgage bond risk position which it hedges in the Treasury bond futures markets at the Chicago Board of Trade. Approximately how many contracts are needed to be held in the hedge?
(Multiple Choice)
4.9/5 (71)
(71) A savings and loan has extremely long-term assets that are currently matched against extremely short-term liabilities. For this S&L:
(Multiple Choice)
4.7/5 (78)
(78) You bought a futures contract for $2.60 per bushel and the contract ended at $2.70 after several days of trading with the following close prices each day: $2.52,$2.57,$2.62,$2.68,and $2.70. What would the mark to market sequence be?
(Multiple Choice)
4.9/5 (69)
(69) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)