



 Chat with AI
Exam 15: Market Risk

Exam 1: Why Are Financial Institutions Special90 Questions
Exam 2: Deposit-Taking Institutions43 Questions
Exam 3: Finance Companies71 Questions
Exam 4: Securities, Brokerage, and Investment Banking91 Questions
Exam 5: Mutual Funds, Hedge Funds, and Pension Funds61 Questions
Exam 6: Insurance Companies80 Questions
Exam 7: Risks of Financial Institutions110 Questions
Exam 8: Interest Rate Risk I110 Questions
Exam 9: Interest Rate Risk II116 Questions
Exam 10: Credit Risk: Individual Loans112 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk51 Questions
Exam 12: Liquidity Risk85 Questions
Exam 13: Foreign Exchange Risk87 Questions
Exam 14: Sovereign Risk89 Questions
Exam 15: Market Risk95 Questions
Exam 16: Off-Balance-Sheet Risk101 Questions
Exam 17: Technology and Other Operational Risks107 Questions
Exam 18: Liability and Liquidity Management38 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees54 Questions
Exam 20: Capital Adequacy102 Questions
Exam 21: Product and Geographic Expansion114 Questions
Exam 22: Futures and Forwards234 Questions
Exam 23: Options, Caps, Floors, and Collars113 Questions
Exam 24: Swaps95 Questions
Exam 25: Loan Sales83 Questions
Exam 26: Securitization Index98 Questions
Select questions type


On December 31, 2001 Historic Bank had long positions of 200,000,000 Japanese Yen and 50,000,000 Swiss Francs. The closing exchange rates were ¥92/$ and Swf 1.89/$. What were the respective positions of the two currencies in dollars?
(Multiple Choice)
4.7/5  (75)
(75) The use of expected shortfall (ES) to measure market risk of a portfolio assumes which of the following?
(Multiple Choice)
4.8/5 (83)
(83) Price volatility of a bond can be estimated by multiplying the bond's modified duration by the adverse daily yield move.
(True/False)
4.7/5 (85)
(85) The back simulation approach to estimating market risk exposure requires the use of daily prices or returns for some period of immediately recent history.
(True/False)
4.8/5 (85)
(85) As compared to the BIS standardized framework model for measuring market risk, the internal models allowed by the large banks are subject to audit by the regulators.
(True/False)
4.8/5 (88)
(88) City bank has six-year zero coupon bonds with a total face value of $20 million. The current market yield on the bonds is 10 percent. What is the price volatility if the maximum potential adverse move in yields is estimated at 20 basis points?
(Multiple Choice)
4.8/5 (75)
(75) The mean change in the value of a portfolio of trading assets has been estimated to be 0 with a standard deviation of 20 percent. Yield changes are assumed to be normally distributed. What is the maximum yield change expected if a 98 percent confidence (one-tailed) limit is used?
(Multiple Choice)
4.9/5 (70)
(70) Daily value at risk (VaR) is defined as the dollar value of a position times price sensitivity.
(True/False)
4.9/5 (81)
(81) The capital requirements of internally generated market risk exposure estimates can be met
(Multiple Choice)
4.9/5 (82)
(82) Which of the following items is not considered to be an advantage of using back simulation over the Risk Metrics approach in developing market risk models?
(Multiple Choice)
4.8/5 (85)
(85) The Volker Rule reduces the specialness of banks operating in the U.S. in maturity intermediation by effectively forcing DTIs to hold a matched maturity book.
(True/False)
4.8/5 (98)
(98) Sumitomo Bank's risk manager has estimated that the VaRs of two of its major assets in its trading portfolio, foreign exchange and bonds, are -$150,000 and -$250,000, respectively. What is the total VaR of Sumitomo's trading portfolio if the correlation among assets is assumed to be 0.80?
(Multiple Choice)
4.8/5 (77)
(77) Consider the following discrete probability distributions of payoffs for 3 securities that are held in a DI's trading portfolio (payoff amounts shown are in $millions): 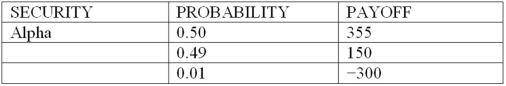
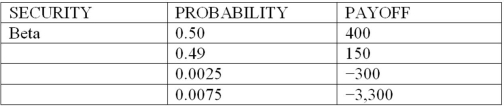
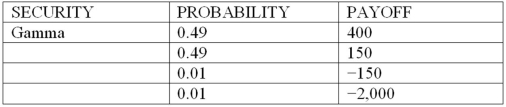 Based on your answers to the previous three questions, which of the following is true?
 (Multiple Choice)
4.9/5 (89)
(89) Sumitomo Bank's risk manager has estimated that the VaRs of two of its major assets in its trading portfolio, foreign exchange and bonds, are -$150,000 and -$250,000, respectively. What is the total VaR of Sumitomo's trading portfolio if the correlation among assets is assumed to be 1.0?
(Multiple Choice)
4.9/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)